

|
시장보고서
상품코드
2109279
베일러 시장 : 시장 기회, 성장요인, 업계 동향 분석 및 예측(2026-2035년)Baler Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

세계의 베일러 시장은 2025년에 49억 달러 규모로 평가되었고, 2035년까지 연평균 복합 성장률(CAGR) 5.2%로 성장할 전망이며, 84억 달러에 이를 것으로 추정되고 있습니다.
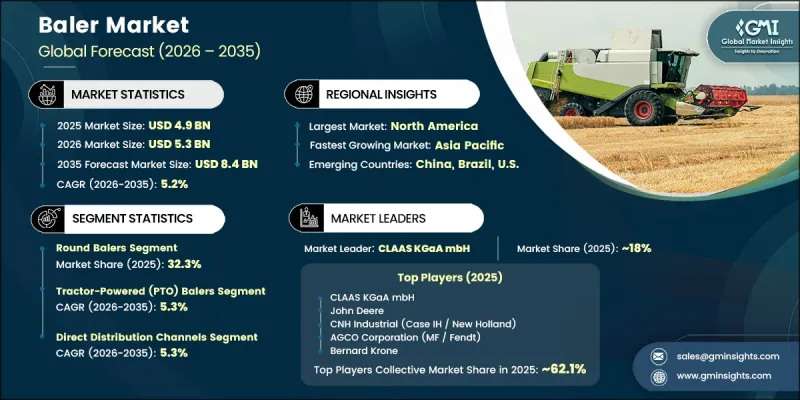
시장 성장은 선진국과 신흥국을 막론하고 농업 기계화, 산업 폐기물 관리, 바이오매스 처리 분야 수요 증가에 의해 주도되고 있습니다. 이 업계를 지탱하고 있는 것은 주로 두 가지 수요원입니다. 하나는 사료나 작물 잔여물을 효율적으로 압축해야 하는 농업 경영이며, 다른 하나는 효과적인 자재 압축 솔루션을 필요로 하는 재활용 및 폐기물 관리 시설입니다. 인구 동향의 변화와 지속적인 도시로의 인구 유출로 인해 농촌 지역의 노동력 부족이 심화되고 있어, 농가들은 노동 집약적인 압축 작업을 기계화된 설비로 대체하도록 촉구받고 있습니다. 특히 선진 농업 지역에서 농장의 평균 규모가 확대되고 있는 것은 베일러 장비에 대한 투자가 가져다주는 경제적 이점을 더욱 강화하고 있습니다. 인건비 상승에 더해 업무 생산성 향상이 요구됨에 따라, 규모에 관계없이 많은 농장이 효율성을 높이고 수작업 의존도를 줄이며 작물 취급 공정을 최적화하는 첨단 베일러 도입을 추진하고 있습니다. 이러한 추세에 따라 대상 시장은 대형 상업 농장에 그치지 않고, 장비 현대화를 통해 생산성 향상을 목표로 하는 중규모 농업 경영체로 꾸준히 확대되고 있습니다.
| 시장 범위 | |
|---|---|
| 개시 연도 | 2025년 |
| 예측 기간 | 2026-2035년 |
| 초기 시장 규모 | 49억 달러 |
| 예측액 | 84억 달러 |
| CAGR | 5.2% |
2025년에는 라운드 베일러 부문이 시장 점유율의 32.3%를 차지했으며, 2035년까지 연평균 성장률(CAGR) 5.2%를 나타낼 것으로 예측됩니다. 라운드 베일러는 다양한 작물 처리에 대응할 수 있는 범용성, 경쟁력 있는 도입 비용, 폭넓은 트랙터 출력에 대응할 수 있는 호환성을 갖추고 있어 건초, 볏짚, 사일리지 처리에서 여전히 가장 선호되는 선택지로 자리 잡고 있습니다. 가변 챔버식 라운드 베일러는 조작의 유연성과 다양한 크기의 베일을 제작할 수 있는 능력 덕분에 계속해서 널리 채택되고 있습니다. 한편, 고정 챔버식 모델은 일상적인 농업 용도에서 신뢰할 수 있는 성능을 추구하는 비용에 민감한 사용자들 사이에서 여전히 인기를 끌고 있습니다.
트랙터 구동식 동력취출장치(PTO) 베일러 부문은 2025년에 54.3%의 시장 점유율을 차지했습니다. 이러한 견고한 시장 지위는 농업 기계의 주요 동력원으로 트랙터가 널리 사용되고 있다는 점에 기인합니다. 표준화된 540 rpm 및 1,000 rpm PTO 시스템과의 호환성 덕분에, 이러한 베일러는 기존 트랙터 군에 쉽게 통합될 수 있어, 성숙한 농업 시장과 신흥 농업 시장 모두에서 기계화된 농업 경영을 위한 실용적이고 효율적인 솔루션이 되고 있습니다.
북미 베일러 시장은 32.9%의 점유율을 차지하고 있으며, 2026-2035년 연평균 성장률(CAGR) 5%를 나타낼 것으로 예측됩니다. 이 지역은 대규모 상업 농업 경영, 충실한 농업 기계 금융 프로그램, 그리고 농업 기계의 안정적인 교체 주기의 혜택을 받고 있습니다. 농업 경영의 지속적인 통합과 효율적인 사료 및 작물 잔여물 관리 솔루션에 대한 수요 증가가 지역 전체에서 첨단 베일링 장비에 대한 꾸준한 투자를 뒷받침하고 있습니다.
베일러 시장 경쟁 구도에는 John Deere, AGCO Corporation(Massey Ferguson/Hesston/Fendt), CLAAS KGaA mbH, Vermeer Corporation, CNH Industrial(Case IH/New Holland), Kuhn Group, Kubota Corporation, Bernard Krone(Krone Group), Lely Industries, Harris Equipment, International Baler Corporation(IBC), Orkel AS, HSM GmbH + Co. KG, Pottinger Landtechnik GmbH 및 몇몇 지역 제조업체 등이 있습니다. 베일러 시장에서 사업을 전개하는 기업들은 경쟁력을 강화하기 위해 제품 혁신, 기술 발전, 그리고 사업 지역 확대에 주력하고 있습니다. 주요 기업들은 기계의 생산성과 운영 효율을 향상시키기 위해 자동화, 정밀 농업과의 통합, 그리고 스마트 모니터링 기술에 투자하고 있습니다. 각 기업은 변화하는 고객의 요구에 부응하기 위해 판매 네트워크 확대, 애프터서비스 체계 강화, 그리고 연비가 우수하고 고성능인 베일러 도입을 추진하고 있습니다. 딜러, 농업 기계 공급업체, 산업 폐기물 관리 기업과의 전략적 제휴는 시장 내 영향력 확대에 기여하고 있습니다. 또한 각 기업은 연구개발, 생산 능력, 디지털 서비스 플랫폼에 대한 투자를 확대하는 한편, 맞춤형 장비 솔루션을 제공함으로써 고객 만족도 향상, 브랜드 충성도 강화, 그리고 전 세계 농업 및 산업 시장에서의 장기적인 성장을 지원하고 있습니다.
자주 묻는 질문
목차
제1장 조사 방법 및 범위
제2장 주요 요약
제3장 업계 인사이트
제4장 경쟁 구도
제5장 시장 추산 및 예측 : 베일러 유형별(2022-2035년)
제6장 시장 추산 및 예측 : 동력원별(2022-2035년)
제7장 시장 추산 및 예측 : 용도별(2022-2035년)
제8장 시장 추산 및 예측 : 유통 채널별(2022-2035년)
제9장 시장 추산 및 예측 : 지역별(2022-2035년)
제10장 기업 개요
AJY 26.08.20The Global Baler Market was valued at USD 4.9 billion in 2025 and is estimated to grow at a CAGR of 5.2% to reach USD 8.4 billion by 2035.
Market growth is driven by rising demand from agricultural mechanization, industrial waste management, and biomass handling applications across both developed and emerging economies. The industry is supported by two primary demand streams: agricultural operations requiring efficient baling of forage and crop residue, and recycling and waste management facilities seeking effective material compaction solutions. Increasing labor shortages in rural areas, driven by demographic changes and ongoing urban migration, are encouraging farmers to replace labor-intensive baling practices with mechanized equipment. The expansion of average farm sizes, particularly across developed agricultural regions, continues to strengthen the economic advantages of investing in baling equipment. Rising labor costs, combined with the need to improve operational productivity, are prompting farms of various sizes to adopt advanced balers that enhance efficiency, reduce dependence on manual labor, and optimize crop handling. This trend is steadily expanding the addressable market beyond large commercial farms to include mid-sized agricultural operations focused on improving productivity through equipment modernization.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $4.9 Billion |
| Forecast Value | $8.4 Billion |
| CAGR | 5.2% |
The round baler segment accounted for 32.3% share in 2025 and is anticipated to grow at a CAGR of 5.2% through 2035. Round balers remain the preferred choice for handling hay, straw, and silage because they offer versatility across multiple crop types, competitive acquisition costs, and compatibility with a wide range of tractor power capacities. Variable-chamber round balers continue to gain wider adoption due to their operational flexibility and ability to produce bales of different sizes, while fixed-chamber models remain popular among cost-conscious users seeking dependable performance for routine agricultural applications.
The tractor-powered power take-off (PTO) balers segment held 54.3% share in 2025. Their strong market position is supported by the widespread use of tractors as the primary power source for agricultural equipment. Compatibility with standardized 540 rpm and 1,000 rpm PTO systems allows these balers to integrate easily with existing tractor fleets, making them a practical and efficient solution for mechanized farming operations across both established and developing agricultural markets.
North America Baler Market held 32.9% share, and is expected to grow at a CAGR of 5% between 2026 and 2035. The region benefits from large-scale commercial farming operations, well-developed agricultural equipment financing programs, and a consistent replacement cycle for farm machinery. Continued consolidation of farming operations and increasing demand for efficient forage and crop residue management solutions are supporting steady investment in advanced baling equipment throughout the region.
The competitive landscape of the baler market includes companies such as John Deere, AGCO Corporation (Massey Ferguson / Hesston / Fendt), CLAAS KGaA mbH, Vermeer Corporation, CNH Industrial (Case IH / New Holland), Kuhn Group, Kubota Corporation, Bernard Krone (Krone Group), Lely Industries, Harris Equipment, International Baler Corporation (IBC), Orkel AS, HSM GmbH + Co. KG, Pottinger Landtechnik GmbH, and several regional manufacturers. Companies operating in the baler market are focusing on product innovation, technological advancements, and geographic expansion to strengthen their competitive positions. Leading manufacturers are investing in automation, precision farming integration, and smart monitoring technologies to improve machine productivity and operational efficiency. Businesses are expanding their distribution networks, enhancing after-sales service capabilities, and introducing fuel-efficient, high-performance balers to meet changing customer requirements. Strategic partnerships with dealers, agricultural equipment suppliers, and industrial waste management companies are helping expand market reach. Companies are also increasing investments in research and development, manufacturing capacity, and digital service platforms while offering customized equipment solutions to improve customer satisfaction, strengthen brand loyalty, and support long-term growth across global agricultural and industrial markets.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Baler type
- 2.2.3 Power source
- 2.2.4 Application
- 2.2.5 Distribution channel
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Raw material & component suppliers
- 3.1.2 OEM manufacturers
- 3.1.3 Dealers, distributors & rental networks
- 3.1.4 End-users & after-sales service providers
- 3.1.5 Value chain margin analysis by node
- 3.1.6 Profit margin
- 3.1.7 Value addition at each stage
- 3.1.8 Factor affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising agricultural mechanization & labor cost inflation driving baler adoption
- 3.2.1.2 Tightening waste management regulations accelerating recycling baler demand
- 3.2.1.3 Growth in bioenergy & renewable feedstock baling creating new application demand
- 3.2.2 Pitfalls & Challenges
- 3.2.2.1 High initial capital expenditure limiting adoption among small & marginal farmers
- 3.2.2.2 Seasonal demand fluctuations & crop cycle dependence creating revenue volatility
- 3.2.3 Opportunities
- 3.2.4 IoT-enabled smart balers predictive maintenance & remote monitoring premium segment
- 3.2.5 Electrification of baling equipment aligned with farm decarbonization mandates
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and innovation landscape
- 3.4.1 Fixed-chamber vs. Variable-chamber baling technology
- 3.4.2 Automation & precision baling systems
- 3.4.3 Iot integration & telematics in modern balers
- 3.4.4 Emerging technologies electric & autonomous balers
- 3.5 Regulatory framework
- 3.5.1 EPA Tier 4 final emissions standards (North America)
- 3.5.2 EU Stage V engine emissions regulations (Europe)
- 3.5.3 Waste management & recycling mandates by region
- 3.5.4 Farm mechanization incentive programs & subsidies
- 3.6 Pricing analysis (driven by primary research)
- 3.6.1 Historical price trend analysis by product category
- 3.6.2 Pricing strategy by player type (premium / value / cost-plus)
- 3.7 Supply chain analysis
- 3.7.1 Key raw materials
- 3.7.2 Supplier concentration & single-source dependency risks
- 3.7.3 Semiconductor shortage impact on baler production timelines
- 3.7.4 Nearshoring & supply chain resilience strategies
- 3.8 Trade data analysis (driven by paid database) (HS code- 8479899565)
- 3.8.1 Import/export volume & value trends by product category
- 3.8.2 Key trade corridors & tariff impact
- 3.9 Impact of AI & generative AI on the market
- 3.9.1 AI-driven disruption of existing business models
- 3.9.2 GenAI use cases & adoption roadmap by segment
- 3.9.3 Risks, limitations & regulatory considerations
- 3.10 Capacity & production landscape (driven by primary research)
- 3.10.1 Installed manufacturing capacity by region & key OEM producer (driven by primary research)
- 3.10.2 Capacity utilization rates & expansion pipelines among top baler manufacturers (driven by primary research)
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East and Africa
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Baler Type, 2022 - 2035 (USD Billion) (Thousand Units)
- 5.1 Key trends
- 5.2 Round balers
- 5.2.1 Fixed-chamber round balers
- 5.2.2 Variable-chamber round balers
- 5.2.3 Mini round balers
- 5.3 Square balers
- 5.3.1 Small square balers
- 5.3.2 Large square balers
- 5.4 Horizontal balers
- 5.4.1 Single-ram horizontal balers
- 5.4.2 Two-ram horizontal balers
- 5.4.3 Continuous/closed-door horizontal balers
- 5.5 Vertical balers
- 5.5.1 Low-density vertical balers
- 5.5.2 High-density vertical balers
- 5.6 Specialty balers
- 5.6.1 Cotton balers
- 5.6.2 Silage balers
- 5.6.3 Hemp & biomass balers
- 5.7 Others
Chapter 6 Market Estimates and Forecast, By Power Source, 2022 - 2035 (USD Billion) (Thousand Units)
- 6.1 Key trends
- 6.2 Tractor-powered (PTO-driven) balers
- 6.2.1 Below 100 HP tractor-compatible balers
- 6.2.2 Above 100 HP tractor-compatible balers
- 6.3 Self-propelled balers
- 6.4 Electric/hydraulic balers
- 6.4.1 Fully electric balers
- 6.4.2 Hydraulic-powered stationary balers
- 6.5 Others
Chapter 7 Market Estimates and Forecast, By Application, 2022 - 2035 (USD Billion) (Thousand Units)
- 7.1 Key trends
- 7.2 Agriculture
- 7.2.1 Hay & forage baling
- 7.2.2 Straw & crop residue baling
- 7.2.3 Cotton baling
- 7.2.4 Silage & bioenergy feedstock baling
- 7.3 Recycling & waste management
- 7.3.1 Cardboard & OCC (old corrugated containers)
- 7.3.2 Plastics baling
- 7.3.3 Metal scrap baling
- 7.3.4 Mixed solid waste baling
- 7.4 Retail & distribution
- 7.4.1 Supermarkets & big-box retail
- 7.4.2 Warehousing & fulfillment centers
- 7.5 Industrial manufacturing
- 7.5.1 Textile & apparel waste baling
- 7.5.2 Rubber & foam baling
- 7.5.3 Paper & pulp industry baling
- 7.6 Others
Chapter 8 Market Estimates and Forecast, By Distribution Channel, 2022 - 2035 (USD Billion) (Thousand Units)
- 8.1 Key trends
- 8.2 Direct
- 8.3 Indirect
Chapter 9 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Billion) (Thousand Units)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Italy
- 9.3.5 Spain
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 Japan
- 9.4.3 India
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global players
- 10.1.1 John Deere
- 10.1.2 CLAAS
- 10.1.3 CNH (Case IH / NH)
- 10.1.4 AGCO (MF / Fendt)
- 10.1.5 Bernard Krone
- 10.1.6 Vermeer
- 10.1.7 Kuhn Group
- 10.1.8 Kubota
- 10.1.9 McHale Engineering
- 10.1.10 Zoomlion
- 10.1.11 Foton Lovol
- 10.1.12 Bollegraaf
- 10.2 Regional players
- 10.2.1 Harris American
- 10.2.2 HSM GmbH
- 10.2.3 Orkel AS
- 10.2.4 Bramidan A/S
- 10.2.5 Minos Agri
- 10.3 Emerging players
- 10.3.1 Abbriata Srl
- 10.3.2 IHI Star Machinery
- 10.3.3 Goweil Maschinenbau
- 10.3.4 Brantner / SITREX


