|
시장보고서
상품코드
2126794
불화 칼륨 시장 예측(-2032년) : 순도, 형태(고체, 액체), 용도(불소화 및 분석용 시약, 유리 에칭, 플럭스), 최종사용자 산업(농약, 화학, 유리, 금속), 지역별Potassium Fluoride Market by Purity, By Form (Solid, Liquid), By Application (Fluorination & Analytical Reagent, Glass Etching, Flux), By End-use Industry (Agrochemical, Chemical, Glass & Metal) and Region - Global Forecast to 2032 |
||||||

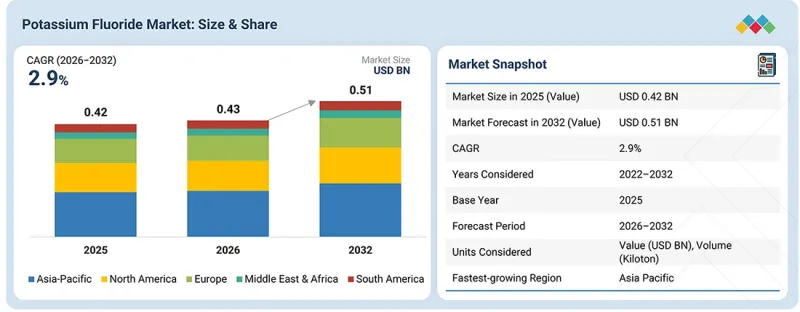
세계의 불화 칼륨 시장 규모는 2026년 4억 3,000만 달러에서 2032년에는 5억 1,000만 달러로 성장하며, 예측 기간 중 CAGR 2.9%로 추이할 것으로 전망되고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2022-2032년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2032년 |
| 단위 | 금액(달러)·킬로톤 |
| 부문 | 순도, 형태, 용도, 최종사용자 산업 |
| 대상 지역 | 북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카 |
불화칼륨 시장은 의약품, 농업, 특수 화학품, 첨단 소재 분야에서 불소화 화학 물질의 이용 확대에 따라 성장을 이어가고 있습니다. 불화칼륨은 불소화 중간체 및 기타 고부가가치 화합물을 제조하기 위한 중요한 불소 공급원입니다. 의약품 연구개발의 활성화, 불소화 원료의약품(API) 생산 증가, 불소화 농약 화합물의 광범위한 사용으로 인해 불화칼륨에 대한 수요는 계속해서 높은 수준을 유지하고 있습니다. 동시에, 아시아태평양, 특히 중국과 인도에서의 특수 불소화합물 생산 확대에 따라 불소화합물의 통합 밸류체인 전반에 걸쳐 소비량이 증가하고 있습니다. 또한 의약품, 전자, 반도체, 첨단 소재 분야에서는 수분 및 미량 원소 불순물에 대한 관리가 더욱 엄격해지고 있으며, 고순도 불화칼륨에 대한 수요도 증가하고 있습니다. 반면, 시장 발전에는 불소 화합물의 유해성, 환경·노동 안전·운송에 관한 엄격한 규제, 전용 취급·보관 설비의 필요성 등의 과제가 있습니다. 또한 일부 공정에서는 선택성, 효율성, 경제성 측면에서 불화칼륨을 능가하는 대체 재료가 채택될 가능성이 있으며, 이는 불화칼륨의 시장 활용을 제한하는 요인이 될 수 있습니다.
"형태별로는 고체 부문이 예측 기간 중 가장 큰 시장 점유율을 차지할 것으로 예상됩니다."
불화칼륨은 주로 무수 분말 또는 결정 형태로 사용되며, 높은 유효 불소 농도를 제공할 수 있을 뿐만 아니라 운송이 용이하고 습기의 영향을 적게 받아 안전하게 보관할 수 있으므로 고체가 주요 형태 범주로 자리 잡고 있습니다. 고체 불화칼륨은 주로 불소화 반응, 특수 화학물질 제조, 농약 배합, 촉매 개발, 유리 제조, 금속 처리에 사용됩니다. 시판 제품은 주로 분말, 결정 또는 과립 형태로 공급되며, 순도는 약 99%에서 99.9% 이상 범위에서 제공됩니다. 고체이기 때문에 배치 공정에서 정확한 계량과 투입이 가능합니다. 한편, 불화칼륨 용액은 일부 용도에서는 취급하기 쉽지만, 다량의 물을 포함하고 있으며, 용매 자체의 운송 및 보관도 필요합니다.
"순도별로는 95%-99% 구간이 예측 기간 중 가장 큰 시장 점유율을 차지할 것으로 전망됩니다."
95%-99%의 순도 범위에 속하는 불화칼륨은 다양한 산업 분야에서 폭넓게 사용되며, 성능, 입수 가능성, 조달 비용의 균형이 가장 뛰어나기 때문에 계속해서 시장 점유율의 대부분을 차지할 것으로 예상됩니다. 이 순도 범위의 불화칼륨은 충분한 불소화 성능과 실용적 유효성을 겸비하고 있으며, 추가적인 고도 정제에 따른 비용을 부담하지 않고도 불소화, 납땜·브레이징, 농업, 유리 에칭, 금속 가공 등에 활용할 수 있습니다. 예를 들어 TANFAC Industries Ltd.는 불소화, 납땜용 플럭스, 살충제 제조 등의 용도로 순도 99% 이상의 불화칼륨을 권장하고 있습니다. 또한 Fengyuan Group은 화학 제품 제조용으로 순도 99%의 산업용 불화칼륨을 공급하고 있습니다. 불화칼륨 공급업체들은 일반적으로, 특히 인 산업 및 금속 산업에서의 용도를 위해 순도 98%에서 99% 범위의 제품을 제조하고 있으며, 이는 이 순도 대역이 폭넓은 용도에 적합함을 나타냅니다. 따라서 95-99% 순도의 불화칼륨에 대한 산업 수요가 높으며, 이는 가장 중요한 시장 부문으로 자리 잡고 있습니다.
"아시아태평양은 예측 기간 중 가장 큰 시장 점유율을 차지할 것으로 예상됩니다."
아시아태평양은 불소 화합물, 농약, 의약품, 전자기기, 첨단 소재 제조 산업이 매우 활발하여 불화칼륨의 주요 지역 시장으로서의 입지를 확고히 하고 있습니다. 특히 중국은 다양한 산업을 대상으로 대량의 불화물을 생산하고 있을 뿐만 아니라, 강력한 공급 및 제조 능력을 보유하고 있으며, 중요한 역할을 수행하고 있습니다. 예를 들어 Henan Yellow River New Material Technology는 연간 약 6만 톤의 불화칼륨 생산 능력을 구축하고 있습니다. 그 밖의 주목할 만한 불화칼륨 생산국으로는 불소화 생산 능력 확충을 추진 중인 인도와, 첨단 불소 화학 산업이 큰 수요를 창출하고 있는 것본 및 한국을 들 수 있습니다. 예를 들어 다이킨(Daikin Industries)은 일본과 한국 등에서 불소화합물의 생산 능력을 갖추고 있습니다. 이 지역의 대규모 생산 능력, 통합된 공급망, 불소화합물 제조의 확대를 통해 아시아태평양은 불화칼륨 시장에서 주도적인 위치를 확립하고 있습니다.
이 보고서에서는 전 세계 불화칼륨 시장을 조사하여 시장 개요, 시장 성장에 영향을 미치는 각종 요인에 대한 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추이 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 정리하여 전해드립니다.
자주 묻는 질문
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술의 진보, AI에 의한 영향, 특허, 혁신, 향후 응용
제7장 규제 상황과 지속가능성 구상
제8장 고객 상황과 구매 행동
제9장 불화 칼륨 시장 : 형태별
제10장 불화 칼륨 시장 : 순도별
제11장 불화 칼륨 시장 : 용도별
제12장 불화 칼륨 시장 : 최종사용자 산업별
제13장 불화 칼륨 시장 : 지역별
제14장 경쟁 구도
제15장 기업 개요
제16장 조사 방법
제17장 부록
KSAThe global potassium fluoride market is projected to grow from USD 0.43 billion in 2026 to USD 0.51 billion by 2032, registering a CAGR of 2.9% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | Value (USD Million/Billion), Volume (Kiloton) |
| Segments | Purity, Form, Application, End Use Industry |
| Regions covered | North America, South America, Europe, Asia Pacific, Middle East & Africa |
The potassium fluoride market has been growing due to the growing use of fluorination chemistry in pharmaceuticals, agriculture, specialty chemicals, and advanced materials, with potassium fluoride being an important source of fluoride to produce fluorinated intermediates and other high-value compounds. The increasing pharmaceutical R&D, increased production of fluorinated active pharmaceutical ingredients, and extensive use of fluorinated agrochemical compounds are maintaining high demand for potassium fluoride. Simultaneously, the growth of specialty fluorochemical production in the Asia Pacific region, especially in China and India, is increasing consumption through integrated fluorochemical value chains. The demand for high-purity potassium fluoride is also going up as pharmaceuticals, electronics, semiconductors, and advanced materials require stricter control of moisture and trace-element impurities. However, the market development faces obstacles related to the hazardous nature of fluoride compounds, strict regulations for environmental, occupational safety, and transportation, and the necessity for special handling and storage infrastructure. Besides, the adoption of alternatives to potassium fluoride in processes where they outperform potassium fluoride in selectivity, efficiency, and economics might limit the use of potassium fluoride in the market.
"By Form, Solid segment is anticipated to account for the largest market share during the forecast period."
The solid form is the dominant form category in the potassium fluoride market since potassium fluoride is mainly used as an anhydrous powder or crystal and can provide high active fluorine concentration, simple transportation, and safe storage, stable from the impact of moisture. Solid potassium fluoride is used mainly in fluorination reactions, production of specialty chemicals, formulation of agrochemicals, development of catalysts, production of glass, and metal treatment. Commercially, these products are supplied mainly in the form of powders, crystals, or granules, being offered in the range of purity of about 99% and above 99.9%. Their solid state allows for accurate dosing and introduction in batch operations. Also, although potassium fluoride solutions are easy to handle in selected applications, they contain a lot of water and thus require additional transportation and storage of the solvent.
By purity, the 95%-99% segment is anticipated to account for the largest market share during the forecast period.
The purity category of potassium fluoride in the range of 95% - 99% is anticipated to continue holding the dominant market share, as this category represents the most reasonable combination of performance, availability, and procurement cost due to the wide scope of applications in multiple industries. Potassium fluoride in this purity range combines acceptable fluoride behavior with performance effectiveness, thus making it favorable for fluorination, agriculture, glass etching, soldering and brazing, metal processing, and other industries without the necessity of incurring extra expenses on further refinement. For instance, TANFAC Industries Ltd. recommends the use of potassium fluoride with the desired purity level of at least 99% for such applications as fluorination, solder flux, and insecticide production. Another manufacturer, Fengyuan Group, provides technical-grade potassium fluoride at 99% purity for the purposes of chemical manufacturing. The suppliers of potassium fluoride in general produce it in the quantity ranging from 98% to 99% purity specifically for the phosphorus industry and metal industry applications, thus confirming the extensive applicability of this range of purity. Hence, there is great industrial demand for potassium fluoride within the 95% to 99% purity range, making this market segment the most significant.
"Asia Pacific is anticipated to account for the largest market share during the forecast period.
Asia Pacific has established itself as the leading regional market of potassium fluoride owing to a very strong manufacturing industry for fluorinated compounds, agrochemicals, pharmaceuticals, electronics, and advanced materials. Countries such as China play a vital role in this regard on account of the massive levels of fluoride produced for different sectors, as well as their own supply and manufacturing capacities. For instance, Henan Yellow River New Material Technology Co., Ltd. has established operational capabilities of around 60,000 MT per year of potassium fluoride. Other notable potassium fluoride producers include India, which, too, is ramping up its fluorination capabilities, and Japan and South Korea, whose advanced fluorinated chemical industries generate significant demand. For instance, Daikin Industries has developed production capabilities in the fluorinated chemicals space in Japan and South Korea, among others. The region's huge production capabilities, integrated supply chains, and increasing manufacturing of fluorinated chemicals have made Asia Pacific a leader in the potassium fluoride market.
In-depth interviews were conducted with Chief Executive Officers (CEOs), marketing directors, other innovation and technology directors, and executives from various key organizations operating in the Potassium fluoride market, and information was gathered from secondary research to determine and verify the market size of several segments.
- By Company Type: Tier 1 - 50%, Tier 2 - 30%, and Tier 3 - 20%
- By Designation: Managers - 15%, Directors - 20%, and Others - 65%
- By Country: Asia Pacific - 35%, Europe- 25%, North America- 25% South America - 5%, Middle East & Africa- 10%.
The Potassium fluoride market comprises of major companies, such as Aarti Industries Ltd. (India), Gujarat Fluorochemicals Limited (India), Derivados del Fluor SAU (Spain), TANFAC Industries Ltd. (India), Navin Fluorine International Limited (India), SB Chemicals (India), Henan Yellow River New Material Technology Co., Ltd. (China), Chengde Yingke Fine Chemical Co., Ltd., (China), Nantong Jinxing Fluorides Chemical Co., Ltd. (China), Fengyuan Group (China). The study includes in-depth competitive analysis of these key players in the Potassium fluoride market, with their company profiles, recent developments, and key market strategies.
Research Coverage
This report segments the market for potassium fluoride market on the basis of purity, form, application, end use industry, and region. It provides estimations for the overall value of the market across various regions. A detailed analysis of key industry players has been conducted to provide insights into their business overviews, products & services, key strategies, and expansions associated with the Potassium fluoride market.
Key benefits of buying this report
This research report is focused on various levels of analysis-industry analysis (industry trends), market ranking analysis of top players, and company profiles, which together provide an overall view of the competitive landscape; emerging and high-growth segments of the potassium fluoride market; high-growth countries; and market drivers, restraints, opportunities, and challenges.
The report provides insights into the following points:
- Analysis of drivers (Semiconductor fluorination and etching chemistry is tightening electronic-grade Potassium Fluoride supply, Aluminum surface treatment is increasing fluoride consumption intensity per processing line, Specialty fluorochemical synthesis is expanding demand for anhydrous and low-moisture Potassium Fluoride, Pharmaceutical and fine-chemical fluorination is increasing demand for controlled-reactivity fluoride sources), restraints (Alternative fluorides are limiting Potassium Fluoride penetration in several bulk industrial applications, Fluoride discharge regulation is constraining growth in environmentally sensitive downstream sectors), opportunities (Electronic-grade Potassium Fluoride purification remains underdeveloped outside Northeast Asia, Battery-electrolyte fluorination intermediates offer a premium growth avenue for specialty producers, Fluoride recovery and circular processing can create a differentiated low-carbon business model), and challenges (Hygroscopicity and corrosivity are complicating storage, logistics, and customer handling economics, Achieving ultra-low impurity specifications requires expensive purification and analytical infrastructure) influencing the growth of Potassium fluoride market
- Market Penetration: Comprehensive information on the Potassium fluoride offered by top players in the Potassium fluoride market
- Product Development/Innovation: Detailed insights on upcoming technologies, product launches, expansions, and acquisitions in the Potassium fluoride market
- Market Development: Comprehensive information about lucrative emerging markets; the report analyzes the markets for Potassium fluoride across regions and countries.
- Market Capacity: Production capacity of the companies is provided wherever available, with upcoming capacities for the Potassium fluoride market
- Competitive Assessment: In-depth assessment of market shares, strategies, products, and manufacturing capabilities of leading players in the Potassium fluoride market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.3.5 UNIT CONSIDERED
- 1.4 STAKEHOLDERS
- 1.5 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN POTASSIUM FLUORIDE MARKET
- 3.2 POTASSIUM FLUORIDE MARKET, BY FORM AND REGION
- 3.3 POTASSIUM FLUORIDE MARKET, BY PURITY
- 3.4 POTASSIUM FLUORIDE MARKET, BY APPLICATION
- 3.5 POTASSIUM FLUORIDE MARKET, BY END-USE INDUSTRY
- 3.6 POTASSIUM FLUORIDE MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising consumption of specialized etching agents in semiconductor fabrication
- 4.2.1.2 Demand in aluminum surface treatment
- 4.2.1.3 Specialty fluorochemical synthesis accelerating adoption of anhydrous potassium fluoride
- 4.2.1.4 Adoption in pharmaceutical and fine-chemical fluorination
- 4.2.2 RESTRAINTS
- 4.2.2.1 Availability of alternative fluorides
- 4.2.2.2 Stringent fluoride discharge regulation
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Geographic concentration of electronic-grade potassium fluoride purification in Northeast Asia
- 4.2.3.2 Battery-electrolyte fluorination intermediates offer a premium growth avenue for specialty producers
- 4.2.3.3 Development of fluoride recovery and circular processing
- 4.2.4 CHALLENGES
- 4.2.4.1 Complex storage, logistics, and customer handling economics
- 4.2.4.2 Need for expensive purification and analytical infrastructure to achieve ultra-low impurity specifications
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN POTASSIUM FLUORIDE MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMICS INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN POTASSIUM FLUORIDE INDUSTRY
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 PRICING ANALYSIS
- 5.4.1 AVERAGE SELLING PRICE, BY REGION (2022-2025)
- 5.4.2 AVERAGE SELLING PRICE, BY PURITY (2022-2025)
- 5.4.3 AVERAGE SELLING PRICE, BY FORM (2022-2025)
- 5.4.4 AVERAGE SELLING PRICE, BY APPLICATION (2022-2025)
- 5.4.5 AVERAGE SELLING PRICE, BY END-USE INDUSTRY (2022-2025)
- 5.4.6 AVERAGE SELLING PRICE OF KEY PLAYERS, BY FORM, 2025
- 5.5 ECOSYSTEM ANALYSIS
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 282619)
- 5.6.2 EXPORT SCENARIO (HS CODE 282619)
- 5.7 KEY CONFERENCES & EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 HENAN YELLOW RIVER NEW MATERIAL TECHNOLOGY CO., LTD. CAPACITY LEADERSHIP IN POTASSIUM FLUORIDE
- 5.10.2 TANFAC INDUSTRIES LTD. POTASSIUM FLUORIDE FOR FLUORINATION CHEMISTRY IN CROP PROTECTION AND PHARMACEUTICAL INTERMEDIATES
- 5.10.3 CHENGDE YINGKE FINE CHEMICAL CO., LTD. MULTI-FORM POTASSIUM FLUORIDE FOR GLASS AND ELECTRONIC MATERIAL APPLICATIONS
- 5.11 IMPACT OF 2025 US TARIFF ON POTASSIUM FLUORIDE MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON REGIONS
- 5.11.4.1 Asia Pacific
- 5.11.4.2 North America
- 5.11.4.3 Europe
- 5.11.5 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 CONTINUOUS FLOW FLUORINATION REACTORS
- 6.1.2 ADVANCED RECRYSTALLIZATION AND PURIFICATION TECHNIQUES
- 6.1.3 CLOSED-LOOP HAZARDOUS MATERIAL HANDLING SYSTEMS
- 6.1.4 REAL-TIME PROCESS ANALYTICS AND QUALITY MONITORING
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 ANHYDROUS HYDROFLUORIC ACID PRODUCTION SYSTEMS
- 6.2.2 HAZARDOUS CHEMICAL STORAGE AND TRANSPORT CONTAINMENT SYSTEMS
- 6.2.3 ANALYTICAL TESTING AND CERTIFICATION INSTRUMENTATION
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 HYDROFLUORIC ACID AS A DIRECT FLUORINATING AND ETCHING AGENT
- 6.3.2 SODIUM FLUORIDE AND POTASSIUM BIFLUORIDE AS ALTERNATIVE FLUORIDE SALTS
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 ULTRA-HIGH-PURITY GRADE EXPANSION
- 6.4.2 BACKWARD INTEGRATION INTO FLUORSPAR AND HYDROFLUORIC ACID
- 6.4.3 CLOSED-LOOP AND AUTOMATED HAZARDOUS MATERIAL HANDLING
- 6.4.4 DIGITAL PROCESS MONITORING AND QUALITY TRACEABILITY
- 6.4.5 FLUORIDE RECOVERY AND CIRCULARITY RESEARCH
- 6.4.6 APPLICATION-SPECIFIC FORM DIFFERENTIATION
- 6.4.7 REGULATORY AND SUSTAINABILITY DOCUMENTATION SYSTEMS
- 6.4.8 EXPANDED ANALYTICAL CERTIFICATION CAPABILITY
- 6.5 PATENT ANALYSIS
- 6.5.1 METHODOLOGY
- 6.5.2 GRANTED PATENTS, 2016-2025
- 6.5.2.1 Publication trends for last ten years
- 6.5.3 INSIGHTS
- 6.5.4 LEGAL STATUS
- 6.5.5 JURISDICTION ANALYSIS
- 6.5.6 TOP APPLICANTS
- 6.5.7 LIST OF MAJOR PATENTS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 NEXT-GENERATION BATTERY ELECTROLYTE ADDITIVES
- 6.6.2 ADVANCED SEMICONDUCTOR NODE ETCHING
- 6.6.3 PHARMACEUTICAL FLUORINATION AND RADIOTRACER SYNTHESIS
- 6.6.4 CIRCULAR FLUORIDE RECOVERY AND SUSTAINABLE SOURCING
- 6.7 IMPACT OF AI/GEN AI ON POTASSIUM FLUORIDE MARKET
- 6.7.1 TOP USE CASES AND MARKET POTENTIAL
- 6.7.2 BEST PRACTICES IN POTASSIUM FLUORIDE PROCESSING
- 6.7.3 CASE STUDIES OF AI IMPLEMENTATION IN POTASSIUM FLUORIDE MARKET
- 6.7.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.5 CLIENT'S READINESS TO ADOPT GENERATIVE AI IN POTASSIUM FLUORIDE MARKET
- 6.8 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 6.8.1 GUJARAT FLUOROCHEMICALS LIMITED - BUILDING A DEDICATED PATH INTO ELECTRONICS-GRADE FLUOROCHEMICALS
- 6.8.2 TANFAC INDUSTRIES LTD. - BACKWARD INTEGRATION THROUGH STRATEGIC OWNERSHIP CHANGE
- 6.8.3 HENAN YELLOW RIVER NEW MATERIAL TECHNOLOGY CO., LTD. - SCALING A DEDICATED SINGLE-SITE PRODUCTION BASE
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 FLUORIDE RECOVERY AND CIRCULAR SOURCING RESEARCH
- 7.2.2 BACKWARD INTEGRATION TO REDUCE SUPPLY CHAIN EMISSIONS
- 7.2.3 RENEWABLE ENERGY ADOPTION IN MANUFACTURING
- 7.2.4 ANALYTICS-DRIVEN ENERGY AND EMISSIONS MANAGEMENT
- 7.2.5 HAZARDOUS MATERIAL HANDLING AUTOMATION FOR ENVIRONMENTAL RISK REDUCTION
- 7.2.6 WATER STEWARDSHIP IN PRODUCTION PROCESSES
- 7.3 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, & ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS AND BUYING CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
- 8.5.1 UPSTREAM FEEDSTOCK INTEGRATION
- 8.5.2 PURITY-TIER PREMIUM CAPTURE
- 8.5.3 APPLICATION AND END-USE DIVERSIFICATION
- 8.5.4 DIGITAL PROCESS EFFICIENCY
- 8.5.5 OWNERSHIP AND STRATEGIC CONSOLIDATION
9 POTASSIUM FLUORIDE MARKET, BY FORM
- 9.1 INTRODUCTION
- 9.2 SOLID
- 9.2.1 DEMAND OF CRITICAL ANHYDROUS REAGENT FOR HIGH-YIELD HALEX ORGANIC SYNTHESIS TO DRIVE MARKET
- 9.3 LIQUID
- 9.3.1 ENABLES DUST-FREE, PRE-MIXED PRECISION CHEMICAL DELIVERY REQUIRED FOR SENSITIVE ELECTRONICS FABRICATION AND INDUSTRIAL ETCHING LINES
10 POTASSIUM FLUORIDE MARKET, BY PURITY
- 10.1 INTRODUCTION
- 10.2 95%-99%
- 10.2.1 DEMAND FOR INDUSTRIAL-GRADE POTASSIUM FLUORIDE DRIVING MARKET
- 10.3 >99%
- 10.3.1 SEMICONDUCTOR AND API SYNTHESIS PROPEL SURGE IN >99% ULTRA-HIGH-PURITY GRADE
11 POTASSIUM FLUORIDE MARKET, BY APPLICATION
- 11.1 INTRODUCTION
- 11.2 FLUORINATION & ANALYTICAL REAGENT
- 11.2.1 SURGING HALEX ORGANIC SYNTHESIS DRIVING DEMAND FOR POTASSIUM FLUORIDE AS CORE FLUORINATION REAGENT
- 11.3 GLASS ETCHING
- 11.3.1 CONTROLLED FLUORIDE ACTIVITY SUPPORTING STABLE DEMAND IN GLASS PROCESSING
- 11.4 FLUX
- 11.4.1 FLUX PERFORMANCE SUSTAINING INDUSTRIAL FLUORIDE DEMAND IN JOINING AND METALLURGICAL OPERATIONS
- 11.5 METAL SURFACE TREATMENT
- 11.5.1 SURFACE-TREATMENT CHEMISTRY INCREASING RECURRING FLUORIDE CONSUMPTION
- 11.6 CATALYST
- 11.6.1 SPECIALTY CATALYTIC SYSTEMS CREATING HIGH-VALUE NICHE FOR POTASSIUM FLUORIDE
- 11.7 ELECTROLYTE ADDITIVE
- 11.7.1 BATTERY-LINKED FLUORINATION CHEMISTRY OPENING PREMIUM SPECIALTY DEMAND
- 11.8 AGROCHEMICAL FORMULATIONS
- 11.8.1 FLUORIDE-ENABLED SYNTHESIS SUPPORTING DEMAND IN AGROCHEMICAL MANUFACTURING
- 11.9 OTHER APPLICATIONS
12 POTASSIUM FLUORIDE MARKET, BY END-USE INDUSTRY
- 12.1 INTRODUCTION
- 12.2 AGROCHEMICAL
- 12.2.1 FLUORINATED CROP-PROTECTION MANUFACTURING SUSTAINING DEMAND
- 12.3 CHEMICAL
- 12.3.1 SPECIALTY CHEMICAL INTEGRATION DRIVING MARKET GROWTH
- 12.4 GLASS & METAL
- 12.4.1 GROWTH IN INDUSTRIAL PROCESSING DRIVING MARKET GROWTH
- 12.5 PHARMACEUTICAL
- 12.5.1 HIGH-PURITY FLUORINATION POSITIONING PHARMACEUTICALS AS PREMIUM QUALIFICATION-DRIVEN SEGMENT
- 12.6 ELECTRONICS & SEMICONDUCTOR
- 12.6.1 ULTRA-HIGH-PURITY REQUIREMENTS SUPPORTING MARKET GROWTH
- 12.7 OTHER END-USE INDUSTRIES
13 POTASSIUM FLUORIDE MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 ASIA PACIFIC
- 13.2.1 CHINA
- 13.2.1.1 Consolidating integrated fluorochemical capacity reinforcing global market leadership
- 13.2.2 JAPAN
- 13.2.2.1 Advancing electronic-grade fluorides driving premium market structure
- 13.2.3 INDIA
- 13.2.3.1 Expanding pharmaceuticals and specialty fluorochemicals creating high-growth opportunity
- 13.2.4 SOUTH KOREA
- 13.2.4.1 Strengthening semiconductor and battery ecosystems fueling demand
- 13.2.5 REST OF ASIA PACIFIC
- 13.2.1 CHINA
- 13.3 NORTH AMERICA
- 13.3.1 US
- 13.3.1.1 Accelerating semiconductor and pharmaceutical fluorination strengthening specialty demand
- 13.3.2 CANADA
- 13.3.2.1 Robust aluminum smelting operations and specialty fine chemical synthesis driving demand
- 13.3.3 MEXICO
- 13.3.3.1 Expanding manufacturing and surface-treatment activity increasing industrial fluoride use
- 13.3.1 US
- 13.4 EUROPE
- 13.4.1 GERMANY
- 13.4.1.1 Consumption in advanced manufacturing driving high-purity fluorochemical demand
- 13.4.2 ITALY
- 13.4.2.1 Expanding specialty chemicals and pharmaceutical processing supporting steady growth
- 13.4.3 FRANCE
- 13.4.3.1 Strengthening pharmaceutical and specialty chemical value chains enhancing market resilience
- 13.4.4 UK
- 13.4.4.1 Rebuilding specialty chemical resilience supporting high-value fluoride consumption
- 13.4.5 SPAIN
- 13.4.5.1 Expanding industrial processing and specialty manufacturing widening fluoride applications
- 13.4.6 REST OF EUROPE
- 13.4.1 GERMANY
- 13.5 MIDDLE EAST & AFRICA
- 13.5.1 GCC COUNTRIES
- 13.5.1.1 Saudi Arabia
- 13.5.1.1.1 Diversifying chemicals and aluminum processing expanding industrial fluoride demand
- 13.5.1.2 UAE
- 13.5.1.2.1 Advanced industrial and technology ecosystems creating high-value demand
- 13.5.1.3 Rest of GCC countries
- 13.5.1.1 Saudi Arabia
- 13.5.2 SOUTH AFRICA
- 13.5.2.1 Growing mining and metallurgical processing sustaining industrial fluoride demand
- 13.5.3 REST OF MIDDLE EAST & AFRICA
- 13.5.1 GCC COUNTRIES
- 13.6 SOUTH AMERICA
- 13.6.1 BRAZIL
- 13.6.1.1 Expanding agrochemicals and specialty manufacturing anchoring regional leadership
- 13.6.2 ARGENTINA
- 13.6.2.1 Strengthening pharmaceuticals and specialty industrial processing fueling demand
- 13.6.3 REST OF SOUTH AMERICA
- 13.6.1 BRAZIL
14 COMPETITIVE LANDSCAPE
- 14.1 INTRODUCTION
- 14.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN
- 14.3 MARKET SHARE ANALYSIS, 2025
- 14.3.1 HENAN YELLOW RIVER NEW MATERIAL TECHNOLOGY CO., LTD.
- 14.3.2 GUJARAT FLUOROCHEMICALS LIMITED
- 14.3.3 TANFAC INDUSTRIES LTD.
- 14.3.4 FENGYUAN GROUP
- 14.3.5 CHENGDE YINGKE FINE CHEMICAL CO., LTD.
- 14.4 REVENUE ANALYSIS
- 14.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 14.5.1 STARS
- 14.5.2 EMERGING LEADERS
- 14.5.3 PERVASIVE PLAYERS
- 14.5.4 PARTICIPANTS
- 14.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 14.5.5.1 Company footprint
- 14.5.5.2 Region footprint
- 14.5.5.3 Form footprint
- 14.5.5.4 Purity footprint
- 14.5.5.5 End-use industry footprint
- 14.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 14.6.1 PROGRESSIVE COMPANIES
- 14.6.2 RESPONSIVE COMPANIES
- 14.6.3 DYNAMIC COMPANIES
- 14.6.4 STARTING BLOCKS
- 14.6.5 COMPETITIVE BENCHMARKING
- 14.6.5.1 Detailed list of key startups/SMEs
- 14.6.5.2 Competitive benchmarking of key startups/SMEs
- 14.7 BRAND/PRODUCT COMPARISON
- 14.8 COMPANY VALUATION AND FINANCIAL METRICS
- 14.9 COMPETITIVE SCENARIO
- 14.9.1 DEALS
15 COMPANY PROFILES
- 15.1 KEY PLAYERS
- 15.1.1 AARTI INDUSTRIES LTD.
- 15.1.1.1 Business overview
- 15.1.1.2 Products/Solutions/Services offered
- 15.1.1.3 MnM view
- 15.1.1.3.1 Right to win
- 15.1.1.3.2 Strategic choices
- 15.1.1.3.3 Weaknesses and competitive threats
- 15.1.2 GUJARAT FLUOROCHEMICALS LIMITED
- 15.1.2.1 Business overview
- 15.1.2.2 Products/Solutions/Services offered
- 15.1.2.3 MnM view
- 15.1.2.3.1 Right to win
- 15.1.2.3.2 Strategic choices
- 15.1.2.3.3 Weaknesses and competitive threats
- 15.1.3 DERIVADOS DEL FLUOR SAU
- 15.1.3.1 Business overview
- 15.1.3.2 Products/Solutions/Services offered
- 15.1.3.3 MnM view
- 15.1.3.3.1 Right to win
- 15.1.3.3.2 Strategic choices
- 15.1.3.3.3 Weaknesses and competitive threats
- 15.1.4 TANFAC INDUSTRIES LTD.
- 15.1.4.1 Business overview
- 15.1.4.2 Products/Solutions/Services offered
- 15.1.4.3 Recent developments
- 15.1.4.3.1 Deals
- 15.1.4.4 MnM view
- 15.1.4.4.1 Right to win
- 15.1.4.4.2 Strategic choices
- 15.1.4.4.3 Weaknesses and competitive threats
- 15.1.5 NAVIN FLUORINE INTERNATIONAL LIMITED
- 15.1.5.1 Business overview
- 15.1.5.2 Products/Solutions/Services offered
- 15.1.5.3 MnM view
- 15.1.5.3.1 Right to win
- 15.1.5.3.2 Strategic choices
- 15.1.5.3.3 Weaknesses and competitive threats
- 15.1.6 SB CHEMICALS
- 15.1.6.1 Business overview
- 15.1.6.2 Products/Solutions/Services offered
- 15.1.6.3 MnM view
- 15.1.6.3.1 Right to win
- 15.1.6.3.2 Strategic choices
- 15.1.6.3.3 Weaknesses and competitive threats
- 15.1.7 HENAN YELLOW RIVER NEW MATERIAL TECHNOLOGY CO., LTD.
- 15.1.7.1 Business overview
- 15.1.7.2 Products/Solutions/Services offered
- 15.1.7.3 MnM view
- 15.1.7.3.1 Right to win
- 15.1.7.3.2 Strategic choices
- 15.1.7.3.3 Weaknesses and competitive threats
- 15.1.8 CHENGDE YINGKE FINE CHEMICAL CO., LTD.
- 15.1.8.1 Business overview
- 15.1.8.2 Products/Solutions/Services offered
- 15.1.8.3 MnM view
- 15.1.8.3.1 Right to win
- 15.1.8.3.2 Strategic choices
- 15.1.8.3.3 Weaknesses and competitive threats
- 15.1.9 NANTONG JINXING FLUORIDES CHEMICAL CO., LTD.
- 15.1.9.1 Business overview
- 15.1.9.2 Products/Solutions/Services offered
- 15.1.9.3 MnM view
- 15.1.9.3.1 Right to win
- 15.1.9.3.2 Strategic choices
- 15.1.9.3.3 Weaknesses and competitive threats
- 15.1.10 FENGYUAN GROUP
- 15.1.10.1 Business overview
- 15.1.10.2 Products/Solutions/Services offered
- 15.1.10.3 MnM view
- 15.1.10.3.1 Right to win
- 15.1.10.3.2 Strategic choices
- 15.1.10.3.3 Weaknesses and competitive threats
- 15.1.1 AARTI INDUSTRIES LTD.
- 15.2 OTHER PLAYERS
- 15.2.1 HARSHIL INDUSTRIES
- 15.2.2 AWISHKAR CHEMICALS INDUSTRIES
- 15.2.3 MORITA CHEMICAL INDUSTRIES CO., LTD.
- 15.2.4 SOLSTICE ADVANCED MATERIALS US, INC.
- 15.2.5 NACALAI TESQUE, INC.
- 15.2.6 FUJIFILM WAKO PURE CHEMICAL CORPORATION
- 15.2.7 JAYFLUORIDE PRIVATE LIMITED
- 15.2.8 MARUTI INDUSTRIES
- 15.2.9 ZHISHI INDUSTRIAL (SHANGHAI) CO., LTD.
- 15.2.10 EREZTECH LLC
- 15.2.11 KISHIDA CHEMICAL CO., LTD.
- 15.2.12 HUNAN HEAVEN MATERIALS DEVELOPMENT CO., LTD.
- 15.2.13 STELLA CHEMIFA CORPORATION
- 15.2.14 LICHE OPTO GROUP CO., LTD.
- 15.2.15 QUZHOU YUANFANG CHEMICAL FACTORY
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.2 PRIMARY DATA
- 16.1.2.1 Key primary interview participants
- 16.2 MARKET SIZE ESTIMATION
- 16.2.1 BOTTOM-UP APPROACH
- 16.2.2 TOP-DOWN APPROACH
- 16.3 BASE NUMBER CALCULATION
- 16.4 MARKET FORECAST APPROACH
- 16.4.1 SUPPLY SIDE
- 16.4.2 DEMAND SIDE
- 16.5 DATA TRIANGULATION
- 16.6 RESEARCH LIMITATIONS AND RISK ASSESSMENT
17 APPENDIX
- 17.1 DISCUSSION GUIDE
- 17.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.3 CUSTOMIZATION OPTIONS
- 17.4 RELATED REPORTS
- 17.5 AUTHOR DETAILS