
|
시장보고서
상품코드
2130450
막 시장 : 소재(폴리머·세라믹), 기술(역삼투·한외여과·정밀 여과·나노 여과), 용도(물&폐수 처리·산업 프로세스), 지역별 예측(-2031년)Membranes Market by Material (Polymeric, Ceramic), Technology (Reverse Osmosis, Ultrafiltration, Microfiltration, Nanofiltration), Application (Water & Wastewater Treatment, Industrial Processing), and Region - Global Forecast to 2031 |
||||||

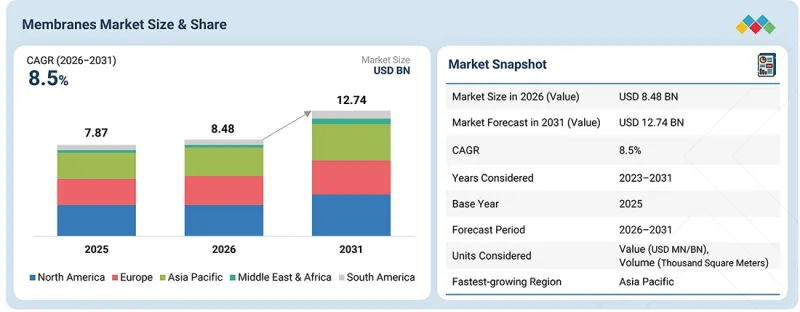
막 시장 규모는 2026년 84억 8,000만 달러에서 CAGR 8.5%로 확대되어 2031년에는 127억 4,000만 달러에 이를 것으로 예상되고 있습니다.
폐수 처리 수요 증가가 막의 활용을 뒷받침하고 있습니다. 이는 막이 오염 물질을 효과적으로 제거하여 엄격한 배출 기준 달성을 지원할 뿐만 아니라, 처리수의 방류나 재이용에 따른 위험을 줄여주기 때문입니다. 급속한 산업화와 도시화로 인해 폐수 발생량이 증가하고 오염 수준이 높아짐에 따라, 지속 가능한 물 관리와 자원 회수를 위해 막 여과 등 첨단 처리 기술의 도입 및 확대가 진행되고 있습니다. 또한, 재활용 및 재사용을 통해 물 부족 문제 해결에 주력하는 움직임이 전 세계 지자체 및 산업 부문의 막 수요를 끌어올릴 것으로 예측됩니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2023-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 단위 | 금액(달러)·수량(평방미터) |
| 부문 | 소재, 기술, 용도 |
| 대상 지역 | 아시아태평양, 북미, 유럽, 중동 및 아프리카, 남미 |
“기술별로는 정밀 여과 부문이 예측 기간 동안 금액 기준 2위의 점유율을 차지할 것으로 전망된다”
정밀 여과는 물 및 폐수 처리 시스템, 의약품 및 의료 제품, 식품 및 음료 등 폭넓은 분야에서 널리 이용되고 있기 때문에 금액 기준으로 두 번째로 큰 점유율을 차지하고 있습니다. 정밀 여과의 큰 특징은 비교적 적은 에너지 소비로 부유 물질, 세균, 큰 폴리머를 효율적이고 효과적으로 제거할 수 있다는 점입니다. 에너지 소비가 적기 때문에 정밀 여과는 다른 많은 처리 방법에 비해 상대적으로 비용이 저렴합니다. 수질 관련 규제 기준의 강화와 업계 전반에 걸친 정화된 배수 수요 증가도 전 세계적으로 정밀 여과 채택이 확대되고 있는 주요 요인 중 하나입니다.
“소재별로는 폴리머 막이 예측 기간 동안 금액 기준으로 세 번째로 높은 성장률을 보일 전망입니다.”
폴리머 막은 높은 수준의 맞춤화 가능성과 유연한 생산 옵션을 제공하며, 비용 대비 효율이 가장 높고 내화학성도 뛰어나 성장률이 세 번째로 높은 부문으로 자리매김하고 있습니다. 이러한 막은 뛰어난 선택성과 내구성을 제공하는 다양한 폴리머를 사용하여 작동하기 때문에 수처리, 제약, 식품 개발 분야에서 널리 활용되고 있습니다. 고분자 화학의 발전으로 인해 오염 저항성 향상, 투과성 향상, 엄격한 환경 규제에 대한 대응 능력 향상이 실현되었습니다. 또한, 지속 가능한 액체 여과 솔루션에 대한 관심과 수요도 증가하고 있습니다. 이러한 동향으로 인해 예측 기간 동안 고분자 막 필터의 활용 확대로 이어질 기회가 생길 것으로 예측됩니다.
“지역별로는 아시아태평양이 금액 기준으로 가장 큰 점유율을 차지할 전망입니다.”
아시아태평양은 중국, 인도, 동남아시아의 급속한 산업화, 도시화, 정수 및 폐수 처리 솔루션에 대한 수요 증가로 인해 시장 점유율을 주도하고 있으며, 가장 빠르게 성장하고 있는 지역입니다. 또한, 정부의 강력한 정책 추진, 인프라에 대한 설비 투자, 지속적인 기술 발전으로 인해 지역 시장의 성장이 가속화되고 있으며, 이를 통해 막 기술의 도입 및 혁신 기회가 창출되고 있습니다.
본 보고서에서는 세계의 막 시장을 조사했으며, 시장 개요, 시장 성장에 영향을 미치는 다양한 요인에 대한 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추이 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 프로파일 등을 종합적으로 다루고 있습니다.
자주 묻는 질문
목차
제1장 서론
제2장 주요 요약
제3장 프리미엄 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI의 영향, 특허, 혁신, 향후 용도
제7장 규제 상황과 지속가능성 이니셔티브
제8장 고객 현황과 구매 행동
제9장 막 시장 : 소재별
제10장 막 시장 : 기술별
제11장 막 시장 : 용도별
제12장 막 시장 : 지역별
제13장 경쟁 구도
제14장 기업 개요
제15장 조사 방법
제16장 부록
KTH 26.09.28The membranes market is expected to reach USD 12.74 billion by 2031, up from USD 8.48 billion in 2026, with a CAGR of 8.5%. The rising demand for wastewater treatment is fueling membrane use because they effectively remove contaminants, helping meet strict disposal standards and reducing risks associated with discharges or reusing treated water. Rapid industrialization and urbanization have led to increased wastewater production and higher pollution levels, prompting the adoption or continuation of advanced treatment technologies like membrane filtration for sustainable water management and resource recovery. Additionally, the focus on reducing water shortages through recycling and reuse is expected to boost demand for membranes in both municipal and industrial sectors worldwide.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2023-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million); Volume (Thousand Square Meters) |
| Segments | Material, Technology, and Application |
| Regions covered | Asia Pacific, North America, Europe, the Middle East & Africa, and South America |
"Based on technology, microfiltration segment to account for second-largest share of membranes market during forecast period, in terms of value"
In terms of value, microfiltration holds the second-largest share of the membranes market because of its extensive use in water and wastewater treatment systems, pharmaceuticals and medical products, food and beverage, and more. Microfiltration has a unique feature that benefits its applications: its ability to effectively and efficiently remove suspended solids, bacteria, and large macromolecules with less energy consumption. Its low energy requirement makes microfiltration relatively inexpensive compared to many other treatment methods. The rising regulatory standards for water quality and the growing industry-wide demand for purified effluents are among the key reasons driving the increased adoption of microfiltration applications worldwide.
"Based on material, polymeric segment to be third fastest-growing segment in membranes market during forecast period, in terms of value"
Polymeric membranes are the third fastest-growing segment in the membranes market because they offer significant customization and flexible production options, are the most cost-effective, and have high chemical resistance. These membranes operate with various polymers that provide good selectivity and durability, making them common in water treatment, pharmaceuticals, and food development applications. Advances in polymer chemistry have led to improved fouling resistance, increased permeability, and a better ability to meet strict environmental regulations. There is also a growing focus and demand for sustainable liquid filtration solutions. It is expected that these trends will create opportunities for increased use of polymeric membrane filters throughout the forecast period.
"Based on region, Asia Pacific to account for largest share of membranes market, in terms of value"
Asia Pacific dominates the membranes market share and is the fastest-growing region due to rapid industrialization, urbanization, and the increased demand for clean water and wastewater treatment solutions in China, India, and Southeast Asia. Additionally, with strong government initiatives, capital investments in infrastructure, and ongoing advancements in technology, Asia Pacific has amplified market growth, thereby providing an opportunity to adopt and innovate membrane technologies.
In the process of determining and verifying the market size for several segments and subsegments identified through secondary research, extensive primary interviews were conducted. A breakdown of the profiles of the primary interviewees is as follows:
- By Company Type: Tier 1 - 40%, Tier 2 - 30%, and Tier 3 - 30%
- By Designation: Directors- 30%, Managers - 20%, and Others - 50%
- By Region: North America - 20%, Europe - 10%, Asia Pacific - 40%, Middle East & Africa - 20%, and South America - 10%
Key players in this market are Dupont (US), Toray Industries (Japan), Hydranautics (Nitto Denko Group Company) (US), Kovalus Separation Solutions (US), Pall Corporation (US), Veolia (France), Pentair (US), Asahi Kasei Corporation (Japan), LG Chem (South Korea), and Mann+Hummel (Germany).
Research Coverage
This report segments the membranes market by material, technology, application, and region, and offers estimates of the market's overall value across various regions. A detailed analysis of key industry players has been performed to provide insights into their business overviews, products and services, main strategies, new product launches, expansions, and mergers and acquisitions related to the membranes market.
Key Benefits of Buying this Report
This research report focuses on various levels of analysis, including industry analysis (industry trends), market ranking analysis of top players, and company profiles. Together, these provide an overall view of the competitive landscape, emerging and high-growth segments of the membranes market, high-growth regions, and the market's drivers, restraints, opportunities, and challenges.
The report provides insights into the following pointers:
- Analysis of key drivers (Increasing awareness about water & wastewater treatment, Stringent wastewater regulations, Shift from chemical to physical treatment of water, Increasing demand from end-use industries), restraints (Fouling and scaling reducing membrane performance, High capital costs, Limited compatibility and high energy consumption), opportunities (Rising demand for water treatment in developing countries, Increasing water scarcity, Circular economy initiatives) and challenges (Discharge of brine as waste from RO membranes, Issue related to lifespan and efficiency of membranes, High initial costs).
- Market Penetration: Comprehensive information on the membranes market share is offered regarding the top players in the global membranes market.
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and new product launches in the membranes market.
- Market Development: Comprehensive information about lucrative emerging markets - the report analyzes the membranes market across regions.
- Market Diversification: Exhaustive information about new products, untapped regions, and recent developments in the global membranes market.
- Competitive Assessment: In-depth assessment of market shares, strategies, products, and manufacturing capabilities of leading players in the membranes market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.3.5 UNITS CONSIDERED
- 1.4 STAKEHOLDERS
- 1.5 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN MEMBRANES MARKET
- 3.2 ASIA PACIFIC: MEMBRANES MARKET, BY MATERIAL AND COUNTRY
- 3.3 MEMBRANES MARKET, BY TECHNOLOGY
- 3.4 MEMBRANES MARKET, BY APPLICATION
- 3.5 MEMBRANES MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing awareness about water & wastewater treatment
- 4.2.1.2 Stringent wastewater regulations
- 4.2.1.3 Shift from chemical to membrane treatment of water
- 4.2.1.4 Increasing demand for membranes from end-use industries
- 4.2.2 RESTRAINTS
- 4.2.2.1 Fouling and scaling in membranes
- 4.2.2.2 High capital costs of raw materials
- 4.2.2.3 Limited compatibility and high energy consumption
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Rising demand for water treatment in emerging economies
- 4.2.3.2 Pressing need for freshwater supply in industries
- 4.2.3.3 Circular economy initiatives
- 4.2.4 CHALLENGES
- 4.2.4.1 Issues related to lifespan and efficiency of membranes
- 4.2.4.2 Discharge of brine as waste from RO membranes
- 4.2.4.3 High initial cost of equipment
- 4.2.5 UNMET NEEDS IN MEMBRANES MARKET
- 4.2.6 WHITE SPACE OPPORTUNITIES
- 4.2.7 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.2.1 DRIVERS
- 4.3 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.3.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 VALUE CHAIN ANALYSIS
- 5.3 ECOSYSTEM
- 5.4 PRICING ANALYSIS
- 5.4.1 AVERAGE SELLING PRICE (ASP) TREND, BY REGION
- 5.4.2 AVERAGE SELLING PRICE TREND OF MEMBRANES, BY APPLICATION (2023-2025)
- 5.5 MACROECONOMIC INDICATORS
- 5.5.1 GLOBAL GDP TRENDS
- 5.5.2 HEALTHCARE INDUSTRY TRENDS
- 5.6 IMPACT OF 2025 US TARIFFS ON MEMBRANES MARKET
- 5.6.1 INTRODUCTION
- 5.6.2 KEY TARIFF RATES
- 5.6.3 PRICE IMPACT ANALYSIS
- 5.6.4 IMPACT ON COUNTRIES/REGIONS
- 5.6.4.1 US
- 5.6.4.2 Europe
- 5.6.4.3 Asia Pacific
- 5.6.5 IMPACT ON END-USE INDUSTRIES
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT SCENARIO (HS CODE 842129)
- 5.7.2 EXPORT SCENARIO (HS CODE 842129)
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 DUPONT FILMTEC MEMBRANES ENABLE INDUSTRIAL WATER REUSE AT BENXI STEEL GROUP
- 5.10.2 TORAY INDUSTRIES, INC. PROVIDES RO MEMBRANES FOR LARGE-SCALE SEAWATER DESALINATION IN UAE
- 5.10.3 HYDRANAUTICS PROVIDES SWC6-LD MEMBRANES FOR TOCOPILLA DESALINATION PLANT IN CHILE
- 5.10.4 KOVALUS SEPARATION SOLUTIONS DEPLOYS PURON MBR TECHNOLOGY AT RWE EEMSHAVEN POWER STATION
- 5.11 KEY CONFERENCES & EVENTS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGY
- 6.1.1.1 Block copolymer membranes
- 6.1.1.2 Flux enhancement technology
- 6.1.2 COMPLEMENTARY TECHNOLOGY
- 6.1.2.1 Membrane crystallization (Combining crystallization & diffusion)
- 6.1.2.2 Membrane distillation
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 Membrane contactors
- 6.1.3.2 Pervaporation for hydrocarbon separation
- 6.1.3.3 Forward osmosis, direct contact membrane distillation, and integrated FO-DCMD systems
- 6.1.1 KEY TECHNOLOGY
- 6.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.2.1 SHORT-TERM (2025-2027) | MATERIAL INNOVATION & PERFORMANCE OPTIMIZATION
- 6.2.2 MID-TERM (2027-2030) | SMART MEMBRANES & DIGITAL PROCESS INTEGRATION
- 6.2.3 LONG TERM (2030-2035+) | SUSTAINABLE HIGH-PERFORMANCE MEMBRANES & AUTONOMOUS OPERATIONS
- 6.3 PATENT ANALYSIS
- 6.3.1 LEGAL STATUS OF PATENTS
- 6.3.2 JURISDICTION ANALYSIS
- 6.4 FUTURE APPLICATIONS
- 6.4.1 ADVANCED WATER REUSE, DESALINATION, AND RESOURCE RECOVERY
- 6.4.2 INDUSTRIAL PROCESS SEPARATION & RESOURCE RECOVERY
- 6.4.3 ADVANCED MEMBRANE TECHNOLOGIES & ANTI-FOULING SOLUTIONS
- 6.4.4 MEMBRANE-BASED GAS SEPARATION, HYDROGEN & CARBON MANAGEMENT
- 6.5 IMPACT OF AI/GEN AI ON MEMBRANES MARKET
- 6.5.1 TOP USE CASES AND MARKET POTENTIAL OF MEMBRANES
- 6.5.2 BEST PRACTICES IN MEMBRANE PROCESSING
- 6.5.3 CASE STUDIES OF AI IMPLEMENTATION IN MEMBRANES MARKET
- 6.5.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.5 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN MEMBRANES MARKET
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 IMPACT OF REGULATORY POLICIES AND SUSTAINABILITY INITIATIVES
- 7.3 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 INTRODUCTION
- 8.2 DECISION-MAKING PROCESS
- 8.3 KEY STAKEHOLDERS AND BUYING CRITERIA
- 8.3.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.3.2 BUYING CRITERIA
- 8.4 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.5 UNMET NEEDS IN VARIOUS END-USE INDUSTRIES
- 8.6 MARKET PROFITABILITY
- 8.6.1 REVENUE POTENTIAL
- 8.6.2 COST DYNAMICS
- 8.6.3 MARGIN OPPORTUNITIES IN KEY END-USE INDUSTRIES
9 MEMBRANES MARKET, BY MATERIAL
- 9.1 INTRODUCTION
- 9.2 POLYMERIC
- 9.2.1 POLYAMIDE
- 9.2.1.1 Primarily used in NF and RO membranes
- 9.2.2 POLYSULFONE AND POLYETHERSULFONE
- 9.2.2.1 Offer high thermal and chemical stability
- 9.2.3 FLUOROPOLYMERS
- 9.2.3.1 Possess high mechanical strength and chemical resistance
- 9.2.4 OTHER POLYMERIC MEMBRANES
- 9.2.1 POLYAMIDE
- 9.3 CERAMIC
- 9.3.1 ALUMINA
- 9.3.1.1 Improves production efficiency of membranes
- 9.3.2 TITANIA
- 9.3.2.1 Primarily used in MF and NF membranes
- 9.3.3 ZIRCONIA
- 9.3.3.1 High strength and fracture toughness
- 9.3.4 OTHER CERAMIC MEMBRANES
- 9.3.1 ALUMINA
- 9.4 OTHER MATERIALS
10 MEMBRANES MARKET, BY TECHNOLOGY
- 10.1 INTRODUCTION
- 10.2 REVERSE OSMOSIS
- 10.2.1 WIDELY USED IN DESALINATION
- 10.3 ULTRAFILTRATION
- 10.3.1 HIGHER FLUX RATE THAN REVERSE OSMOSIS
- 10.4 MICROFILTRATION
- 10.4.1 USED AS PRETREATMENT TO REVERSE OSMOSIS AND NANOFILTRATION
- 10.5 NANOFILTRATION
- 10.5.1 WORKS AT REDUCED OPERATING PRESSURES WITH HIGHER FLOW RATES THAN REVERSE OSMOSIS
- 10.6 OTHER TECHNOLOGIES
11 MEMBRANES MARKET, BY APPLICATION
- 11.1 INTRODUCTION
- 11.2 WATER & WASTEWATER TREATMENT
- 11.2.1 DESALINATION
- 11.2.1.1 Used to separate dissolved salts from water
- 11.2.2 UTILITY WATER TREATMENT
- 11.2.2.1 Produces high-purity or potable water from contaminated sources
- 11.2.3 WASTEWATER REUSE
- 11.2.3.1 Efficient in eliminating contaminants from process streams
- 11.2.1 DESALINATION
- 11.3 INDUSTRIAL PROCESSING
- 11.3.1 FOOD & BEVERAGE
- 11.3.1.1 Removal of pathogenic substances from liquid streams
- 11.3.2 CHEMICAL & PETROCHEMICAL
- 11.3.2.1 Reduced operational cost
- 11.3.3 PHARMACEUTICAL & MEDICAL
- 11.3.3.1 Superior filtration and temperature resistance
- 11.3.4 TEXTILE
- 11.3.4.1 Desalting & purification of dyes
- 11.3.5 POWER
- 11.3.5.1 Advanced membrane technology to improve water quality
- 11.3.6 PULP & PAPER
- 11.3.6.1 Wastewater treatment for pulp preparation and bleaching
- 11.3.7 OTHER APPLICATIONS
- 11.3.1 FOOD & BEVERAGE
12 MEMBRANES MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 ASIA PACIFIC
- 12.2.1 CHINA
- 12.2.1.1 Shift towards advanced water treatment and water reuse to drive market
- 12.2.2 JAPAN
- 12.2.2.1 Development of advanced technologies and boom in industrial sector to boost market
- 12.2.3 INDIA
- 12.2.3.1 Expansion of wastewater treatment infrastructure and water reuse to drive membrane demand
- 12.2.4 SOUTH KOREA
- 12.2.4.1 Expansion of industrial water reuse and advanced treatment to drive membrane demand
- 12.2.5 AUSTRALIA
- 12.2.5.1 Expansion of desalination and water reuse to drive membrane demand
- 12.2.6 REST OF ASIA PACIFIC
- 12.2.1 CHINA
- 12.3 NORTH AMERICA
- 12.3.1 US
- 12.3.1.1 Expansion of industrial water reuse and advanced water treatment to drive membrane demand
- 12.3.2 CANADA
- 12.3.2.1 Expansion of industrial water treatment and water reuse to drive membrane demand
- 12.3.3 MEXICO
- 12.3.3.1 Growth of manufacturing sector to boost market
- 12.3.1 US
- 12.4 EUROPE
- 12.4.1 SPAIN
- 12.4.1.1 Expansion of desalination and water reuse to drive membrane demand
- 12.4.2 GERMANY
- 12.4.2.1 Stricter wastewater standards and advanced treatment upgrades to drive membrane demand
- 12.4.3 FRANCE
- 12.4.3.1 Increasing water reuse and adoption of advanced membrane technologies to drive market
- 12.4.4 UK
- 12.4.4.1 Rising concerns over water scarcity prompting increased adoption of desalination and advanced membrane technologies
- 12.4.5 ITALY
- 12.4.5.1 Water scarcity and industrial water reuse to drive membrane demand
- 12.4.6 REST OF EUROPE
- 12.4.1 SPAIN
- 12.5 MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.5.1.1 Saudi Arabia
- 12.5.1.1.1 Expansion of reverse osmosis desalination and water reuse to drive membrane demand
- 12.5.1.2 UAE
- 12.5.1.2.1 Extensive use of membranes in brackish water treatment to drive market
- 12.5.1.3 Kuwait
- 12.5.1.3.1 Strong capacity for brackish water and seawater desalination to boost market
- 12.5.1.4 Rest of GCC
- 12.5.1.1 Saudi Arabia
- 12.5.2 SOUTH AFRICA
- 12.5.2.1 Addressing water scarcity through advanced membrane technologies in South Africa
- 12.5.3 REST OF MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.6 SOUTH AMERICA
- 12.6.1 BRAZIL
- 12.6.1.1 Rising need for safe drinking water to drive demand for membranes
- 12.6.2 ARGENTINA
- 12.6.2.1 Emphasis on wastewater treatment activities and foreign investments to boost market
- 12.6.3 REST OF SOUTH AMERICA
- 12.6.1 BRAZIL
13 COMPETITIVE LANDSCAPE
- 13.1 OVERVIEW
- 13.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 13.3 REVENUE ANALYSIS, 2022-2025
- 13.4 MARKET SHARE ANALYSIS, 2025
- 13.5 COMPANY VALUATION AND FINANCIAL METRICS
- 13.5.1 COMPANY VALUATION
- 13.6 PRODUCT COMPARISON ANALYSIS
- 13.6.1 DUPONT (FILMTEC)
- 13.6.2 HYDRANAUTICS (A NITTO GROUP COMPANY) (PRO-SERIES)
- 13.6.3 KOVALUS SEPARATION SOLUTIONS (PURON)
- 13.6.4 VEOLIA (ZEEWEED ULTRAFILTRATION HOLLOW-FIBER MEMBRANES)
- 13.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.7.1 STARS
- 13.7.2 EMERGING LEADERS
- 13.7.3 PERVASIVE PLAYERS
- 13.7.4 PARTICIPANTS
- 13.7.5 COMPANY FOOTPRINT
- 13.7.5.1 Material footprint
- 13.7.5.2 Technology footprint
- 13.7.5.3 Application footprint
- 13.7.5.4 Region footprint
- 13.7.5.5 Company overall footprint
- 13.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 13.8.1 PROGRESSIVE COMPANIES
- 13.8.2 RESPONSIVE COMPANIES
- 13.8.3 DYNAMIC COMPANIES
- 13.8.4 STARTING BLOCKS
- 13.8.5 COMPETITIVE BENCHMARKING
- 13.9 COMPETITIVE SCENARIO AND TRENDS
- 13.9.1 PRODUCT LAUNCHES
- 13.9.2 DEALS
- 13.9.3 EXPANSIONS
- 13.9.4 OTHER DEVELOPMENTS
14 COMPANY PROFILES
- 14.1 KEY PLAYERS
- 14.1.1 DUPONT
- 14.1.1.1 Business overview
- 14.1.1.2 Products/Solutions/Services offered
- 14.1.1.3 Recent developments
- 14.1.1.3.1 Deals
- 14.1.1.4 MnM view
- 14.1.1.4.1 Key strengths
- 14.1.1.4.2 Strategic choices
- 14.1.1.4.3 Weaknesses and competitive threats
- 14.1.2 TORAY INDUSTRIES, INC.
- 14.1.2.1 Business overview
- 14.1.2.2 Products/Solutions/Services offered
- 14.1.2.3 Recent developments
- 14.1.2.3.1 Product launches
- 14.1.2.3.2 Deals
- 14.1.2.4 MnM view
- 14.1.2.4.1 Key strengths
- 14.1.2.4.2 Strategic choices
- 14.1.2.4.3 Weaknesses and competitive threats
- 14.1.3 HYDRANAUTICS (A NITTO DENKO GROUP COMPANY)
- 14.1.3.1 Business overview
- 14.1.3.2 Products/Solutions/Services offered
- 14.1.3.3 Recent developments
- 14.1.3.3.1 Product launches
- 14.1.3.3.2 Deals
- 14.1.3.4 MnM view
- 14.1.3.4.1 Key strengths
- 14.1.3.4.2 Strategic choices
- 14.1.3.4.3 Weaknesses and competitive threats
- 14.1.4 KOVALUS SEPARATION SOLUTIONS
- 14.1.4.1 Business overview
- 14.1.4.2 Products/Solutions/Services offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Product launches
- 14.1.4.3.2 Deals
- 14.1.4.3.3 Deals
- 14.1.4.3.4 Expansions
- 14.1.4.4 MnM view
- 14.1.4.4.1 Key strengths
- 14.1.4.4.2 Strategic choices
- 14.1.4.4.3 Weaknesses and competitive threats
- 14.1.5 PALL CORPORATION
- 14.1.5.1 Business overview
- 14.1.5.2 Products/Solutions/Services offered
- 14.1.5.3 Recent developments
- 14.1.5.3.1 Deals
- 14.1.5.4 MnM view
- 14.1.5.4.1 Key strengths
- 14.1.5.4.2 Strategic choices
- 14.1.5.4.3 Weaknesses and competitive threats
- 14.1.6 VEOLIA
- 14.1.6.1 Business overview
- 14.1.6.2 Products/Solutions/Services offered
- 14.1.6.3 Recent developments
- 14.1.6.3.1 Deals
- 14.1.6.4 MnM view
- 14.1.6.4.1 Key strengths
- 14.1.6.4.2 Strategic choices
- 14.1.6.4.3 Weaknesses and competitive threats
- 14.1.7 PENTAIR
- 14.1.7.1 Business overview
- 14.1.7.2 Products/Solutions/Services offered
- 14.1.7.3 Recent developments
- 14.1.7.3.1 Product launches
- 14.1.7.3.2 Deals
- 14.1.7.4 MnM view
- 14.1.7.4.1 Key strengths
- 14.1.7.4.2 Strategic choices
- 14.1.7.4.3 Weaknesses and competitive threats
- 14.1.8 ASAHI KASEI CORPORATION
- 14.1.8.1 Business overview
- 14.1.8.2 Products/Solutions/Services offered
- 14.1.8.3 Recent developments
- 14.1.8.3.1 Product launches
- 14.1.8.3.2 Expansions
- 14.1.8.4 MnM view
- 14.1.8.4.1 Key strengths
- 14.1.8.4.2 Strategic choices
- 14.1.8.4.3 Weaknesses and competitive threats
- 14.1.9 LG CHEM
- 14.1.9.1 Business overview
- 14.1.9.2 Products/Solutions/Services offered
- 14.1.9.3 Recent developments
- 14.1.9.3.1 Product launches
- 14.1.9.3.2 Deals
- 14.1.9.3.3 Other developments
- 14.1.9.4 MnM view
- 14.1.9.4.1 Key strengths
- 14.1.9.4.2 Strategic choices
- 14.1.9.4.3 Weaknesses and competitive threats
- 14.1.10 MANN+HUMMEL
- 14.1.10.1 Business overview
- 14.1.10.2 Products/Solutions/Services offered
- 14.1.10.3 MnM view
- 14.1.10.3.1 Key strengths
- 14.1.10.3.2 Strategic choices
- 14.1.10.3.3 Weaknesses and competitive threats
- 14.1.11 SOLVENTUM
- 14.1.11.1 Business overview
- 14.1.11.2 Products/Solutions/Services offered
- 14.1.11.2.1 Other developments
- 14.1.11.3 MnM view
- 14.1.11.3.1 Key strengths
- 14.1.11.3.2 Strategic choices made
- 14.1.11.3.3 Weaknesses and competitive threats
- 14.1.12 BEIJING ORIGINWATER TECHNOLOGY CO., LTD.
- 14.1.12.1 Business overview
- 14.1.12.2 Products/Solutions/Services offered
- 14.1.12.3 MnM view
- 14.1.12.3.1 Key strengths
- 14.1.12.3.2 Strategic choices made
- 14.1.12.3.3 Weaknesses and competitive threats
- 14.1.1 DUPONT
- 14.2 OTHER PLAYERS
- 14.2.1 ALSYS
- 14.2.2 APPLIED MEMBRANES, INC.
- 14.2.3 AQUAPORIN
- 14.2.4 AXEON WATER TECHNOLOGIES
- 14.2.5 GEA GROUP AKTIENGESELLSCHAFT
- 14.2.6 LANXESS
- 14.2.7 LENNTECH B.V.
- 14.2.8 MEMBRANE SOLUTIONS (NANTONG)
- 14.2.9 MEMBRANIUM
- 14.2.10 MERCK KGAA
- 14.2.11 PARKER-HANNIFIN CORP
- 14.2.12 PERMIONICS
- 14.2.13 SYNDER FILTRATION, INC.
- 14.2.14 SCINOR WATER AMERICA, LLC
- 14.2.15 TOYOBO CO., LTD.
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.1.1 Key data from secondary sources
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Key data from primary sources
- 15.1.2.2 Key industry insights
- 15.1.2.3 Breakdown of primary interviews
- 15.1.1 SECONDARY DATA
- 15.2 MARKET SIZE ESTIMATION
- 15.2.1 BOTTOM-UP APPROACH
- 15.2.2 TOP-DOWN APPROACH
- 15.3 BASE NUMBER CALCULATION
- 15.3.1 DEMAND-SIDE APPROACH
- 15.3.2 SUPPLY-SIDE APPROACH
- 15.4 MARKET FORECAST APPROACH
- 15.4.1 SUPPLY SIDE
- 15.4.2 DEMAND SIDE
- 15.5 DATA TRIANGULATION
- 15.6 FACTOR ANALYSIS
- 15.7 RESEARCH ASSUMPTIONS
- 15.8 LIMITATIONS & RISKS
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS


