
|
시장보고서
상품코드
2132779
모바일 헬스(mHealth) 솔루션 시장 예측(-2031년) : 오퍼링별, 사용 사례별, 최종사용자별, 지역별mHealth Solutions Market by Offering [Apps (Chronic Care, Mental Health, Women´s Health, Medication Management, Fitness, CDS), Devices (Sleep, Drug Delivery)], Use Case (Preventive, Monitoring), End User (Providers, Patients) - Global Forecast to 2031 |
||||||

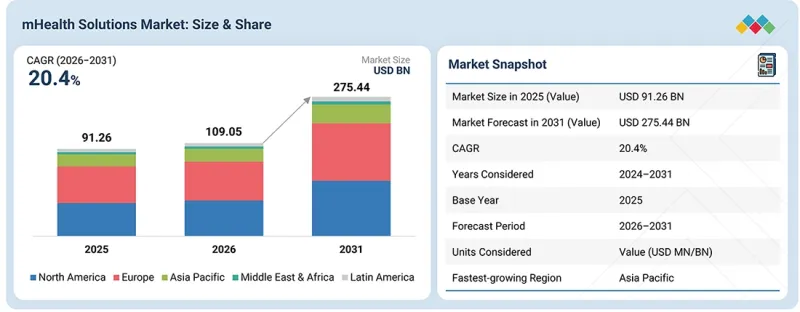
세계의 모바일 헬스 솔루션 시장 규모는 2026년 1,090억 5,000만 달러에서 예측 기간 중 CAGR 20.4%로 확대하며, 2031년에는 2,754억 4,000만 달러에 달할 것으로 예측됩니다.
정부의 정책 및 규제적 노력에 힘입어 모바일 의료 애플리케이션, 커넥티드 의료기기, 원격 환자 모니터링, AI 기반 헬스케어 소프트웨어 및 디지털 헬스 인프라에 대한 체계가 마련되면서 모바일 헬스 솔루션의 도입이 더욱 가속화되고 있습니다. 미국에서는 FDA가 모바일 의료 애플리케이션 및 의료기기 소프트웨어에 대해 위험 기반 규제 체계를 적용하고 있을 뿐만 아니라, 2026년에 발표된 임상 의사결정 지원 소프트웨어 및 저위험 웰니스 기술에 관한 지침을 통해 디지털 헬스 개발자들에게 보다 명확한 지침을 제시하고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2031년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 오퍼링별, 사용 사례별, 최종사용자별, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카 |
또한 FDA는 2026년에 ‘TEMPO 디지털 헬스 기기 시범 프로그램’을 시작하여, 환자 안전 요건을 유지하면서 특정 디지털 헬스 기기에 대한 접근을 촉진하고 있습니다. 호주 디지털 헬스청은 소비자와 의료 종사자가 모바일 헬스 애플리케이션의 신뢰성, 안전성, 사용 편의성 및 임상적 가치를 평가할 수 있도록 지원하기 위해 모바일 헬스 앱에 관한 전국적인 평가 프레임워크를 수립했습니다. 이러한 노력을 통해 모바일 헬스 애플리케이션에 대한 규제의 명확성과 신뢰성이 높아졌으며, 의료 시스템 전반에 걸친 해당 애플리케이션의 개발, 평가 및 도입이 지원되고 있습니다.
이러한 노력 덕분에 모바일 헬스 서비스 분야는 예측 기간 중 상당한 성장률을 보이고 있습니다.
의료 시스템에서 지속적이고 원격적인 재택 간호를 실현하는 기술을 활용한 모델이 점점 더 많이 채택됨에 따라 모바일 헬스 서비스는 인상적인 성장을 달성하고 있습니다. 이러한 성장은 만성질환 유병률의 증가, 환자에 대한 지속적인 모니터링의 필요성, 재택 의료에 대한 수요 증가, 그리고 의료 서비스 제공자에게 건강 정보를 전송하는 커넥티드 의료기기의 이용 확대에 의해 주도되고 있습니다. 예를 들어 필립스의 ‘Care Orchestrator’를 활용하면 의료 제공자는 수면 무호흡증이나 호흡기 질환이 있는 환자를 원격으로 모니터링 및 관리하고, 복약 순응도 및 임상 보고서를 수신하며, 개입이 필요한 환자를 우선적에 대응할 수 있습니다.
최종사용자별로는 2025년 의료 제공자 부문이 모바일 헬스 솔루션 시장에서 큰 점유율을 차지했습니다.
최종사용자별로 보면 모바일 헬스 솔루션 시장은 환자·소비자, 의료 제공자, 의료 보험사, 기타 최종사용자로 구분됩니다. 이러한 구분은 환자 모니터링, 임상적 의사결정, 치료 조정 및 의료 서비스 제공 개선을 목적으로 한 디지털 기술의 채택 확대에 의해 추진되고 있습니다. 병원, 진료소 및 기타 의료 제공자들은 환자 데이터에 대한 지속적인 접근을 가능하게 하고 시기적절한 개입을 지원하기 위해 모바일 헬스 애플리케이션, 연결형 의료기기 및 원격 모니터링 서비스를 임상 워크플로우에 점점 더 많이 통합하고 있습니다. 만성질환 유병률의 증가와 가치 중심 치료 및 재택 치료로의 전환은 의료 제공자들이 모바일 헬스 솔루션을 도입하는 움직임을 더욱 가속화하고 있습니다. 예를 들어 원격 환자 모니터링을 통해 의료 서비스 제공자는 혈압계, 혈당 측정기, 펄스 옥시미터 등 연결된 의료기기에서 환자가 생성한 건강 데이터를 수신하고, 이 정보를 활용하여 원격으로 환자를 관리할 수 있게 됩니다.
아시아태평양은 예측 기간 중 가장 빠른 성장세를 기록할 것으로 예상됩니다.
아시아태평양은 의료의 급속한 디지털화, 모바일 연결의 확대, 만성질환 부담의 증가, 그리고 원격 진료 및 재택 진료에 대한 수요 증가에 힘입어 모바일 헬스 솔루션 시장에서 가장 빠르게 성장하는 지역이 될 것으로 예상됩니다. 이 지역 전반에 걸친 정부 주도의 노력으로 디지털 헬스 생태계는 더욱 강화되고 있습니다. 중국에서는 정부가 ‘인터넷+의료’ 모델의 확대를 지속하고 있으며, 인터넷 병원과 온라인 의료 서비스를 통해 원격 진료 및 디지털 기반 의료 서비스에 대한 접근성이 확대되고 있습니다. 2025년까지 중국의 인터넷 의료 규제 플랫폼은 성(省) 수준에서 커버리지를 달성했으며, 인터넷 병원의 수도 크게 증가했습니다. 또한 정부는 모바일 의료 앱, 원격 진료 및 커넥티드 헬스케어 서비스의 촉진에도 힘쓰고 있으며, 그 일환으로 ‘광대역 네트워크+건강한 농촌 지역’ 시범 사업을 시행했습니다. 이 사업에는 117개의 프로젝트가 포함되어 있으며, 그중 37건이 원격의료 서비스에 중점을 둔 것이었습니다. 이러한 노력은 해당 지역의 디지털 헬스 인프라를 강화하는 동시에, 모바일 헬스 앱, 원격의료, 원격 환자 모니터링 및 커넥티드 의료기기 분야에서 기회를 창출하고 있습니다.
주요 기업
모바일 헬스 솔루션 시장에서 사업을 운영하는 주요 기업으로는 Koninklijke Philips N.V.(네덜란드), Medtronic(아일랜드), Abbott(미국), ResMed(미국),Dexcom, Inc.(미국), GE HealthCare(미국), athenahealth(미국), Optum(미국) 등이 있습니다. 이들 기업은 모바일 헬스 솔루션 시장에서의 입지를 강화하기 위해 신제품 출시, 제품 업데이트, 사업 확장, 파트너십, 제휴, 합병 및 인수 등의 전략을 채택했습니다.
조사 범위
이 보고서에서는 모바일 헬스 솔루션 시장을 분석하고, 제공, 사용 사례, 최종사용자, 지역을 기반으로 각 부문 시장 규모와 향후 성장 가능성을 추정하고 있습니다. 또한 시장 성장에 영향을 미치는 요인(촉진요인, 억제요인, 기회, 과제 등)에 대해서도 분석하고 있습니다. 더불어, 이해관계자에게 주어진 기회와 과제를 평가하고 있습니다. 또한 이 보고서에서는 마이크로 시장의 성장 동향, 전망 및 모바일 헬스 솔루션 시장 전체에 대한 기여도에 대해서도 조사하고 있습니다. 더불어 5개 주요 지역별로 각 시장 부문의 매출 예측을 제시하고 있습니다. 아울러, 본 시장의 주요 기업에 대한 경쟁 분석과 더불어 각 기업의 프로필, 제품 라인업, 최근 동향 및 주요 시장 전략에 대해서도 소개하고 있습니다.
이 보고서를 구매해야 하는 이유
이 보고서는 기존 기업은 물론, 신규 진입 기업 및 중소기업이 시장 동향을 파악하는 데 도움이 되며, 결과적으로 시장 점유율 확대로 이어집니다. 이 보고서를 구매한 기업은 다음 전략 중 하나 또는 여러 가지를 활용하여 시장내 입지를 강화할 수 있습니다.
이 리포트에서는 다음 사항에 대한 인사이트를 제공합니다. :
- 주요 촉진요인(스마트폰, 태블릿, 기타 모바일 플랫폼의 보급 확대, 만성질환 관리에서 커넥티드 기기 및 모바일 헬스 앱의 이용 확대, 의료 제공 비용 절감, 환자 중심 의료 제공에 대한 관심 증가, 재택 의료 서비스에 대한 수요 증가) 분석, 제약 요인(기준 및 규제 부재, 충분한 보상 제도 미비), 기회(신흥 시장에서의 채택 확대, 모바일 플랫폼에서의 모바일 헬스 솔루션 채택 확대), 과제(모바일 헬스 기기 및 앱의 특허 보호, 데이터 보안 미비, 데이터 도난 및 의료 사기 관련 우려)는 모바일 헬스 솔루션 시장의 성장에 기여하는 요인입니다.
- 제품 개발/혁신: 모바일 헬스 솔루션 시장의 향후 동향, 연구개발 활동 및 소프트웨어 출시에 대한 상세한 분석
- 시장 개발: 수익성이 높은 신흥 시장, 제공 서비스 유형, 사용 사례, 최종사용자 및 지역에 대한 포괄적인 정보
- 시장 다각화: 모바일 헬스 솔루션 시장의 소프트웨어 포트폴리오, 급성장 지역, 최근 동향 및 투자에 대한 포괄적인 정보
- 경쟁사 평가: Koninklijke Philips N.V.(네덜란드), Medtronic(아일랜드), Abbott(미국), ResMed(미국),Dexcom, Inc.(미국), GE HealthCare(미국), athenahealth(미국), Optum(미국), Teladoc Health(미국), AliveCor, Inc.(미국) 등 주요 참여 기업에 대한 정보
자주 묻는 질문
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 테크놀러지, 특허, 디지털 기술, AI 도입에 의한 전략적 파괴
제7장 고객 상황과 구매 행동
제8장 모바일 헬스 솔루션 시장(오퍼링별)
제9장 모바일 헬스 솔루션 시장(사용 사례별)
제10장 모바일 헬스 솔루션 시장(최종사용자별)
제11장 모바일 헬스 솔루션 시장(지역별)
제12장 경쟁 구도
제13장 기업 개요
제14장 조사 방법
제15장 부록
KSA 26.10.01The global mHealth solutions market is forecast to reach USD 275.44 billion by 2031, up from USD 109.05 billion in 2026, at a CAGR of 20.4% over the forecast period. Government policies and regulatory initiatives increasingly support the adoption of mHealth solutions by establishing frameworks for mobile medical applications, connected medical devices, remote patient monitoring, AI-enabled healthcare software, and digital health infrastructure. In the US, the FDA applies a risk-based regulatory framework to mobile medical applications and device software, while recent 2026 guidance on clinical decision support software and low-risk wellness technologies provides greater clarity for digital health developers.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Offering, Use Case, and End User |
| Regions covered | North America, Europe, Asia Pacific, Latin America, and Middle East & Africa |
In addition, the FDA launched the TEMPO Digital Health Devices Pilot in 2026 to promote access to certain digital health devices while maintaining patient safety requirements. The Australian Digital Health Agency has developed a national Assessment Framework for mHealth Apps to help consumers and healthcare professionals assess the credibility, safety, usability, and clinical value of mobile health applications. These initiatives provide greater regulatory clarity and confidence around mHealth applications, supporting their development, evaluation, and adoption across the healthcare system.
By offering, the mHealth services segment is growing at a significant rate during the forecast period.
mHealth services are experiencing significant growth as healthcare systems increasingly adopt technology-enabled models for continuous, remote, and home-based care. This expansion is driven by the growing prevalence of chronic diseases, the need for continuous patient monitoring, rising demand for home healthcare, and the increasing use of connected medical devices that transmit health information to healthcare providers. For example, Philips' Care Orchestrator enables healthcare providers to remotely monitor and manage patients with sleep apnea and respiratory conditions, receive adherence and clinical reports, and prioritize patients who require intervention.
By end user, the healthcare providers segment held a significant share of the MHealth solutions market in 2025.
By end user, the mHealth solutions market is segmented into patients/consumers, healthcare providers, healthcare payers, and other end users. This segmentation is driven by the growing adoption of digital technologies to improve patient monitoring, clinical decision-making, care coordination, and healthcare delivery. Hospitals, clinics, and other healthcare providers are increasingly integrating mHealth applications, connected medical devices, and remote monitoring services into clinical workflows to enable continuous access to patient data and support timely interventions. The rising prevalence of chronic diseases and the shift toward value-based and home-based care are further encouraging healthcare providers to adopt mHealth solutions. For example, remote patient monitoring enables providers to receive patient-generated health data from connected devices such as blood pressure monitors, glucose monitors, and pulse oximeters, and to use this information to manage patients remotely.
Asia Pacific is expected to register the fastest growth during the forecast period.
Asia Pacific is expected to be the fastest-growing region in the mHealth solutions market, supported by rapid digitalization of healthcare, expanding mobile connectivity, rising chronic disease burden, and increasing demand for remote and home-based care. Government initiatives across the region are further strengthening the digital-health ecosystem. In China, the government continues to expand the "Internet + Healthcare" model, with internet hospitals and online medical services increasing access to remote consultations and digitally enabled care. By 2025, China's internet-healthcare regulatory platform had achieved provincial-level coverage, and the number of internet hospitals had increased significantly. The government is also promoting mobile medical applications, remote consultations, and connected healthcare services, including through the "Broadband Network + Healthy Rural Areas" pilot, which included 117 projects, of which 37 focused on remote medical services. These initiatives are strengthening the region's digital-health infrastructure and creating opportunities for mHealth applications, telehealth, remote patient monitoring, and connected medical devices.
The break-down of primary participants is as mentioned below:
- By Company Type - Tier 1: 32%, Tier 2: 44%, and Tier 3: 24%
- By Designation - Directors: 30%, Manager: 34%, and Others: 36%
- By Region - North America: 40%, Europe: 28%, Asia Pacific: 20%, Latin America: 7% and Middle East & Africa: 5%
Key Players
The prominent players operating in the mHealth solutions market include Koninklijke Philips N.V. (Netherlands), Medtronic (Ireland), Abbott (US), ResMed (US), Dexcom, Inc. (US), GE HealthCare (US), athenahealth (US), Optum (US), among others. These companies adopted strategies such as product launches, product updates, expansions, partnerships, collaborations, and mergers & acquisitions to strengthen their presence in the mHealth solutions market.
Research Coverage
The report analyzes the mHealth solutions market and estimates the market size and future growth potential of various segments based on offering, use case, end user, and region. The report also analyzes factors (such as drivers, restraints, opportunities, and challenges) affecting market growth. It evaluates opportunities and challenges for market stakeholders. The report also studies micro-markets with respect to their growth trends, prospects, and contributions to the total mHealth solutions market. The report forecasts the revenue of the market segments with respect to five major regions. The report also provides a competitive analysis of the key players in this market, along with their company profiles, product offerings, recent developments, and key market strategies.
Reasons to Buy the Report
This report will help established firms as well as new entrants and smaller firms gauge the pulse of the market, which, in turn, would help them garner a greater share of the market. Firms purchasing the report could use one or more of the following strategies to strengthen their positions in the market.
This report provides insights into:
- Analysis of key drivers (increasing penetration of smartphones, tablets, and other mobile platforms, increasing utilization of connected devices and mHealth apps to manage chronic diseases, cost containment in healthcare delivery, rising focus on patient-centric healthcare delivery, increasing demand for home healthcare services), restraints (lack of standards & regulations and sufficient reimbursement), opportunities (Growing adoption across emerging markets, growing adoption of mHealth solutions in mobile platforms), challenges (patent protection for mHealth devices and app, lack of data security and concerns regarding data theft and healthcare fraud) are factors contributing the growth of the mHealth solutions market.
- Product Development/Innovation: Detailed insights into upcoming trends, research & development activities, and software launches in the mHealth solutions market
- Market Development: Comprehensive information on lucrative emerging markets, type of offering, use case, end user, and region
- Market Diversification: Exhaustive information about software portfolios, growing geographies, recent developments, and investments in mHealth solutions market
- Competitive Assessment: In-depth assessment of market share, growth strategies, product offerings, company evaluation quadrant, and capabilities of leading players in the global mHealth solutions market, such as Koninklijke Philips N.V. (Netherlands), Medtronic (Ireland), Abbott (US), ResMed (US), Dexcom, Inc. (US), GE HealthCare (US), athenahealth (US), Optum (US), Teladoc Health (US), AliveCor, Inc. (US), among others
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.4 LIMITATIONS
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 MHEALTH SOLUTIONS MARKET OVERVIEW
- 3.2 MHEALTH SOLUTIONS MARKET, BY OFFERING & REGION
- 3.3 MHEALTH SOLUTIONS MARKET: GEOGRAPHIC SNAPSHOT
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing penetration of smartphones, tablets, and other mobile platforms
- 4.2.1.2 Rising focus on patient-centric healthcare delivery
- 4.2.1.3 Rapid adoption of wearables expands connected mHealth ecosystems
- 4.2.1.4 Chronic disease burden drives demand for remote monitoring and connected devices
- 4.2.2 RESTRAINTS
- 4.2.2.1 Complexity of regulatory landscape
- 4.2.2.2 Fragmentation of mHealth ecosystem
- 4.2.2.3 Interoperability constraints
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 AI and predictive analytics expand mHealth capabilities
- 4.2.3.2 Growing adoption across emerging markets
- 4.2.3.3 Strategic partnerships and collaborations among healthcare companies and mHealth providers
- 4.2.3.4 Telehealth growth expands mobile care delivery
- 4.2.4 CHALLENGES
- 4.2.4.1 Reimbursement barriers restrict wider mHealth adoption
- 4.2.4.2 Concerns associated with data security
- 4.2.4.3 Rapid Technology Evolution Increases mHealth Development Complexity
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL HEALTHCARE IT INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 INDICATIVE PRICE FOR MHEALTH SOLUTIONS, BY END USER (2025)
- 5.5.2 INDICATIVE PRICE FOR MHEALTH SOLUTIONS MARKET, BY REGION (2025)
- 5.6 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.7 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 CASE STUDY ANALYSIS
- 5.9.1 CASE 1: CASE STUDY 1: CLINICAS DEL AZUCAR (CDA)
- 5.9.2 CASE STUDY 2: NOVA HOSPITAL & ENOVACOM
- 5.9.3 CASE STUDY 3: APPLE & NHS TEAMS
- 5.10 IMPACT OF 2025 US TARIFF - OVERVIEW
- 5.10.1 INTRODUCTION
- 5.10.2 KEY TARIFF RATES
- 5.10.3 PRICE IMPACT ANALYSIS
- 5.10.4 IMPACT ON COUNTRY/REGION
- 5.10.4.1 US
- 5.10.4.2 Europe
- 5.10.4.3 Asia Pacific
- 5.10.5 IMPACT ON END USERS
- 5.10.5.1 Healthcare providers
- 5.10.5.2 Healthcare payers
- 5.10.5.3 Patients and consumers
- 5.10.5.4 Other end users (Academic institutes, research centers, government bodies, etc.)
6 STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, DIGITAL, AND AI ADOPTION
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 AI AND MACHINE LEARNING
- 6.1.2 5G/6G CONNECTIVITY
- 6.1.3 DIGITAL BIOMARKERS
- 6.1.4 COMPLEMENTARY TECHNOLOGIES
- 6.1.5 CONNECTED MEDICAL DEVICES
- 6.1.6 CLOUD COMPUTING
- 6.1.7 TELEMEDICINE PLATFORMS
- 6.1.8 ADJACENT TECHNOLOGIES
- 6.1.8.1 Precision medicine
- 6.1.8.2 Clinical decision support systems
- 6.1.8.3 Healthcare data analytics
- 6.2 PATENT ANALYSIS
- 6.2.1 PATENT PUBLICATION TRENDS FOR THE MHEALTH SOLUTIONS
- 6.2.2 INSIGHTS: JURISDICTION AND TOP APPLICANT ANALYSIS
- 6.3 FUTURE APPLICATIONS
- 6.3.1 AI-POWERED PREDICTIVE HEALTH MONITORING
- 6.3.2 PERSONALIZED DIGITAL HEALTH COACHING
- 6.3.3 CONTINUOUS REMOTE PATIENT MONITORING
- 6.3.4 AI-ENABLED EARLY DISEASE DETECTION
- 6.3.5 MOBILE MEDICATION ADHERENCE AND MANAGEMENT
- 6.4 IMPACT OF AI/GEN AI ON MHEALTH SOLUTIONS MARKET
- 6.4.1 INTRODUCTION
- 6.4.2 MARKET POTENTIAL OF AI/GEN AI IN MHEALTH SOLUTIONS MARKET
- 6.4.3 CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION
- 6.4.3.1 Cottage health expands AI-assisted virtual care and patient safety platform enterprise-wide
- 6.4.3.2 Apollo Hospitals deploys AI-enabled connected care across healthcare continuum
- 6.4.4 IMPACT OF AI/GEN AI ON INTERCONNECTED AND ADJACENT ECOSYSTEMS
- 6.4.4.1 AI-powered symptom assessment & triage
- 6.4.4.2 Predictive health analytics
- 6.4.4.3 Conversational health assistants
- 6.4.4.4 Medication & treatment support
- 6.4.5 USER READINESS AND IMPACT ASSESSMENT
- 6.4.5.1 User readiness
- 6.4.5.1.1 Healthcare providers
- 6.4.5.1.2 Healthcare payers
- 6.4.5.1.3 Patients/Consumers
- 6.4.5.2 Impact assessment
- 6.4.5.2.1 User A: Healthcare providers
- 6.4.5.2.1.1 Implementation
- 6.4.5.2.1.2 Impact
- 6.4.5.2.2 User B: Healthcare payers
- 6.4.5.2.2.1 Implementation
- 6.4.5.2.2.2 Impact
- 6.4.5.2.3 User B: Patients/Consumers
- 6.4.5.2.3.1 Implementation
- 6.4.5.2.3.2 Impact
- 6.4.5.2.1 User A: Healthcare providers
- 6.4.5.1 User readiness
- 6.4.6 REGULATORY BODIES, GOVERNMENT AGENCIES, & OTHER ORGANIZATIONS
- 6.4.7 REGULATORY ANALYSIS
7 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 7.1 INTRODUCTION
- 7.2 DECISION-MAKING PROCESS
- 7.3 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 7.3.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 7.3.2 BUYING CRITERIA
- 7.4 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 7.5 UNMET NEEDS FROM VARIOUS END USERS
- 7.5.1 UNMET NEEDS
- 7.5.2 END USER EXPECTATIONS
- 7.6 MARKET PROFITABILITY
8 MHEALTH SOLUTIONS MARKET, BY OFFERING
- 8.1 INTRODUCTION
- 8.2 MHEALTH APPS
- 8.2.1 GROWING ADOPTION FOR PERSONALIZED AND CONNECTED HEALTHCARE TO DRIVE SEGMENT
- 8.2.2 CHRONIC CARE MANAGEMENT APPS
- 8.2.2.1 Increasing need for continuous, personalized chronic care management to boost demand
- 8.2.3 MENTAL & BEHAVIORAL HEALTH APPS
- 8.2.3.1 Growing demand for accessible and convenient mental healthcare to drive segment
- 8.2.4 GENERAL HEALTH & FITNESS APPS
- 8.2.4.1 Focus on personalized health, fitness, and wellness management to propel segment
- 8.2.5 MEDICATION MANAGEMENT & ADHERENCE APPS
- 8.2.5.1 Segment driven by need for improved medication adherence and treatment management
- 8.2.6 WOMEN'S HEALTH APPS
- 8.2.6.1 Rapid adoption of mobile technologies for personalized women's health management
- 8.2.7 DIAGNOSTIC & SYMPTOM CHECKER APPS
- 8.2.7.1 Increasing need for convenient digital health assessment and diagnostic support to drive segment
- 8.2.8 PATIENT HEALTH RECORDS APPS/PATIENT PORTAL APPS
- 8.2.8.1 Growing need for accessible and connected patient health information to boost market
- 8.2.9 CLINICAL DECISION SUPPORT APPS
- 8.2.9.1 Rapid adoption of medical applications for clinical monitoring and decision support to drive segment
- 8.2.10 OTHER HEALTHCARE APPS
- 8.2.10.1 High demand for digital healthcare information and patient engagement to grow market
- 8.3 CONNECTED MEDICAL DEVICES
- 8.3.1 ADVANCING CONNECTED TECHNOLOGIES FOR CONTINUOUS AND PERSONALIZED HEALTH MONITORING TO DRIVE MARKET
- 8.3.2 VITAL SIGNS MONITORING DEVICES
- 8.3.2.1 Expanding role of connected monitoring in continuous patient assessment to boost segment
- 8.3.3 SLEEP MONITORING DEVICES
- 8.3.3.1 Advancing connected technologies for sleep health management
- 8.3.4 MULTIPARAMETER & REMOTE PATIENT MONITORING DEVICES
- 8.3.4.1 Increasing integration of multiparameter monitoring across care settings to boost market
- 8.3.5 FETAL & MATERNAL MONITORING DEVICES
- 8.3.5.1 Enhanced maternal and fetal care through wireless monitoring to drive segment
- 8.3.6 NEUROLOGICAL MONITORING DEVICES
- 8.3.6.1 Segment driven by advances in connected technologies for neurological monitoring
- 8.3.7 SMART INHALERS & DRUG DELIVERY DEVICES
- 8.3.7.1 Improved medication management through connected drug delivery to boost market
- 8.3.8 OTHER CONNECTED MEDICAL DEVICES
- 8.3.8.1 Broadening applications of connected devices in specialized healthcare
- 8.4 MHEALTH SERVICES
- 8.4.1 EXPANDING ACCESS TO CONNECTED AND PATIENT-CENTRIC HEALTHCARE SERVICES TO BOOST MARKET
- 8.4.2 REMOTE PATIENT MONITORING SERVICES
- 8.4.2.1 Extending clinical oversight beyond traditional care settings - key driver
- 8.4.3 TELEHEALTH SERVICES
- 8.4.3.1 Broad access to virtual and on-demand healthcare to boost demand
- 8.4.4 DIGITAL DISEASE MANAGEMENT SERVICES
- 8.4.4.1 Shifting chronic disease management toward continuous digital care
- 8.4.5 OTHERS
- 8.4.5.1 Connected care strengthened through implementation, support, and digital rehabilitation
9 MHEALTH SOLUTIONS MARKET, BY USE CASE
- 9.1 INTRODUCTION
- 9.2 PREVENTIVE CARE & WELLNESS
- 9.2.1 AI AND WEARABLES DRIVE PREVENTIVE MHEALTH ADOPTION
- 9.3 SCREENING & DIAGNOSIS
- 9.3.1 MOBILE AND AI-ENABLED TOOLS EXPANDING ACCESS TO EARLY SCREENING & DIAGNOSIS
- 9.4 TREATMENT & DISEASE MANAGEMENT
- 9.4.1 CONNECTED DEVICES AND DIGITAL THERAPEUTICS STRENGTHENING MHEALTH-BASED DISEASE MANAGEMENT
- 9.5 PATIENT MONITORING
- 9.5.1 WEARABLES AND REMOTE MONITORING ENABLE CONTINUOUS PATIENT OVERSIGHT
- 9.6 MEDICATION MANAGEMENT & ADHERENCE
- 9.6.1 MOBILE PLATFORMS AND DIGITAL TOOLS IMPROVING MEDICATION ADHERENCE
- 9.7 CONSULTING & CARE COORDINATION
- 9.7.1 DIGITAL CONNECTIVITY ENABLES ENHANCED COORDINATED CARE DELIVERY
- 9.8 REHABILITATION & RECOVERY
- 9.8.1 DIGITAL REHABILITATION EXTENDS RECOVERY BEYOND TRADITIONAL THERAPY SETTINGS
- 9.9 OTHERS
- 9.9.1 MOBILE HEALTH EXPANDS POPULATION-LEVEL HEALTH EDUCATION AND AWARENESS
10 MHEALTH SOLUTIONS MARKET, BY END USER
- 10.1 INTRODUCTION
- 10.2 PATIENTS/CONSUMERS
- 10.2.1 PERSONALIZED AND CONVENIENT HEALTHCARE TO LEAD TO MARKET GROWTH
- 10.3 HEALTHCARE PROVIDERS
- 10.3.1 HEALTHCARE PROVIDERS INTEGRATING MHEALTH INTO CONNECTED CARE DELIVERY
- 10.4 HEALTHCARE PAYERS
- 10.4.1 LEVERAGING MHEALTH TO IMPROVE OUTCOMES AND MANAGE HEALTHCARE COSTS
- 10.5 OTHER END USERS
- 10.5.1 SCALED MHEALTH FOR POPULATION-LEVEL HEALTHCARE TO DRIVE SEGMENT
11 MHEALTH SOLUTIONS MARKET, BY REGION
- 11.1 INTRODUCTION
- 11.2 NORTH AMERICA
- 11.2.1 MACROECONOMIC OUTLOOK FOR NORTH AMERICA
- 11.2.2 US
- 11.2.2.1 Market driven by RPM and telehealth expansion
- 11.2.3 CANADA
- 11.2.3.1 Market driven by digital adoption and interoperability
- 11.3 EUROPE
- 11.3.1 MACROECONOMIC OUTLOOK FOR EUROPE
- 11.3.2 GERMANY
- 11.3.2.1 DiGA reimbursement and digital health integration to drive market
- 11.3.3 UK
- 11.3.3.1 Market driven by NHS digitalization and AI adoption
- 11.3.4 FRANCE
- 11.3.4.1 Market driven by telemonitoring and digital health infrastructure
- 11.3.5 ITALY
- 11.3.5.1 Market driven by PNRR, telemedicine, and EHR expansion
- 11.3.6 SPAIN
- 11.3.6.1 Rising funding for digital health plans to boost market
- 11.3.7 REST OF EUROPE
- 11.4 ASIA PACIFIC
- 11.4.1 MACROECONOMIC OUTLOOK FOR ASIA PACIFIC
- 11.4.2 CHINA
- 11.4.2.1 Market driven by internet healthcare and AI-enabled care
- 11.4.3 JAPAN
- 11.4.3.1 Rising geriatric population and subsequent rise in preventive care to drive market
- 11.4.4 INDIA
- 11.4.4.1 Government initiatives and digital health to drive market growth
- 11.4.5 AUSTRALIA
- 11.4.5.1 Growing remote monitoring and connected health records expansion to drive market
- 11.4.6 SOUTH KOREA
- 11.4.6.1 Strategic partnerships and AI innovations accelerating mHealth adoption
- 11.4.7 REST OF ASIA PACIFIC
- 11.5 LATIN AMERICA
- 11.5.1 MACROECONOMIC OUTLOOK FOR LATIN AMERICA
- 11.5.2 BRAZIL
- 11.5.2.1 Market driven by SUS digitalization and connected care
- 11.5.3 MEXICO
- 11.5.3.1 Market driven by AI-enabled chronic care
- 11.5.4 REST OF LATIN AMERICA
- 11.6 MIDDLE EAST & AFRICA
- 11.7 MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA
- 11.7.1 GCC
- 11.7.1.1 Market driven by virtual hospitals and AI-enabled care
- 11.7.2 SAUDI ARABIA
- 11.7.2.1 Expanding connected healthcare ecosystem to boost market
- 11.7.3 UAE
- 11.7.3.1 Connected records and smart health apps to boost market
- 11.7.4 REST OF GCC
- 11.7.4.1 Strengthening of connected healthcare ecosystems through digital health transformation to propel market
- 11.7.5 SOUTH AFRICA
- 11.7.5.1 Market driven by mobile health and digital public healthcare
- 11.7.6 REST OF MIDDLE EAST & AFRICA
- 11.7.1 GCC
12 COMPETITIVE LANDSCAPE
- 12.1 INTRODUCTION
- 12.2 KEY PLAYER STRATEGY/RIGHT TO WIN
- 12.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN MHEALTH SOLUTIONS MARKET
- 12.3 REVENUE ANALYSIS, 2021-2025
- 12.4 MARKET SHARE ANALYSIS, 2025
- 12.4.1 RANKING OF KEY MARKET PLAYERS
- 12.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 12.5.1 STARS
- 12.5.2 EMERGING LEADERS
- 12.5.3 PERVASIVE PLAYERS
- 12.5.4 PARTICIPANTS
- 12.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 12.5.5.1 Company footprint
- 12.5.5.2 Regional footprint
- 12.5.5.3 Offering footprint
- 12.5.5.4 Use case footprint
- 12.5.5.5 End user footprint
- 12.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 12.6.1 PROGRESSIVE COMPANIES
- 12.6.2 RESPONSIVE COMPANIES
- 12.6.3 DYNAMIC COMPANIES
- 12.6.4 STARTING BLOCKS
- 12.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 12.6.5.1 Detailed list of key startups/SMEs
- 12.6.5.2 Company footprint (startups/SMEs)
- 12.7 COMPANY VALUATION AND FINANCIAL METRICS
- 12.7.1 FINANCIAL METRICS
- 12.7.2 COMPANY VALUATION
- 12.8 BRAND/PRODUCT COMPARISON
- 12.9 COMPETITIVE SCENARIO
- 12.9.1 PRODUCT/SERVICE LAUNCHES & APPROVALS
- 12.9.2 DEALS
- 12.9.3 OTHER DEVELOPMENTS
13 COMPANY PROFILES
- 13.1 KEY PLAYERS
- 13.1.1 KONINKLIJKE PHILIPS N.V.
- 13.1.1.1 Business overview
- 13.1.1.2 Products & services offered
- 13.1.1.3 Recent developments
- 13.1.1.3.1 Product/Service launches & approvals
- 13.1.1.3.2 Deals
- 13.1.1.3.3 Expansions
- 13.1.1.3.4 Other developments
- 13.1.1.4 MnM view
- 13.1.1.4.1 Right to win
- 13.1.1.4.2 Strategic choices
- 13.1.1.4.3 Weaknesses & competitive threats
- 13.1.2 MEDTRONIC
- 13.1.2.1 Business overview
- 13.1.2.2 Products & services offered
- 13.1.2.3 Recent developments
- 13.1.2.3.1 Product/Service launches & approvals
- 13.1.2.3.2 Deals
- 13.1.2.4 MnM view
- 13.1.2.4.1 Right to win
- 13.1.2.4.2 Strategic choices
- 13.1.2.4.3 Weaknesses & competitive threats
- 13.1.3 ABBOTT
- 13.1.3.1 Business overview
- 13.1.3.2 Products & services offered
- 13.1.3.3 Recent developments
- 13.1.3.3.1 Product/Service launches & approvals
- 13.1.3.3.2 Deals
- 13.1.3.4 MnM view
- 13.1.3.4.1 Right to win
- 13.1.3.4.2 Strategic choices
- 13.1.3.4.3 Weaknesses & competitive threats
- 13.1.4 RESMED
- 13.1.4.1 Business overview
- 13.1.4.2 Products & services offered
- 13.1.4.3 Recent developments
- 13.1.4.3.1 Product/Service launches & approvals
- 13.1.4.3.2 Deals
- 13.1.4.4 MnM view
- 13.1.4.4.1 Right to win
- 13.1.4.4.2 Strategic choices
- 13.1.4.4.3 Weaknesses & competitive threats
- 13.1.5 DEXCOM, INC.
- 13.1.5.1 Business overview
- 13.1.5.2 Products & services offered
- 13.1.5.3 Recent developments
- 13.1.5.3.1 Product/Service launches & approvals
- 13.1.5.3.2 Deals
- 13.1.5.4 MnM view
- 13.1.5.4.1 Right to win
- 13.1.5.4.2 Strategic choices
- 13.1.5.4.3 Weaknesses & competitive threats
- 13.1.6 GE HEALTHCARE
- 13.1.6.1 Business overview
- 13.1.6.2 Products & services offered
- 13.1.6.3 Recent developments
- 13.1.6.3.1 Product/Service launches & approvals
- 13.1.6.3.2 Deals
- 13.1.6.3.3 Other developments
- 13.1.7 OMRON HEALTHCARE, INC.
- 13.1.7.1 Business overview
- 13.1.7.2 Products & services offered
- 13.1.7.3 Recent developments
- 13.1.7.3.1 Product/Service launches & approvals
- 13.1.7.4 Recent developments
- 13.1.7.4.1 Deals
- 13.1.8 ORACLE
- 13.1.8.1 Business overview
- 13.1.8.2 Products & services offered
- 13.1.8.3 Recent developments
- 13.1.8.3.1 Product/Service launches & approvals
- 13.1.8.3.2 Deals
- 13.1.8.3.3 Expansions
- 13.1.9 BOSTON SCIENTIFIC CORPORATION
- 13.1.9.1 Business overview
- 13.1.9.2 Products & services offered
- 13.1.9.3 Recent developments
- 13.1.9.3.1 Product/Service launches & approvals
- 13.1.9.4 Recent developments
- 13.1.9.4.1 Deals
- 13.1.10 SIEMENS HEALTHCARE PRIVATE LIMITED
- 13.1.10.1 Business overview
- 13.1.10.2 Products & services offered
- 13.1.10.3 Recent developments
- 13.1.10.3.1 Product/Service launches & approvals
- 13.1.10.3.2 Expansions
- 13.1.11 OPTUM
- 13.1.11.1 Business overview
- 13.1.11.2 Products & services offered
- 13.1.11.3 Recent developments
- 13.1.11.3.1 Deals
- 13.1.12 ATHENAHEALTH
- 13.1.12.1 Business overview
- 13.1.12.2 Products & services offered
- 13.1.12.3 Recent developments
- 13.1.12.3.1 Product/Service launches & approvals
- 13.1.12.3.2 Deals, January 2023-July 2026
- 13.1.13 EMPATICA INC.
- 13.1.13.1 Business overview
- 13.1.13.2 Products & services offered
- 13.1.13.3 Recent developments
- 13.1.13.3.1 Product/Service launches & approvals
- 13.1.13.3.2 Deals
- 13.1.13.3.3 Expansions
- 13.1.14 TELADOC HEALTH, INC.
- 13.1.14.1 Business overview
- 13.1.14.2 Products & services offered
- 13.1.14.3 Recent developments
- 13.1.14.3.1 Product/Service launches & approvals
- 13.1.14.3.2 Deals
- 13.1.15 WELLDOC, INC.
- 13.1.15.1 Business overview
- 13.1.15.2 Products & services offered
- 13.1.15.3 Recent developments
- 13.1.15.3.1 Product/Service launches & approvals
- 13.1.15.3.2 Deals
- 13.1.16 ALIVECOR, INC.
- 13.1.16.1 Business overview
- 13.1.16.2 Products & services offered
- 13.1.16.3 Recent developments
- 13.1.16.3.1 Product/Service launches & approvals
- 13.1.16.3.2 Deals
- 13.1.17 BIOFOURMIS
- 13.1.17.1 Business overview
- 13.1.17.2 Products & services offered
- 13.1.17.3 Recent developments
- 13.1.17.3.1 Deals
- 13.1.18 TUNSTALL GROUP
- 13.1.18.1 Business overview
- 13.1.18.2 Products & services offered
- 13.1.19 GARMIN LTD.
- 13.1.19.1 Business overview
- 13.1.19.2 Products & services offered
- 13.1.19.3 Recent developments
- 13.1.19.3.1 Product/Service launches & approvals
- 13.1.19.3.2 Deals
- 13.1.20 AIRSTRIP TECHNOLOGIES, INC
- 13.1.20.1 Business overview
- 13.1.20.2 Products & services offered
- 13.1.20.3 Recent developments
- 13.1.20.3.1 Product/Service launches & approvals
- 13.1.20.3.2 Deals
- 13.1.1 KONINKLIJKE PHILIPS N.V.
- 13.2 OTHER PLAYERS
- 13.2.1 NATURAL CYCLES NORDIC AB
- 13.2.2 SIDEKICK HEALTH
- 13.2.3 BUOY HEALTH, INC.
- 13.2.4 VIASUALDX
- 13.2.5 FIMO HEALTH
14 RESEARCH METHODOLOGY
- 14.1 RESEARCH DATA
- 14.1.1 SECONDARY DATA
- 14.1.1.1 Key data from secondary sources
- 14.1.2 PRIMARY DATA
- 14.1.2.1 Key data from primary sources
- 14.1.2.2 Breakdown of primary sources
- 14.1.1 SECONDARY DATA
- 14.2 MARKET SIZE ESTIMATION
- 14.3 MARKET SIZE ESTIMATION
- 14.4 MARKET BREAKDOWN DATA TRIANGULATION
- 14.5 MARKET SHARE ESTIMATION
- 14.6 STUDY ASSUMPTIONS
- 14.7 RESEARCH LIMITATIONS
- 14.7.1 METHODOLOGY-RELATED LIMITATIONS
- 14.8 RISK ASSESSMENT
15 APPENDIX
- 15.1 DISCUSSION GUIDE
- 15.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 15.3 CUSTOMIZATION OPTIONS
- 15.4 RELATED REPORTS
- 15.5 AUTHOR DETAILS


