
|
시장보고서
상품코드
2136428
임상시험 서비스 시장 : 서비스 유형별, 상별, 딜리버리 모델별, 시험 디자인별, 치료 분야별, 모달리티별, 최종사용자별, 지역별 - 세계 예측(-2031년)Clinical Trial Services Market by Type (Lab, Monitoring, Contracts, Recruitment, PV, Biostatistics), Phase, Therapy (Oncology, Neurology, Dermatology, CVD), Modality (Biologics, Devices), Delivery Model (FSP, Hybrid) - Global forecast to 2031 |
||||||

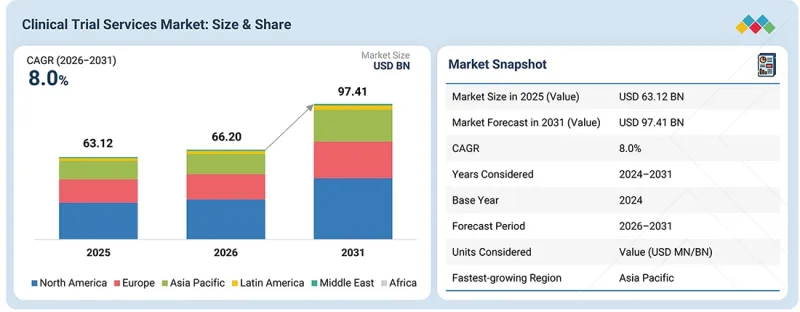
임상시험 서비스 시장 규모는 2026년 662억 달러에서 2031년까지 974억 1,000만 달러에 달할 것으로 예측되며, 2026년부터 2031년까지 예측 기간 동안 CAGR은 8.0%가 될 전망입니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 서비스 유형별, 상별, 딜리버리 모델별, 시험 디자인별, 치료 분야별, 모달리티별, 최종사용자별, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카 |
세포·유전자 치료(CGT) 및 정밀 의학 파이프라인이 확대됨에 따라, 제1상-제4상 임상시험에 대한 전문적인 외부 위탁 서비스에 대한 수요가 증가하고 있습니다. 이러한 프로그램에서는 복잡한 프로토콜, 바이오마커 및 유전체 기반 피험자 선정, 규모가 작고 지리적으로 분산된 피험자 집단, 전문적인 임상시험 시설 요건, 엄격한 검체 취급, 맞춤형 임상용 의약품 공급 및 물류, 장기간에 걸친 안전성 추적 관찰 등이 빈번하게 요구됩니다. 이러한 요건으로 인해 각 후원사는 임상시험 기관 선정 및 관리, 피험자 모집, 임상 모니터링, 검사 및 바이오마커 측정, 데이터 관리, 의약품 안전성 감시, 그리고 임상시험 물류 분야에서 강점을 가진 CRO나 전문 제공업체에 업무를 위탁하고 있습니다.
서비스 유형별로는 2025년 임상시험 서비스 시장에서 검사 서비스 부문이 두 번째로 큰 점유율을 차지했습니다.
서비스 유형별로 보면 임상시험 서비스 시장은 검사 서비스, 임상시험 기관의 관리·모니터링, 임상시험 기관과의 계약·지급, 피험자 모집·유지, 메디컬 라이팅, 임상시험용 의약품 공급·물류 서비스, 안전성 및 의약품 안전성 감시, 임상시험 데이터 관리 서비스, 컨설팅, 그리고 기타 임상시험 서비스로 분류됩니다. 2025년, 검사 서비스는 임상시험 기관의 관리·모니터링에 이어 시장에서 두 번째로 큰 점유율을 차지했습니다. 검사 서비스의 점유율이 높은 이유는 제1상-제4상 임상시험에서 약물 농도 측정, 약동학 평가, 바이오마커 및 면역원성 평가, 그리고 유효성 및 안전성 평가를 위한 신뢰성 높은 검사 데이터를 생성하기 위해 분석 시험 및 생물학적 분석 시험에 대한 광범위한 수요가 있기 때문입니다. 바이오의약품, 항암제, 세포·유전자 치료 및 기타 복잡한 치료법의 개발이 진행됨에 따라 전문적인 분석법, 바이오마커 검사, 고품질의 생물분석 역량에 대한 수요가 더욱 높아지고 있으며, 의뢰사는 이러한 업무를 CRO나 전문 검사 기관에 위탁하는 경향이 강해지고 있습니다.
최종사용자별로는 2025년 임상시험 서비스 시장에서 제약·바이오의약품 기업이 가장 큰 점유율을 차지했습니다.
최종사용자/스폰서별로 보면 임상시험 서비스 시장은 제약·바이오의약품 기업, 의료기기 기업 및 학술 기관으로 구분됩니다. 제약·바이오의약품 기업은 다시 대기업, 중견 기업 및 중소기업으로 세분화됩니다. 2025년에는 제약·바이오의약품 기업이 가장 큰 시장 점유율을 차지했습니다. 이 부문의 높은 점유율은 광범위한 1상-4상 임상 개발 파이프라인, 막대한 연구개발비, 프로토콜의 복잡화, 그리고 전 세계 임상시험 수행에 있어 CRO에 대한 의존도 증가에 의해 주도되고 있습니다. 아웃소싱을 통해 이러한 스폰서들은 전문적인 치료 분야에 대한 인사이트, 전 세계 임상시험 기관 및 피험자 네트워크, 확장 가능한 임상 운영 자원, 그리고 임상시험 기관의 관리·모니터링,임상 검사, 데이터 관리, 의약품 안전성 모니터링, 피험자 모집, 임상시험 물류 분야의 역량을 활용할 수 있을 뿐만 아니라, 운영의 유연성과 개발 효율성을 향상시킬 수 있습니다.
지역별로는 2025년에 북미가 시장 점유율에서 가장 큰 비중을 차지했습니다.
2025년, 북미는 확립된 제약 및 바이오의약품 산업, 높은 연구개발비, 그리고 1-4상 임상시험 서비스 아웃소싱에 대한 큰 수요에 힘입어 전 세계 임상시험 서비스 시장에서 가장 큰 점유율을 차지했습니다. 또한, 이 지역은 임상 연구 시설, 병원, 대학 병원, 전문 검사 기관으로 구성된 긴밀한 네트워크의 혜택을 받고 있으며, 대규모이며 복잡한 임상시험을 위한 견고한 인프라를 제공하고 있습니다. 게다가, 특히 미국에서 분산형 및 하이브리드형 임상시험 모델, 디지털 환자 참여 도구,리스크 기반 모니터링, 첨단 임상 데이터 기술이 급속히 보급되면서 임상시험 기관의 관리·모니터링, 피험자 모집·유지, 데이터 관리, 의약품 안전성 감시, 임상 검사, 임상시험 물류와 같은 서비스에 대한 수요를 더욱 부추기고 있습니다. 이러한 요인들로 인해 북미는 임상시험 서비스 아웃소싱 분야의 주요 지역 시장으로서의 입지를 더욱 공고히 하고 있습니다.
본 보고서에서 다룬 기업 개요 목록:
- IQVIA Inc.(미국)
- Thermo Fisher Scientific Inc.(미국)
- Fortrea(미국)
- ICON Plc(아일랜드)
- Syneos Health(미국)
- Laboratory Corporation of America Holdings(미국)
- Medpace(미국)
- Wuxi AppTec(중국)
- Frontage Labs(미국)
- Pharmaron(미국)
- Tigermed(중국)
- SGS Societe Generale de Surveillance SA.(스위스)
- Eurofins Scientific(룩셈부르크)
- Linica(일본)
- Parexel International Corporation(미국)
- Worldwide Clinical Trials(미국)
- Novotech(호주)
- PSI(스위스)
- Allucent(미국)
- Premier Research(미국)
- Clario(미국)
- KCR S.A.(미국)
- Rho, Inc.(미국)
- Advanced Clinical(미국)
조사 범위
본 조사 보고서에서는 임상시험 서비스 시장을 서비스 유형, 단계, 치료 분야, 모달리티, 제공 모델, 시험 설계, 최종사용자/스폰서 및 지역별로 분류하고 있습니다.
본 보고서는 임상시험 서비스 시장의 성장에 영향을 미치는 주요 촉진요인, 기회 및 과제에 대한 상세한 정보를 제공합니다. 여기에는 파이프라인 확대 및 임상시험의 복잡화, 연구개발 투자 증가, CRO가 제공하는 서비스의 유연성, 의약품 개발 기간 단축에 대한 수요, 진화하는 아웃소싱 모델,규제의 현대화, AI 및 데이터 분석, 분산형 및 환자/시험 기관 중심의 임상시험, 피험자 모집 및 유지와 관련된 과제, 그리고 전문 임상 연구 인력 부족 등이 포함됩니다. 또한, 업계 동향, 기술 개발, 규제 및 지속가능성에 관한 고려 사항, 고객 동향, 가격 책정, 생태계 동향, 경쟁 구도에 대해서도 분석하고 있습니다. 주요 시장 참여 기업에 대한 상세한 평가에서는 서비스 포트폴리오, 전략, 시장 내 위치, 제휴, 계약, 그리고 임상시험 서비스 시장과 관련된 서비스 출시, 거래, 합작 투자, 파트너십, 인수합병(M&A) 등 기타 전략적 전개에 대해 포괄적으로 다루고 있습니다.
본 보고서를 구매할 때의 주요 이점
본 보고서는 임상시험 서비스 시장 전체 및 그 하위 부문의 매출에 대한 가장 정확한 추정치를 제공함으로써, 시장을 선도하는 기업과 신규 진입 기업을 지원합니다. 또한 이해관계자가 경쟁 구도를 더 깊이 이해하고, 자사의 비즈니스를 포지셔닝하기 위한 인사이트를 얻어 적절한 시장 진입 전략을 수립하는 데에도 도움이 됩니다. 본 보고서는 이해관계자가 시장 동향을 파악하고, 주요 시장 촉진요인 및 과제에 대한 정보를 얻는 데 도움이 됩니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다:
- 주요 촉진요인 분석(파이프라인의 복잡화 및 전문 치료 분야에서의 임상시험 활동 증가, 연구개발 투자 확대와 견실한 임상 파이프라인의 존재, CRO가 제공하는 서비스의 유연성, 의약품 개발 기간 단축 및 생산성 향상에 대한 수요, 그리고 풀서비스형 CRO에서 FSP/하이브리드/전략적 아웃소싱 모델로의 단계적 전환),임상시험 서비스 시장의 성장에 영향을 미치는 기회(규제 현대화 및 혁신적인 시험 설계, 임상 개발 분야의 AI, 자동화, 데이터 분석, 환자/시험 기관 중심형 및 분산형 임상시험) 및 과제(피험자 모집 및 유지, 그리고 자격을 갖춘 임상 연구 인력 및 전문 지식의 부족)
- 서비스 개발 및 혁신 : 새로 도입되거나 지속적으로 진화하는 임상시험 서비스 및 기술을 활용한 솔루션에 대한 상세한 인사이트
- 시장 개발 : 수익성이 높은 시장에 대한 종합적인 정보 - 본 보고서는 다양한 지역에 걸친 시장을 분석합니다.
- 시장 다각화 : 임상시험 서비스 시장의 신규 서비스, 미개척 지역, 최근 동향 및 투자에 관한 종합적인 정보
- 경쟁사 평가 : Thermo Fisher Scientific Inc.(PPD, Inc.), IQVIA Inc., ICON plc, Laboratory Corporation of America Holdings, Syneos Health, WuXi AppTec, Eurofins Scientific, Parexel International Corporation, Fortrea Inc., Medpace, SGS, Frontage Labs, Pharmaron, Tigermed, BioAgile 등 주요 임상시험 서비스 제공업체의 시장 점유율, 성장 전략, 서비스 제공 내용 및 경쟁 포지셔닝에 대한 상세한 평가를 수행합니다. 본 보고서에서는 임상시험 서비스 시장의 주요 전략, 신규 서비스 출시, 거래, 인수, 제휴, 계약, 합작 투자, 사업 확장, 투자 및 자금 조달 활동, 브랜드/서비스 비교 분석, 그리고 공급업체의 기업 가치 평가 및 재무 지표에 대해 분석하고 있습니다.
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI추진의 영향, 혁신, 향후 응용
제7장 지속가능성과 규제 상황
제8장 고객 상황과 구매 행동
제9장 임상시험 서비스 시장(서비스 유형별)
제10장 임상시험 서비스 시장(상별)
제11장 임상시험 서비스 시장(딜리버리 모델별)
제12장 임상시험 서비스 시장(시험 디자인별)
제13장 임상시험 서비스 시장(치료 분야별)
제14장 임상시험 서비스 시장(모달리티별)
제15장 임상시험 서비스 시장(최종사용자별)
제16장 임상시험 서비스 시장(지역별)
제17장 경쟁 구도
제18장 기업 개요
제19장 조사 방법
제20장 부록
KSM 26.10.07The clinical trial services market is projected to reach USD 97.41 billion by 2031 from USD 66.20 billion in 2026, at a CAGR of 8.0% during the forecast period of 2026 to 2031.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Service Type, Therapy Area, Phase, Study Design, Modality, Delivery Model, End User/Sponsor |
| Regions covered | North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa |
The expanding pipeline of cell & gene therapies (CGTs) and precision medicines is increasing demand for specialized outsourced Phase I-IV clinical trial services. These programs often involve complex protocols, biomarker- or genomic-based patient selection, small and geographically dispersed patient populations, specialized site requirements, stringent sample handling, customized clinical supply and logistics, and extended safety follow-up. Such requirements are encouraging sponsors to engage CROs and specialized providers with capabilities in site identification and management, patient recruitment, clinical monitoring, laboratory and biomarker testing, data management, pharmacovigilance, and clinical trial logistics.
By service type, the laboratory services segment accounted for the second-largest share of the clinical trial services market in 2025.
By service type, the clinical trial services market is segmented into laboratory services, site management and monitoring, site contracts and payments, patient recruitment and retention, medical writing, clinical trial supply & logistics services, safety and pharmacovigilance, clinical trial data management services, consulting, and other clinical trial services. In 2025, laboratory services accounted for the second-largest share of the market, following site management and monitoring. The significant share of laboratory services stems from the extensive need for analytical and bioanalytical testing during Phase I-IV clinical trials to measure drug concentrations, evaluate pharmacokinetics, assess biomarkers and immunogenicity, and generate reliable laboratory data for efficacy and safety assessments. Increasing development of biologics, oncology therapies, cell & gene therapies, and other complex modalities is further increasing demand for specialized assays, biomarker testing, and high-quality bioanalytical capabilities, encouraging sponsors to outsource these activities to CROs and specialized laboratories.
By end user, the pharmaceutical & biopharmaceutical companies accounted for the largest share in the clinical trial services market in 2025.
Based on end user/sponsor, the clinical trial services market is segmented into pharmaceutical & biopharmaceutical companies, medical device companies, and academic institutes. Pharmaceutical & biopharmaceutical companies are further segmented into large and mid-size and small companies. In 2025, pharmaceutical & biopharmaceutical companies accounted for the largest market share. This segment's large share is driven by extensive Phase I-IV clinical development pipelines, substantial R&D expenditure, increasing protocol complexity, and growing reliance on CROs for global trial execution. Outsourcing enables these sponsors to access specialized therapeutic expertise, global site and patient networks, scalable clinical operations resources, and capabilities in site management and monitoring, laboratory testing, data management, pharmacovigilance, patient recruitment, and clinical trial logistics while improving operational flexibility and development efficiency.
By region, North America accounted for the largest share of the market in 2025.
In 2025, North America held the largest share of the global clinical trial services market, supported by a well-established pharmaceutical and biopharmaceutical industry, high R&D expenditure, and substantial demand for outsourced Phase I-IV clinical trial services. The region also benefits from a dense network of clinical research sites, hospitals, academic medical centers, and specialized laboratories, providing strong infrastructure for large-scale and complex clinical studies. In addition, the rapid adoption of decentralized and hybrid trial models, digital patient-engagement tools, risk-based monitoring, and advanced clinical data technologies, particularly in the US, is further supporting demand for services such as site management and monitoring, patient recruitment and retention, data management, pharmacovigilance, laboratory testing, and clinical trial logistics. These factors continue to strengthen North America's position as the leading regional market for outsourced clinical trial services.
List of Companies Profiled in the Report:
- IQVIA Inc. (US)
- Thermo Fisher Scientific Inc. (US)
- Fortrea (US)
- ICON Plc (Ireland)
- Syneos Health (US)
- Laboratory Corporation of America Holdings (US)
- Medpace (US)
- Wuxi AppTec (China)
- Frontage Labs (US)
- Pharmaron (US)
- Tigermed (China)
- SGS Societe Generale de Surveillance SA. (Switzerland)
- Eurofins Scientific (Luxembourg)
- Linical (Japan)
- Parexel International Corporation (US)
- Worldwide Clinical Trials (US)
- Novotech (Australia)
- PSI (Switzerland)
- Allucent (US)
- Premier Research (US)
- Clario (US)
- KCR S.A. (US)
- Rho, Inc. (US)
- Advanced Clinical (US)
Research Coverage
This research report categorizes the clinical trial services market by service type, phase, therapeutic area, modality, delivery model, study design, end user/sponsor, and region.
The report provides detailed information on the key drivers, opportunities, and challenges influencing the growth of the clinical trial services market, including increasing pipeline and trial complexity, growing R&D investment, service flexibility offered by CROs, demand for faster drug-development timelines, evolving outsourcing models, regulatory modernization, AI and data analytics, decentralized and patient/site-centric trials, patient recruitment and retention challenges, and shortages of specialized clinical research talent. It also analyzes industry trends, technology developments, regulatory and sustainability considerations, customer landscape, pricing, ecosystem dynamics, and the competitive landscape. A detailed assessment of key market participants covers their service portfolios, strategies, market positioning, partnerships, agreements, and other strategic developments, including service launches, deals, collaborations, partnerships, and acquisitions associated with the clinical trial services market.
Key Benefits of Buying the Report
The report will help market leaders/new entrants by providing the closest approximations of the revenue numbers for the overall clinical trial services market and its subsegments. It will also help stakeholders better understand the competitive landscape and gain insights to position their business and develop suitable go-to-market strategies. This report will help stakeholders understand the market's pulse and provide information on key market drivers, opportunities, and challenges.
The report provides insights into the following pointers:
- Analysis of key drivers (growing pipeline complexity and increasing clinical-trial activity in specialty therapies, growing R&D investments and presence of a robust clinical pipeline, service flexibility offered by CROs, demand for faster drug-development timelines and productivity improvement, and the gradual shift from full-service CRO toward FSP/hybrid/strategic outsourcing models), opportunities (regulatory modernization and innovative trial designs, AI, automation and data analytics in clinical development, and patient/site-centric and decentralized clinical trials), and challenges (patient recruitment and retention and shortage of qualified clinical research talent and specialized expertise) influencing the growth of the clinical trial services market
- Service Development/Innovation: Detailed insights into newly introduced and evolving clinical trial services and technology-enabled solutions
- Market Development: Comprehensive information about lucrative markets-the report analyzes the market across varied regions.
- Market Diversification: Exhaustive information about new services, untapped geographies, recent developments, and investments in the clinical trial services market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, service offerings, and competitive positioning of key clinical trial service providers, including Thermo Fisher Scientific Inc. (PPD, Inc.), IQVIA Inc., ICON plc, Laboratory Corporation of America Holdings, Syneos Health, WuXi AppTec, Eurofins Scientific, Parexel International Corporation, Fortrea Inc., Medpace, SGS, Frontage Labs, Pharmaron, Tigermed, and BioAgile, among others. The report analyzes key strategies, service launches, deals, acquisitions, partnerships, agreements, collaborations, expansions, investment and funding activities, brand/service comparative analysis, and vendor valuation and financial metrics in the clinical trial services market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.2.1 INCLUSIONS & EXCLUSIONS
- 1.3 MARKET SCOPE
- 1.3.1 MARKETS COVERED
- 1.3.2 REGIONAL SCOPE
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 GLOBAL CLINICAL TRIAL SERVICES MARKET SNAPSHOT
- 3.2 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET, BY MODALITY AND COUNTRY, 2025
- 3.3 CLINICAL TRIAL SERVICES MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing pipeline complexity and increasing clinical-trial activity in specialty and advanced therapies
- 4.2.1.2 Resilient biopharma R&D investment and broad clinical-development pipeline
- 4.2.1.3 Flexible and scalable service delivery offered by CROs
- 4.2.1.4 Pressure to shorten development timelines and improve clinical R&D productivity
- 4.2.1.5 Growing adoption of FSP, hybrid, and strategic portfolio-based outsourcing models
- 4.2.2 OPPORTUNITIES
- 4.2.2.1 Regulatory modernization and adoption of innovative trial designs
- 4.2.2.2 AI, automation, and advanced data analytics across clinical development
- 4.2.2.3 Patient- and site-centric, decentralized, and hybrid clinical-trial models
- 4.2.3 CHALLENGES
- 4.2.3.1 Patient recruitment, enrollment, and retention constraints
- 4.2.3.2 Shortage of qualified clinical-research talent and specialized domain expertise
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 MARKET TRENDS
- 5.1.1 INTEGRATION OF HEOR AND RWE INTO CLINICAL TRIAL DESIGN
- 5.1.2 INCREASING FOCUS ON IN SILICO TRIALS
- 5.1.3 FSP AND HYBRID OUTSOURCING ARE GAINING STRATEGIC IMPORTANCE VERSUS ONE-SIZE-FITS-ALL FULL-SERVICE OUTSOURCING
- 5.1.4 SUSTAINABILITY AND ESG PRESSURES ARE SHAPING CLINICAL TRIALS
- 5.1.5 SUPPLIER CONSOLIDATION AND STRATEGIC PARTNERSHIPS REDEFINE MARKET
- 5.2 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.3 PRICING ANALYSIS
- 5.3.1 INDICATIVE PRICING RANGE, BY SERVICE TYPE, 2025
- 5.3.2 INDICATIVE PRICING ANALYSIS, BY PHASE, 2025
- 5.3.3 INDICATIVE PRICING ANALYSIS, BY REGION, 2025
- 5.4 VALUE CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.6 INVESTMENT/FUNDING ACTIVITY
- 5.7 KEY CONFERENCES & EVENTS
- 5.8 PORTER'S FIVE FORCES ANALYSIS
- 5.8.1 THREAT OF NEW ENTRANTS
- 5.8.2 THREAT OF SUBSTITUTES
- 5.8.3 BARGAINING POWER OF BUYERS
- 5.8.4 BARGAINING POWER OF SUPPLIERS
- 5.8.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.9 IMPACT OF 2025 TRUMP TARIFF ON CLINICAL TRIAL SERVICES MARKET
- 5.9.1 INTRODUCTION
- 5.9.2 KEY TARIFF RATES
- 5.9.3 PRICE IMPACT ANALYSIS
- 5.9.4 IMPACT ON COUNTRY/REGION
- 5.9.4.1 North America
- 5.9.4.1.1 US
- 5.9.4.2 Europe
- 5.9.4.3 Asia Pacific
- 5.9.4.1 North America
- 5.9.5 IMPACT ON END-USE INDUSTRIES
- 5.9.5.1 Pharmaceutical & biotech companies
- 5.9.5.2 Medical devices companies
- 5.9.5.3 Academic institutes
- 5.10 MACROECONOMIC OUTLOOK
- 5.10.1 INTRODUCTION
- 5.10.2 GDP TRENDS AND FORECAST
- 5.10.3 TRENDS IN GLOBAL CLINICAL TRIAL SERVICES MARKET
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVE N IMPACT, INNOVATIONS AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGIES
- 6.1.1.1 AI-integrated Clinical Trial Management System (CTMS) & Electronic Trial Master File (eTMF) platforms
- 6.1.1.2 Randomization and Trial Supply Management (RTSM)
- 6.1.1.3 Electronic Data Capture (EDC) System
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Digital Biomarkers, Wearables & Electronic Patient-Reported Outcome (EPRO) Tools
- 6.1.2.2 Model-Informed Drug Development (MIDD)
- 6.1.2.3 Data Management and Informatics Technologies
- 6.1.2.4 Real-world evidence (RWE) & real-world data (RWD) platforms
- 6.1.3 ADJACENT TECHNOLOGY
- 6.1.3.1 Clinical trial simulation tools
- 6.1.1 KEY TECHNOLOGIES
- 6.2 IMPACT OF AI/GEN AI ON CLINICAL TRIAL SERVICES MARKET
- 6.2.1 INTRODUCTION
- 6.2.2 MARKET POTENTIAL ACROSS DRUG DEVELOPMENT STAGES
- 6.2.3 KEY COMPANIES IMPLEMENTING AI
- 6.2.4 FUTURE OF GENERATIVE AI IN DRUG DEVELOPMENT ECOSYSTEM
- 6.3 TECHNOLOGY/SERVICE ROADMAP
- 6.4 FUTURE APPLICATIONS
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 REGULATORY FRAMEWORK & CLINICAL TRIAL AUTHORIZATION
- 7.1.3 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 7.3 CERTIFICATIONS, LABELING, & ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS AND BUYING CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 CUSTOMER LANDSCAPE
- 8.3.1 BUDGET ALLOCATION TREND
- 8.3.2 ADOPTION BARRIER & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
9 CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE
- 9.1 INTRODUCTION
- 9.2 CLINICAL TRIAL MANAGEMENT & MONITORING
- 9.2.1 ADOPTION OF ADVANCED TECHNOLOGIES SUCH AS ARTIFICIAL INTELLIGENCE AND RISE OF REMOTE CLINICAL MONITORING TO SUPPORT MARKET GROWTH
- 9.3 LABORATORY SERVICES
- 9.3.1 ANALYTICAL TESTING SERVICES
- 9.3.1.1 Increasing demand for analytical testing for drug development to drive market
- 9.3.2 BIOANALYTICAL TESTING SERVICES
- 9.3.2.1 Rising focus on biologics in advanced therapies to drive market
- 9.3.1 ANALYTICAL TESTING SERVICES
- 9.4 CLINICAL TRIAL DATA MANAGEMENT SERVICES
- 9.4.1 GROWING RELIANCE ON DATA FOR CLINICAL EVALUATIONS BY REGULATORY BODIES TO SUPPORT MARKET GROWTH
- 9.4.2 BIOSTATISTICS
- 9.4.2.1 Integration of real-world data (RWD) into statistical analysis to support market growth
- 9.4.3 OTHER DATA MANAGEMENT SERVICES
- 9.5 CLINICAL TRIAL SUPPLY & LOGISTICS SERVICES
- 9.5.1 COMPLEXITIES ASSOCIATED WITH SUPPLY AND LOGISTICS TO DRIVE MARKET
- 9.6 CONSULTING
- 9.6.1 INCREASING COMPLEXITIES DURING TRIALS TO DRIVE MARKET
- 9.7 PATIENT RECRUITMENT & RETENTION
- 9.7.1 INCREASING REQUIREMENT FOR DECENTRALIZED CLINICAL TRIAL SERVICES TO BOOST MARKET GROWTH
- 9.8 MEDICAL WRITING
- 9.8.1 INCREASED OUTSOURCING OF MEDICAL WRITING SERVICES IN EMERGING ECONOMIES TO DRIVE MARKET
- 9.9 SAFETY & PHARMACOVIGILANCE
- 9.9.1 REGULATORY AND SAFETY MONITORING EXPERTISE OFFERED BY CROS TO SUPPORT MARKET GROWTH
- 9.10 SITE CONTRACTS & PAYMENTS
- 9.10.1 GROWING NEED FOR STREAMLINED SITE CONTRACTING AND PAYMENT MANAGEMENT TO SUPPORT MARKET GROWTH
- 9.11 OTHER SERVICE TYPES
10 CLINICAL TRIAL SERVICES MARKET, BY PHASE
- 10.1 INTRODUCTION
- 10.2 PHASE III
- 10.2.1 HIGH SIGNIFICANCE OF PHASE III TRIALS TO DRIVE DEMAND FOR OUTSOURCING
- 10.3 PHASE II
- 10.3.1 LONG DURATION OF PHASE II STUDIES TO CREATE GROWTH OPPORTUNITIES FOR CROS
- 10.4 PHASE I
- 10.4.1 DECLINING TRIALS TO POSE GROWTH CHALLENGE TO MARKET
- 10.5 PHASE IV
- 10.5.1 SIGNIFICANCE OF PHASE IV TO SUPPORT MARKET GROWTH
11 CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL
- 11.1 INTRODUCTION
- 11.2 FULL-SERVICE OUTSOURCING (FSO) MODEL
- 11.2.1 RISE IN NUMBER OF EMERGING BIOPHARMACEUTICAL COMPANIES TO DRIVE MARKET
- 11.3 FUNCTIONAL SERVICE PROVIDER (FSP) MODEL
- 11.3.1 GROWING ADOPTION OF FSP SERVICES BY LARGE PHARMACEUTICAL COMPANIES TO FUEL MARKET GROWTH
- 11.4 HYBRID MODEL
- 11.4.1 HIGH FLEXIBILITY OFFERED BY HYBRID MODEL TO SUPPORT MARKET GROWTH
12 CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN
- 12.1 INTRODUCTION
- 12.2 INTERVENTIONAL
- 12.2.1 MAJOR ROLE OF INTERVENTIONAL TRIALS IN EVALUATING SAFETY AND EFFICACY OF NEW DRUGS AND DEVICES TO DRIVE MARKET
- 12.3 OBSERVATIONAL
- 12.3.1 INCREASING RELIANCE ON OBSERVATIONAL STUDIES TO EVALUATE EFFICACY OF DRUGS IN REAL-WORLD SCENARIO TO SUPPORT MARKET GROWTH
13 CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA
- 13.1 INTRODUCTION
- 13.2 ONCOLOGY
- 13.2.1 GROWING DISEASE BURDEN AND FOCUS ON DEVELOPING NOVEL MEDICINES FOR CANCER TO DRIVE MARKET
- 13.2.2 BREAST CANCER
- 13.2.2.1 Increasing cases and high spending on treating breast cancer to support growth
- 13.2.3 LUNG CANCER
- 13.2.3.1 Increasing focus on developing drugs against lung cancer to foster growth
- 13.2.4 COLORECTAL CANCER
- 13.2.4.1 Increasing drug discovery and development efforts against colorectal cancer to aid growth
- 13.2.5 PROSTATE CANCER
- 13.2.5.1 Growing clinical pipeline to propel market
- 13.2.6 OTHER CANCER
- 13.3 NEUROLOGY
- 13.3.1 INCREASING R&D INVESTMENTS RELATED TO NEUROLOGICAL DISORDERS TO DRIVE MARKET
- 13.4 RESPIRATORY DISORDERS
- 13.4.1 RISING INCIDENCE OF RESPIRATORY DISORDERS TO SUPPORT MARKET GROWTH
- 13.5 METABOLIC DISORDERS/ENDOCRINOLOGY
- 13.5.1 INCREASING GLOBAL DIABETES POPULATION TO BOOST MARKET GROWTH
- 13.6 CARDIOVASCULAR SYSTEM DISORDERS
- 13.6.1 HIGH FOCUS ON PHARMACEUTICAL R&D ATTRIBUTED TO RISING MORTALITY RATES DUE TO CVD TO DRIVE MARKET
- 13.7 DERMATOLOGY
- 13.7.1 GROWING FOCUS ON DRUG DEVELOPMENT FOR DIFFERENT SKIN CONDITIONS TO SUPPORT MARKET GROWTH
- 13.8 GASTROINTESTINAL DISEASES
- 13.8.1 EXPANSION AND DEVELOPMENT OF GASTROINTESTINAL DRUG PRODUCT LINE TO PROPEL MARKET
- 13.9 IMMUNOLOGICAL DISORDERS
- 13.9.1 GROWING CLINICAL RESEARCH FOR IMMUNOLOGICAL DISORDERS TO FUEL MARKET GROWTH
- 13.10 INFECTIOUS DISEASES
- 13.10.1 RISING OUTBREAKS OF INFECTIOUS DISEASES TO INCREASE DRUG DISCOVERY ACTIVITIES AND DRIVE MARKET
- 13.11 PSYCHIATRY
- 13.11.1 GROWING INCIDENCE OF PSYCHIATRIC DISORDERS TO SUPPORT MARKET GROWTH
- 13.12 OPHTHALMOLOGY
- 13.12.1 RISING NUMBER OF OPHTHALMOLOGY PIPELINE DRUGS TO SUPPORT SEGMENT GROWTH
- 13.13 HEMATOLOGY
- 13.13.1 CONSISTENT DRUG DEVELOPMENT EFFORTS FOR HEMATOLOGICAL DISORDERS TO SUPPORT MARKET GROWTH
- 13.14 GENITOURINARY & WOMEN'S HEALTH
- 13.14.1 RISING PREVALENCE OF CHRONIC DISORDERS IN WOMEN TO PROPEL MARKET
- 13.15 OTHER THERAPEUTIC AREAS
14 CLINICAL TRIAL SERVICES MARKET, BY MODALITY
- 14.1 INTRODUCTION
- 14.2 SMALL MOLECULES
- 14.2.1 STRONG PIPELINE GROWTH AND GROWING INVESTMENTS TO SUPPORT GROWTH
- 14.3 BIOLOGICS
- 14.3.1 GROWING COLLABORATIONS TO DEVELOP NEW BIOLOGICS AND REGULATORY SUPPORT TO PROPEL DEMAND
- 14.4 MONOCLONAL ANTIBODY
- 14.4.1 SURGING DEMAND FOR TARGETED THERAPIES TO DRIVE MARKET
- 14.5 CELL & GENE THERAPY
- 14.5.1 DEVELOPMENT COMPLEXITY AND REGULATORY MOMENTUM TO DRIVE CRO DEMAND
- 14.6 OTHER BIOLOGICS
- 14.7 BIOSIMILARS
- 14.7.1 INCREASING DEMAND FOR COST-EFFECTIVE ALTERNATIVES TO SUPPORT BIOSIMILARS GROWTH, THUS AIDING OUTSOURCING
- 14.8 MEDICAL DEVICES & IVD
- 14.8.1 SPECIALIZED SERVICES OFFERED BY CROS TO DRIVE DEMAND
15 CLINICAL TRIAL SERVICES MARKET, BY END USER
- 15.1 INTRODUCTION
- 15.2 PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES
- 15.2.1 INCREASE IN R&D EXPENDITURE OF PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES TO DRIVE MARKET
- 15.2.2 LARGE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES
- 15.2.2.1 Demand for therapeutic expertise and global reach to aid outsourcing to CROs
- 15.2.3 SMALL & MID-SIZE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES
- 15.2.3.1 Demand driven by limited internal capabilities and rising trial complexity
- 15.3 MEDICAL DEVICE COMPANIES
- 15.3.1 RISING REGULATORY EVIDENCE REQUIREMENTS AND EXPANSION OF INTEGRATED SERVICE PORTFOLIOS BY MEDTECH CROS TO DRIVE MARKET GROWTH
- 15.4 ACADEMIC INSTITUTES
- 15.4.1 EXPANDING CRO-ACADEMIC PARTNERSHIPS AND SITE NETWORKS TO DRIVE MARKET
16 CLINICAL TRIAL SERVICES MARKET, BY REGION
- 16.1 INTRODUCTION
- 16.2 NORTH AMERICA
- 16.2.1 US
- 16.2.1.1 Presence of well-established CROs to drive market
- 16.2.2 CANADA
- 16.2.2.1 Favorable government-led initiatives and rising R&D investments to drive market
- 16.2.1 US
- 16.3 EUROPE
- 16.3.1 GERMANY
- 16.3.1.1 Growing R&D spending and favorable government policies to propel market
- 16.3.2 UK
- 16.3.2.1 Rising collaborations and improved policies to support market
- 16.3.3 FRANCE
- 16.3.3.1 Government-led support for effective drug research to drive market
- 16.3.4 ITALY
- 16.3.4.1 Government-led focus on improving clinical trial regulations to drive market
- 16.3.5 SPAIN
- 16.3.5.1 Rising R&D expenditure to boost market growth
- 16.3.6 REST OF EUROPE
- 16.3.1 GERMANY
- 16.4 ASIA PACIFIC
- 16.4.1 CHINA
- 16.4.1.1 Low manufacturing cost and increased establishment of R&D centers to drive market
- 16.4.2 INDIA
- 16.4.2.1 Cost-efficient and innovation-driven approach to propel market
- 16.4.3 JAPAN
- 16.4.3.1 Slight decline in number of clinical trials to limit market
- 16.4.4 AUSTRALIA
- 16.4.4.1 Favorable tax incentives and cash rebates to pharmaceutical companies to support market
- 16.4.5 SOUTH KOREA
- 16.4.5.1 Favorable government initiatives for drug development to drive market
- 16.4.6 REST OF ASIA PACIFIC
- 16.4.1 CHINA
- 16.5 LATIN AMERICA
- 16.5.1 BRAZIL
- 16.5.1.1 Government-led support through improved policies in pharmaceutical R&D to drive market
- 16.5.2 MEXICO
- 16.5.2.1 Increasing investments in pharma R&D to drive market
- 16.5.3 REST OF LATIN AMERICA
- 16.5.1 BRAZIL
- 16.6 MIDDLE EAST
- 16.6.1 GCC COUNTRIES
- 16.6.1.1 Saudi Arabia
- 16.6.1.1.1 Increase in collaborations to drive market
- 16.6.1.2 UAE
- 16.6.1.2.1 Growing clinical research activities to drive market
- 16.6.1.3 Rest of GCC Countries
- 16.6.1.1 Saudi Arabia
- 16.6.2 REST OF MIDDLE EAST
- 16.6.3 AFRICA
- 16.6.3.1 Expanding pharmaceutical industry to support market growth
- 16.6.1 GCC COUNTRIES
17 COMPETITIVE LANDSCAPE
- 17.1 OVERVIEW
- 17.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2023-2025
- 17.3 REVENUE ANALYSIS, 2023-2025
- 17.3.1 CLINICAL TRIAL SERVICES MARKET
- 17.4 MARKET SHARE ANALYSIS, 2025
- 17.4.1 CLINICAL TRIAL SERVICES MARKET
- 17.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 17.5.1 CLINICAL TRIAL SERVICES MARKET
- 17.5.2 STARS
- 17.5.3 EMERGING LEADERS
- 17.5.4 PERVASIVE PLAYERS
- 17.5.5 PARTICIPANTS
- 17.5.5.1 Company footprint: Key players, 2025
- 17.5.5.1.1 Company footprint
- 17.5.5.2 Region footprint
- 17.5.5.3 Service type footprint
- 17.5.5.4 Phase footprint
- 17.5.5.1 Company footprint: Key players, 2025
- 17.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 17.6.1 CLINICAL TRIAL SERVICES MARKET: STARTUPS/SMES, 2025
- 17.6.2 PROGRESSIVE COMPANIES
- 17.6.3 RESPONSIVE COMPANIES
- 17.6.4 DYNAMIC COMPANIES
- 17.6.5 STARTING BLOCKS
- 17.6.5.1 Competitive benchmarking
- 17.6.5.1.1 Detailed list of key startups/SMES
- 17.6.5.1.2 Competitive benchmarking of startups/SMEs
- 17.6.5.1 Competitive benchmarking
- 17.7 COMPANY VALUATION AND FINANCIAL METRICS
- 17.7.1 CLINICAL TRIAL SERVICES MARKET
- 17.8 BRAND/SERVICE COMPARISON
- 17.9 COMPETITIVE SCENARIO
- 17.9.1 SERVICE LAUNCHES
- 17.9.2 DEALS
- 17.9.3 EXPANSIONS
18 COMPANY PROFILES
- 18.1 KEY PLAYERS
- 18.1.1 IQVIA INC.
- 18.1.1.1 Business overview
- 18.1.1.2 Solutions/Services offered
- 18.1.1.3 Recent developments
- 18.1.1.3.1 Service/Solution launches
- 18.1.1.3.2 Deals
- 18.1.1.4 MnM view
- 18.1.1.4.1 Right to win
- 18.1.1.4.2 Strategic choices
- 18.1.1.4.3 Weaknesses and competitive threats
- 18.1.2 ICON PLC
- 18.1.2.1 Business overview
- 18.1.2.2 Services/Solutions offered
- 18.1.2.3 Recent developments
- 18.1.2.3.1 Service launches
- 18.1.2.3.2 Deals
- 18.1.2.3.3 Expansions
- 18.1.2.4 MnM view
- 18.1.2.4.1 Right to win
- 18.1.2.4.2 Strategic choices
- 18.1.2.4.3 Weaknesses and competitive threats
- 18.1.3 THERMO FISHER SCIENTIFIC INC.
- 18.1.3.1 Business overview
- 18.1.3.2 Services/Solutions offered
- 18.1.3.3 Recent developments
- 18.1.3.3.1 Product/Service launches
- 18.1.3.3.2 Deals
- 18.1.3.3.3 Expansions
- 18.1.3.4 MnM view
- 18.1.3.4.1 Right to win
- 18.1.3.4.2 Strategic choices
- 18.1.3.4.3 Weaknesses and competitive threats
- 18.1.4 FORTREA
- 18.1.4.1 Business overview
- 18.1.4.2 Services/Solutions offered
- 18.1.4.3 Recent developments
- 18.1.4.3.1 Service launches
- 18.1.4.3.2 Deals
- 18.1.4.3.3 Expansions
- 18.1.4.3.4 Other developments
- 18.1.4.4 MnM view
- 18.1.4.4.1 Right to win
- 18.1.4.4.2 Strategic choices
- 18.1.4.4.3 Weaknesses and competitive threats
- 18.1.5 SYNEOS HEALTH
- 18.1.5.1 Business overview
- 18.1.5.2 Services/Solutions offered
- 18.1.5.3 Recent developments
- 18.1.5.3.1 Service launches
- 18.1.5.3.2 Deals
- 18.1.6 LABORATORY CORPORATION OF AMERICA HOLDINGS
- 18.1.6.1 Business overview
- 18.1.6.2 Services/Solutions offered
- 18.1.6.3 Recent developments
- 18.1.6.3.1 Service/ Solution launches
- 18.1.6.3.2 Deals
- 18.1.6.3.3 Expansions
- 18.1.6.4 MnM view
- 18.1.6.4.1 Right to win
- 18.1.6.4.2 Strategic choices
- 18.1.6.4.3 Weaknesses and competitive threats
- 18.1.7 MEDPACE
- 18.1.7.1 Business overview
- 18.1.7.2 Services/Solutions offered
- 18.1.8 WUXI APPTEC
- 18.1.8.1 Business overview
- 18.1.8.2 Services/Solutions offered
- 18.1.8.3 Recent developments
- 18.1.8.3.1 Deals
- 18.1.8.3.2 Expansions
- 18.1.8.4 Other developments
- 18.1.9 FRONTAGE LABS
- 18.1.9.1 Business overview
- 18.1.9.2 Services/Solutions offered
- 18.1.9.3 Recent developments
- 18.1.9.3.1 Deals
- 18.1.10 PHARMARON
- 18.1.10.1 Business overview
- 18.1.10.2 Services/Solutions offered
- 18.1.11 TIGERMED
- 18.1.11.1 Business overview
- 18.1.11.2 Services offered
- 18.1.11.3 Recent developments
- 18.1.11.3.1 Service approvals
- 18.1.11.3.2 Deals
- 18.1.12 SGS SA
- 18.1.12.1 Business overview
- 18.1.12.2 Services/Solutions offered
- 18.1.12.3 Recent developments
- 18.1.12.3.1 Deals
- 18.1.12.3.2 Expansions
- 18.1.13 EUROFINS SCIENTIFIC
- 18.1.13.1 Business overview
- 18.1.13.2 Services/Solutions offered
- 18.1.14 LINICAL
- 18.1.14.1 Business overview
- 18.1.14.2 Services/Solutions offered
- 18.1.14.3 Recent developments
- 18.1.14.4 Expansions
- 18.1.15 PAREXEL INTERNATIONAL CORPORATION
- 18.1.15.1 Business overview
- 18.1.15.2 Services/Solutions offered
- 18.1.15.3 Recent developments
- 18.1.15.3.1 Product & service launches
- 18.1.15.3.2 Deals
- 18.1.15.3.3 Expansions
- 18.1.16 PSI CRO AG
- 18.1.16.1 Business overview
- 18.1.16.2 Services/Solutions offered
- 18.1.16.3 Recent developments
- 18.1.16.3.1 Service launches
- 18.1.16.3.2 Deals
- 18.1.16.3.3 Expansions
- 18.1.17 NOVOTECH
- 18.1.17.1 Business overview
- 18.1.17.2 Services/Solutions offered
- 18.1.17.3 Recent developments
- 18.1.17.3.1 Deals
- 18.1.18 BIOAGILE
- 18.1.18.1 Business overview
- 18.1.18.2 Services/Solutions offered
- 18.1.19 ADVANCED CLINICAL
- 18.1.19.1 Business overview
- 18.1.19.2 Services/Solutions offered
- 18.1.19.3 Recent developments
- 18.1.19.3.1 Deals
- 18.1.20 FIRMA CLINICAL RESEARCH
- 18.1.20.1 Business overview
- 18.1.20.2 Services/Solutions offered
- 18.1.1 IQVIA INC.
- 18.2 OTHER PLAYERS
- 18.2.1 WORLDWIDE CLINICAL TRIALS
- 18.2.2 PROPHARMA
- 18.2.3 ALLUCENT
- 18.2.4 PREMIER RESEARCH
- 18.2.5 CAIDYA
- 18.2.6 ERGOMED GROUP
- 18.2.7 CLARIO
- 18.2.8 PRECISION MEDICINE GROUP, LLC.
- 18.2.9 EPS HOLDINGS, INC.
- 18.2.10 GUIRES INC. (PEPGRA)
- 18.2.11 KCR S.A.
19 RESEARCH METHODOLOGY
- 19.1 RESEARCH APPROACH
- 19.1.1 SECONDARY DATA
- 19.1.1.1 Key sources of secondary data
- 19.1.1.2 Key objectives of secondary research
- 19.1.2 PRIMARY DATA
- 19.1.2.1 Breakdown of primaries
- 19.1.2.2 Key objectives of primary research
- 19.1.1 SECONDARY DATA
- 19.2 MARKET ESTIMATION METHODOLOGY
- 19.2.1 COMPANY REVENUE ANALYSIS (BOTTOM-UP APPROACH)
- 19.2.2 MNM REPOSITORY ANALYSIS AND PRIMARY RESEARCH
- 19.2.3 SEGMENTAL MARKET ASSESSMENT (TOP-DOWN APPROACH)
- 19.3 GROWTH RATE PROJECTIONS
- 19.4 DATA TRIANGULATION
- 19.5 RESEARCH ASSUMPTIONS
- 19.6 RESEARCH LIMITATIONS
- 19.7 RISK ANALYSIS
20 APPENDIX
- 20.1 DISCUSSION GUIDE
- 20.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 20.3 CUSTOMIZATION OPTIONS
- 20.4 RELATED REPORTS
- 20.5 AUTHOR DETAILS


