
|
시장보고서
상품코드
2136429
완두콩 단백질 시장 : 유형별(분리, 농축, 조직형 완두콩 단백질), 용도별(식품 및 음료, 기타), 성질별(기존 제품, 유기농), 가공 방법별(건식, 습식), 지역별 - 세계 예측(-2031년)Pea Protein Market by Type (Isolates, Concentrates, and Textured), Application (Food, Beverages, and Other Applications), Nature (Conventional and Organic), Processing Method (Dry and Wet), and Region - Global Forecast to 2031 |
||||||

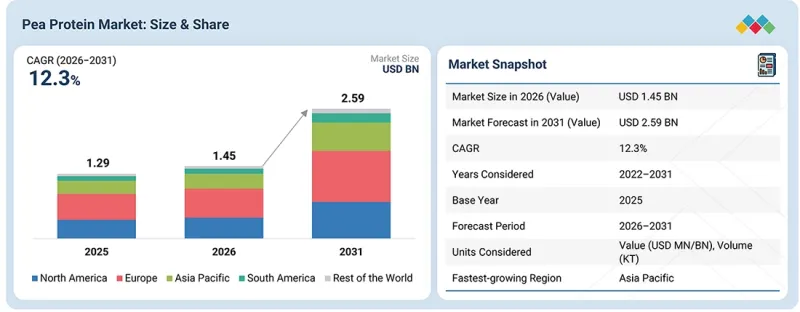
완두콩 단백질 시장 규모는 2026년 14억 5,000만 달러에서 2031년에는 25억 9,000만 달러에 달할 것으로 예측되며, 2026년부터 2031년까지 CAGR은 12.3%가 될 전망입니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2022-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 단위 | 금액(달러)·톤 |
| 부문 | 유형, 용도, 성질, 가공 방법, 지역 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 남미, 기타 지역 |
“유형별로는 분리 완두콩 단백질이 식품·음료 및 반려동물 사료의 폭넓은 용도를 바탕으로 최대 점유율을 차지합니다.”
완두콩 단백질은 안정적인 영양가와 기능성을 갖춘 농축 단백질 원료를 제공할 수 있어 완두콩 단백질 시장을 주도하고 있습니다. 높은 단백질 함량 덕분에 제품의 부피를 크게 늘리지 않고도 단백질 함량을 높이고자 하는 제조업체의 용도에 적합합니다. 또한, 분리 완두콩 단백질은 대체육, 스포츠 영양 식품, 음료, 스낵, 기능성 식품, 반려동물 사료 등 다양한 제품 배합에 적용할 수 있습니다. 게다가 추출 및 가공 기술의 발전으로 제조업체는 기능성과 용도 적합성을 향상시킨 완두콩 단백질을 개발할 수 있게 되었습니다.
“특성별로는 비용 효율성, 입수 용이성, 양산 적합성을 배경으로 기존형 부문이 최대 점유율을 차지하고 있습니다.”
기존형 완두콩 단백질 부문은 높은 비용 효율성, 광범위한 입수 가능성, 안정적인 공급, 대규모 생산 적합성 덕분에 세계 시장을 독점할 것으로 추정됩니다. 기존형 완두콩 단백질은 대체육,스포츠·퍼포먼스용 영양 식품, 음료, 스낵, 기능성 식품 등 대량 생산되는 용도에서 널리 사용되고 있으며, 이러한 분야에서는 제조업체들이 신뢰할 수 있는 원료의 확보 가능성, 안정적인 품질, 비용 효율적인 배합을 요구하고 있습니다. 또한 확립된 생산 및 조달 체계 역시 광범위한 식품·영양 용도에서의 채택을 더욱 뒷받침하고 있습니다.
“용도별로는 다양한 식품 배합에서의 사용 확대를 배경으로, 식품 부문이 완두콩 단백질 시장에서 최대 점유율을 차지합니다.”
식물 유래 단백질 원료가 주류를 이루는 식품 배합에 점점 더 많이 도입됨에 따라, 식품 부문이 완두콩 단백질 시장을 주도하고 있습니다. 완두콩 단백질은 수분 유지력, 유화성, 식감 향상과 같은 기능성을 갖추고 있어, 제조업체는 이를 활용하여 제품의 구조나 영양 프로파일을 개선할 수 있습니다. 대체육, 스낵, 제빵 제품, 과자, 기능성 식품 등 폭넓은 제품에 활용되는 것 외에도, 단백질 강화 및 클린 라벨 배합에 대한 관심이 높아지고 있는 점도 완두콩 단백질의 광범위한 채택과 시장 내 주도적인 위치를 뒷받침하고 있습니다.
“유럽은 확립된 식물성 식품 산업과 견고한 제조 기반을 바탕으로 완두콩 단백질 시장을 주도하고 있습니다.”
유럽은 해당 지역의 확립된 식물성 식품 산업, 원료 제조사의 강력한 입지, 대체 단백질이 주류 식품에 점점 더 많이 도입되고 있다는 점을 바탕으로 시장을 선도하고 있습니다. 첨단 식품 가공 기술의 보급과 식물성 배합에 대한 지속적인 혁신을 통해 제조업체들은 다양한 완두콩 단백질 기반 제품을 개발할 수 있게 되었습니다. 또한, 지속가능한 식품 생산을 지원하는 노력과 유럽 소매 시장 전반에 걸친 식물성 제품의 품목 확대 역시 이 지역의 주도적 지위 확립에 기여하고 있습니다.
본 보고서에서는 전 세계 완두콩 단백질 시장을 조사하여 시장 개요, 시장 성장에 영향을 미치는 다양한 요인에 대한 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추정 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 종합적으로 다루고 있습니다.
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술의 진보, AI의 영향, 특허, 혁신, 향후 응용
제7장 지속가능성과 규제 상황
제8장 고객 상황과 구매 행동
제9장 완두콩 단백질 시장 : 유형별
제10장 완두콩 단백질 시장 : 성질별
제11장 완두콩 단백질 시장 : 가공 방법별
제12장 완두콩 단백질 시장 : 용도별
제13장 완두콩 단백질 시장 : 지역별
제14장 경쟁 구도
제15장 기업 개요
제16장 조사 방법
제17장 인접 시장 및 관련 시장
제18장 부록
KSM 26.10.07The pea protein market is projected to reach USD 2.59 billion by 2031 from USD 1.45 billion in 2026, at a CAGR of 12.3% from 2026 to 2031.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) and Volume (KT) |
| Segments | Type, Application, Nature, Processing Method, and Region |
| Regions covered | North America, Europe, Asia Pacific, South America, and Rest of the World (RoW) |
"By type, the isolates segment dominates the pea protein market, driven by broad applications across food & beverage and pet food applications"
The isolates segment dominates the pea protein market due to its ability to deliver a concentrated protein ingredient with consistent nutritional and functional performance. Its high protein content makes it suitable for applications where manufacturers aim to increase protein levels without substantially increasing product volume. Pea protein isolate is also adaptable to diverse formulations, including meat alternatives, sports nutrition, beverages, snacks, functional foods, and pet foods, while advances in extraction and processing technologies have enabled manufacturers to develop isolates with improved functionality and application suitability.
"By nature, the conventional segment dominates the pea protein market due to cost-effectiveness, availability, and scalable production"
The conventional pea protein segment is estimated to dominate the global market, supported by its cost-effectiveness, wide availability, consistent supply, and suitability for large-scale production. Conventional pea protein is widely used across high-volume applications such as meat substitutes, performance nutrition, beverages, snacks, and functional foods, where manufacturers require reliable ingredient availability, consistent quality, and cost-efficient formulation. Its established production and sourcing practices further support its adoption across a broad range of food and nutrition applications.
"By application, the food segment dominates the pea protein market, driven by increasing use in diverse food formulations"
The food segment dominates the pea protein market due to the increasing incorporation of plant-based protein ingredients into mainstream food formulations. Pea protein offers functional properties such as water binding, emulsification, and texture enhancement, enabling manufacturers to improve the structure and nutritional profile of products. Its use across products such as meat alternatives, snacks, bakery items, confectionery, and functional foods, together with the growing focus on protein enrichment and clean-label formulations, supports its widespread adoption and leading position in the market.
"Europe dominates the pea protein market, supported by an established plant-based food industry and strong manufacturing base"
Europe dominates the pea protein market, supported by the region's established plant-based food industry, strong presence of ingredient manufacturers, and increasing incorporation of alternative proteins into mainstream food products. The availability of advanced food-processing capabilities and ongoing innovation in plant-based formulations enables manufacturers to develop a broad range of pea protein-based products. In addition, supportive initiatives for sustainable food production and the expansion of plant-based product offerings across European retail markets are contributing to the region's leading position.
In-depth interviews have been conducted with chief executive officers (CEOs), directors, and other executives from various key organizations operating in the pea protein market.
- By Company Type: Tier 1 - 40%, Tier 2 - 20%, and Tier 3 - 40%
- By Designation: CXOs - 26%, Managers - 30%, Executives - 44%
- By Region: North America - 20%, Europe - 20%, Asia Pacific - 40%, South America - 10%, and Rest of the World -10%
Prominent companies in the market include Roquette Freres (France), ADM (US), Ingredion (US), Kerry Group plc (Ireland), Glanbia plc (Ireland), Cargill, Incorporated (US), International Flavors & Fragrances Inc. (US), PURIS (US), Emsland Group (Germany), Yantai Shuangta Food Co., Ltd. (China), Burcon (Canada), Axiom Foods, Inc. (US), Shandong Jianyuan Group (China), ET-Chem (China), AGT Food and Ingredients Inc. (Canada), and other players.
Research Coverage
This research report categorizes the pea protein market by type (isolates, concentrates, and textured), application (food, beverages, and other applications), nature (conventional and organic), processing method (wet processing and dry processing), and region (North America, Europe, Asia Pacific, South America, and Rest of the World).
The report's scope encompasses detailed information on the major factors, including drivers, restraints, challenges, and opportunities, which influence the growth of the pea protein industry. A thorough analysis of the key industry players has been done to provide insights into their business, services, key strategies, contracts, partnerships, agreements, product launches, mergers & acquisitions, and recent developments associated with the pea protein market. This report provides a competitive analysis of emerging startups in the pea protein market ecosystem. Furthermore, the study covers industry-specific trends, including technology analysis, ecosystem & market mapping, and patent & regulatory landscape, among others.
Reasons to Buy This Report
The report provides market leaders/new entrants with information on the closest approximations of revenue numbers for the overall pea protein and its subsegments. It will help stakeholders understand the competitive landscape and gain more insights to better position their businesses and plan suitable go-to-market strategies. The report also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of key drivers (Growing consumer interest in plant-based diets and popularity of plant-based products), restraints (Volatility in raw material supply and prices), opportunities (Expansion of the smart protein and plant-based food ecosystem), and challenges (Presence of anti-nutritional factors in peas)
- Product Development/Innovation: Detailed insights into research & development activities and new product launches in the pea protein market
- Market Development: Comprehensive information about lucrative market analysis of pea protein across varied regions
- Market Diversification: Exhaustive information about new product sources, untapped geographies, recent developments, and investments in the pea protein market
- Competitive Assessment: In depth assessment of market shares, growth strategies, product offerings, brand/product comparison, and product footprints of leading players such as Roquette Freres (France), ADM (US), Ingredion (US), Kerry Group plc (Ireland), Glanbia plc (Ireland), Cargill, Incorporated (US), International Flavors & Fragrances Inc. (US), PURIS (US), Emsland Group (Germany), Yantai Shuangta Food Co., Ltd. (China), Burcon (Canada), Axiom Foods, Inc (US), Shandong Jianyuan group (China), ET-Chem (China), AGT Food and Ingredients Inc. (Canada), and other players in the pea protein market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 UNIT CONSIDERED
- 1.4.1 CURRENCY CONSIDERED
- 1.4.2 UNITS CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN PEA PROTEIN MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN PEA PROTEIN MARKET
- 3.2 PEA PROTEIN MARKET, BY TYPE AND REGION
- 3.3 PEA PROTEIN MARKET, BY TOP 3 TYPES
- 3.4 PEA PROTEIN MARKET, BY NATURE
- 3.5 PEA PROTEIN MARKET, BY APPLICATION
- 3.6 PEA PROTEIN MARKET, BY PROCESSING METHOD
- 3.7 PEA PROTEIN MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing consumer interest in plant-based diets and popularity of plant-based products
- 4.2.1.2 Rising demand for sustainable protein sources
- 4.2.1.3 Growing consumer awareness about nutritional benefits offered by pea and pea-based products
- 4.2.1.4 Increasing demand for clean-label and allergen-conscious food products
- 4.2.2 RESTRAINTS
- 4.2.2.1 Volatility in raw material supply and prices
- 4.2.2.2 Limited solubility and functional performance
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expansion of smart protein and plant-based food ecosystem
- 4.2.3.2 Lower allergenicity and allergen-labeling advantages compared with other plant-based proteins
- 4.2.3.3 Advancements in texture properties that support adoption in baking and meat processing
- 4.2.3.4 Rise in demand from pet food industry
- 4.2.3.5 Advancements in sustainable and cost-efficient pea protein processing
- 4.2.4 CHALLENGES
- 4.2.4.1 Presence of anti-nutritional factors in peas
- 4.2.4.2 Undesirable taste and sensory characteristics
- 4.2.4.3 Presence of alternative plant proteins
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN PEA PROTEIN MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 INTENSITY OF COMPETITIVE RIVALRY
- 5.1.2 BARGAINING POWER OF SUPPLIERS
- 5.1.3 BARGAINING POWER OF BUYERS
- 5.1.4 THREAT OF SUBSTITUTES
- 5.1.5 THREAT OF NEW ENTRANTS
- 5.2 MACROECONOMICS OUTLOOK
- 5.2.1 INTRODUCTION
- 5.3 VALUE CHAIN ANALYSIS
- 5.3.1 RESEARCH & PRODUCT DEVELOPMENT
- 5.3.2 RAW MATERIAL SOURCING & INGREDIENT DEVELOPMENT
- 5.3.3 EXTRACTION, PRODUCTION, & QUALITY ASSURANCE
- 5.3.4 DISTRIBUTION & SUPPLY CHAIN MANAGEMENT
- 5.3.5 END-USE APPLICATIONS & COMMERCIALIZATION
- 5.4 ECOSYSTEM ANALYSIS
- 5.4.1 DEMAND SIDE
- 5.4.2 SUPPLY SIDE
- 5.5 PRICING ANALYSIS
- 5.5.1 INTRODUCTION
- 5.5.2 AVERAGE SELLING PRICE OF PEA PROTEIN, BY PRODUCT TYPE
- 5.5.3 AVERAGE SELLING PRICE (ASP) TREND, BY REGION, 2022-2025 (USD/TONS)
- 5.5.4 INDICATIVE AVERAGE SELLING PRICE (ASP) TREND, BY TYPE, 2022-2025 (USD/TONS)
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT ANALYSIS: PEA PROTEIN MARKET
- 5.6.2 EXPORT ANALYSIS: PEA PROTEIN MARKET
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 INGREDION - PEA PROTEIN FOR NUTRITIONAL BEVERAGES
- 5.10.2 ROQUETTE - NUTRALYS PEA PROTEIN FOR HIGH-PROTEIN AND PLANT-BASED FORMULATIONS
- 5.10.3 COSUCRA - PISANE PEA PROTEIN FOR PROTEIN-FORTIFIED FOODS
- 5.11 IMPACT OF 2025 US TARIFF - PEA PROTEIN MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 PRICE IMPACT ANALYSIS
- 5.11.3 IMPACT ON COUNTRIES/REGIONS
- 5.11.4 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGY ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGIES
- 6.1.1.1 Wet fractionation
- 6.1.1.2 Dry fractionation
- 6.1.1.3 Alkaline extraction-isoelectric precipitation
- 6.1.1.4 Ultrafiltration (UF) processing
- 6.1.2 COMPLEMENTARY ANALYSIS
- 6.1.2.1 Dehulling
- 6.1.2.2 Spray drying
- 6.1.2.3 High-pressure homogenization
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 Fermentation
- 6.1.3.2 Extrusion / High-moisture extrusion
- 6.1.3.3 Protein structure modification
- 6.1.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.1.4.1 Short-term | Advanced refining & sustainable ingredient development
- 6.1.4.2 Mid-term | Advanced fractionation & functional ingredient development
- 6.1.4.3 Long-term | Biotechnology & next-generation pea protein innovation
- 6.1.1 KEY TECHNOLOGIES
- 6.2 PATENT ANALYSIS
- 6.3 FUTURE APPLICATIONS
- 6.3.1 FUTURE APPLICATIONS OF PEA PROTEIN IN NEXT-GENERATION PLANT-BASED BEVERAGES
- 6.3.2 ADVANCED PROTEIN TEXTURIZATION AND EXTRUSION TECHNOLOGY: SHAPING THE FUTURE OF THE PEA PROTEIN MARKET
- 6.3.3 PRECISION FORMULATION AND BLENDING TECHNOLOGY: SHAPING THE FUTURE OF PEA PROTEIN APPLICATIONS
- 6.4 IMPACT OF GENERATIVE AI ON PEA PROTEIN MARKET
- 6.4.1 INTRODUCTION
- 6.4.2 TOP USE CASES AND MARKET POTENTIAL
- 6.4.3 BEST PRACTICES IN PEA PROTEIN INDUSTRY
- 6.4.4 CASE STUDIES OF AI IMPLEMENTATION IN PEA PROTEIN MARKET
- 6.4.5 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.4.6 CLIENTS' READINESS TO ADOPT GENERATIVE AI FOR PEA PROTEIN PRODUCTION
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.1.2.1 Industry standards in pea protein market
- 7.1.3 LABELING REQUIREMENTS AND CLAIMS
- 7.1.4 ANTICIPATED REGULATORY CHANGES IN NEXT 5-10 YEARS
- 7.1.4.1 Enhanced ingredient traceability and supply chain transparency
- 7.1.4.2 Greater global harmonization of plant protein regulations
- 7.1.4.3 Stricter sustainability and responsible sourcing requirements
- 7.1.4.4 Digital traceability, AI-enabled quality monitoring, and compliance automation
- 7.1.4.5 Higher safety and purity standards for plant-based protein ingredients
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 SUSTAINABLE SOURCING
- 7.2.2 CARBON FOOTPRINT REDUCTION INITIATIVES
- 7.2.3 CIRCULAR ECONOMY APPROACHES
- 7.3 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS APPLICATION INDUSTRIES ACROSS SUPPLY CHAIN
- 8.5 MARKET PROFITABILITY
- 8.6 REVENUE POTENTIAL
- 8.6.1 COST DYNAMICS
- 8.6.2 MARGIN OPPORTUNITIES, BY TOP APPLICATIONS
9 PEA PROTEIN MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 ISOLATES
- 9.2.1 GROWING INNOVATION FOR HIGH-QUALITY PROTEIN ISOLATES TO DRIVE SEGMENT
- 9.3 CONCENTRATES
- 9.3.1 WIDE APPLICATION IN SNACKS AND BAKERY ITEMS TO BOOST DEMAND
- 9.4 TEXTURED
- 9.4.1 NUTRITIONAL BENEFITS AND FUNCTIONAL ATTRIBUTES TO DRIVE DEMAND
10 PEA PROTEIN MARKET, BY NATURE
- 10.1 INTRODUCTION
- 10.2 CONVENTIONAL
- 10.3 ORGANIC
11 PEA PROTEIN MARKET, BY PROCESSING METHOD
- 11.1 INTRODUCTION
- 11.2 WET PROCESSING
- 11.2.1 SUPERIOR FUNCTIONALITY AND PURITY
- 11.3 DRY PROCESSING
- 11.3.1 INNOVATION IN DIVERSE FOOD SECTORS
12 PEA PROTEIN MARKET, BY APPLICATION
- 12.1 INTRODUCTION
- 12.2 FOOD
- 12.2.1 MEAT SUBSTITUTES
- 12.2.1.1 Global trends of plant-based meats and veganism to drive segment
- 12.2.2 PERFORMANCE NUTRITION
- 12.2.2.1 Increasing cases of lactose intolerance and adoption in supplements to drive adoption
- 12.2.3 FUNCTIONAL FOODS
- 12.2.3.1 Growing awareness about functional benefits of pea protein to support segment growth
- 12.2.4 SNACKS
- 12.2.4.1 Spike in demand for healthy snacking alternatives to drive segment
- 12.2.5 BAKERY PRODUCTS
- 12.2.5.1 Demand for healthy alternatives in baking applications to drive segment
- 12.2.6 CONFECTIONERIES
- 12.2.6.1 Consumer demand for healthier confectionery products to drive segment
- 12.2.7 OTHER FOOD APPLICATIONS
- 12.2.1 MEAT SUBSTITUTES
- 12.3 BEVERAGES
- 12.3.1 EASY SOLUBILITY AND ADOPTION IN PLANT-BASED BEVERAGES TO SUPPORT SEGMENT GROWTH
- 12.4 OTHER APPLICATIONS
13 PEA PROTEIN MARKET, REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 US
- 13.2.1.1 Rising demand for plant-based protein and expansion of foodservice applications to drive market
- 13.2.2 CANADA
- 13.2.2.1 Expanding pea cultivation and investments in protein processing to drive market
- 13.2.3 MEXICO
- 13.2.3.1 Growing consumer interest in plant-based foods and dairy alternatives to drive market
- 13.2.1 US
- 13.3 EUROPE
- 13.3.1 GERMANY
- 13.3.1.1 Rising health and sustainability awareness and demand for plant-based alternatives to drive market
- 13.3.2 FRANCE
- 13.3.2.1 Strong pea production and growing investments in plant-based protein infrastructure to drive market
- 13.3.3 UK
- 13.3.3.1 Expanding applications of pea protein and growing demand for plant-based alternatives to drive market
- 13.3.4 ITALY
- 13.3.4.1 Strong competition from conventional protein sources to drive demand for pea protein
- 13.3.5 SPAIN
- 13.3.5.1 Strong agricultural output and changing consumer preferences to drive market
- 13.3.6 REST OF EUROPE
- 13.3.1 GERMANY
- 13.4 ASIA PACIFIC
- 13.4.1 CHINA
- 13.4.1.1 Rising demand for healthy and plant-based protein foods to drive market
- 13.4.2 JAPAN
- 13.4.2.1 Aging population and protein supply diversification to drive market
- 13.4.3 AUSTRALIA & NEW ZEALAND
- 13.4.3.1 Growing demand for plant-based foods and expansion of domestic protein production to drive market
- 13.4.4 INDIA
- 13.4.4.1 Growth of startups in plant-based food products segment to boost market
- 13.4.5 REST OF ASIA PACIFIC
- 13.4.1 CHINA
- 13.5 SOUTH AMERICA
- 13.5.1 BRAZIL
- 13.5.1.1 Rising demand for plant-based alternatives and sports nutrition to drive market
- 13.5.2 ARGENTINA
- 13.5.2.1 Expanding pea production and growing demand for plant-based meat alternatives to drive market
- 13.5.3 REST OF SOUTH AMERICA
- 13.5.1 BRAZIL
- 13.6 REST OF THE WORLD
- 13.6.1 AFRICA
- 13.6.1.1 Growing pea production and rising demand for nutritionally enhanced plant-based foods to drive market
- 13.6.2 MIDDLE EAST
- 13.6.2.1 Rising demand for sustainable plant-based alternatives and growing local production to drive market
- 13.6.1 AFRICA
14 COMPETITIVE LANDSCAPE
- 14.1 OVERVIEW
- 14.2 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2023-2025
- 14.3 REVENUE ANALYSIS, 2023-2025
- 14.4 MARKET SHARE ANALYSIS, 2025
- 14.4.1 ROQUETTE FRERES
- 14.4.2 ADM
- 14.4.3 INGREDION
- 14.4.4 GLANBIA PLC
- 14.4.5 CARGILL, INCORPORATED
- 14.5 BRAND/PRODUCT COMPARISON
- 14.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 14.6.1 STARS
- 14.6.2 EMERGING LEADERS
- 14.6.3 PERVASIVE PLAYERS
- 14.6.4 PARTICIPANTS
- 14.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 14.6.5.1 Company footprint
- 14.6.5.2 Region footprint
- 14.6.5.3 Type footprint
- 14.6.5.4 Application footprint
- 14.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 14.7.1 PROGRESSIVE COMPANIES
- 14.7.2 RESPONSIVE COMPANIES
- 14.7.3 DYNAMIC COMPANIES
- 14.7.4 STARTING BLOCKS
- 14.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 14.7.5.1 Detailed list of key startups/SMEs
- 14.7.5.2 Competitive benchmarking of key startups/SMEs
- 14.8 COMPANY VALUATION AND FINANCIAL METRICS
- 14.9 COMPETITIVE SCENARIO
- 14.9.1 PRODUCT LAUNCHES
- 14.9.2 DEALS
- 14.10 EXPANSIONS
15 COMPANY PROFILES
- 15.1 KEY PLAYERS
- 15.1.1 ROQUETTE FRERES
- 15.1.1.1 Business overview
- 15.1.1.2 Products/Solutions/Services offered
- 15.1.1.3 Recent developments
- 15.1.1.3.1 Product launches
- 15.1.1.3.2 Expansions
- 15.1.1.4 MnM view
- 15.1.1.4.1 Right to win
- 15.1.1.4.2 Strategic choices
- 15.1.1.4.3 Weaknesses and competitive threats
- 15.1.2 ADM
- 15.1.2.1 Business overview
- 15.1.2.2 Products/Solutions/Services offered
- 15.1.2.3 Recent developments
- 15.1.2.3.1 Product launches
- 15.1.2.3.2 Deals
- 15.1.2.3.3 Expansions
- 15.1.2.4 MnM view
- 15.1.2.4.1 Right to win
- 15.1.2.4.2 Strategic choices
- 15.1.2.4.3 Weakness/competitive threats
- 15.1.3 INGREDION
- 15.1.3.1 Business overview
- 15.1.3.2 Products/Solutions/Services offered
- 15.1.3.3 Recent developments
- 15.1.3.3.1 Product launches
- 15.1.3.3.2 Deals
- 15.1.3.4 MnM view
- 15.1.3.4.1 Right to win
- 15.1.3.4.2 Strategic choices
- 15.1.3.4.3 Weaknesses and competitive threats
- 15.1.4 KERRY GROUP PLC
- 15.1.4.1 Business overview
- 15.1.4.2 Products/Solutions/Services offered
- 15.1.4.3 Recent developments
- 15.1.4.3.1 Deals
- 15.1.4.3.2 Expansions
- 15.1.4.4 MnM view
- 15.1.4.4.1 Right to win
- 15.1.4.4.2 Strategic choices
- 15.1.4.4.3 Weakness/competitive threats
- 15.1.5 GLANBIA PLC
- 15.1.5.1 Business overview
- 15.1.5.2 Products/Solutions/Services offered
- 15.1.5.3 Recent developments
- 15.1.5.3.1 Product launches
- 15.1.5.4 MnM view
- 15.1.5.4.1 Right to win
- 15.1.5.4.2 Strategic choices
- 15.1.5.4.3 Weaknesses and competitive threats
- 15.1.6 CARGILL, INCORPORATED
- 15.1.6.1 Business overview
- 15.1.6.2 Products/Solutions/Services offered
- 15.1.6.3 Recent developments
- 15.1.6.3.1 Expansions
- 15.1.6.4 MnM view
- 15.1.7 INTERNATIONAL FLAVORS & FRAGRANCES INC.
- 15.1.7.1 Business overview
- 15.1.7.2 Products/Solutions/Services offered
- 15.1.7.3 Recent developments
- 15.1.7.3.1 Deals
- 15.1.7.3.2 Expansions
- 15.1.7.4 MnM view
- 15.1.8 PURIS
- 15.1.8.1 Business overview
- 15.1.8.2 Products/Solutions/Services offered
- 15.1.8.3 Recent developments
- 15.1.8.3.1 Deals
- 15.1.8.4 MnM view
- 15.1.9 EMSLAND GROUP
- 15.1.9.1 Business overview
- 15.1.9.2 Products/Solutions/Services offered
- 15.1.9.3 Recent developments
- 15.1.9.3.1 Deals
- 15.1.9.3.2 Expansions
- 15.1.9.4 MnM view
- 15.1.10 YANTAI SHUANGTA FOODS CO., LTD.
- 15.1.10.1 Business overview
- 15.1.10.2 Products/Solutions/Services offered
- 15.1.10.3 MnM view
- 15.1.11 BURCON
- 15.1.11.1 Business overview
- 15.1.11.2 Products/Solutions/Services offered
- 15.1.11.3 Recent developments
- 15.1.11.3.1 Product launches
- 15.1.11.3.2 Deals
- 15.1.11.3.3 Expansions
- 15.1.11.4 MnM view
- 15.1.12 AXIOM FOODS INC.
- 15.1.12.1 Business overview
- 15.1.12.2 Products/Solutions/Services offered
- 15.1.12.3 Recent developments
- 15.1.12.3.1 Deals
- 15.1.12.4 MnM view
- 15.1.13 SHANDONG JIANYUAN GROUP
- 15.1.13.1 Business overview
- 15.1.13.2 Products/Solutions/Services offered
- 15.1.13.3 Recent developments
- 15.1.13.4 MnM view
- 15.1.14 ETCHEM
- 15.1.14.1 Business overview
- 15.1.14.2 Products/Solutions/Services offered
- 15.1.14.3 Recent developments
- 15.1.14.4 MnM view
- 15.1.15 AGT FOOD AND INGREDIENTS
- 15.1.15.1 Business overview
- 15.1.15.2 Products/Solutions/Services offered
- 15.1.15.3 MnM view
- 15.1.1 ROQUETTE FRERES
- 15.2 OTHER PLAYERS
- 15.2.1 THE GREEN LABS, LLC
- 15.2.1.1 Business overview
- 15.2.1.2 Products/Solutions/Services offered
- 15.2.1.3 MnM view
- 15.2.2 COSUCRA
- 15.2.2.1 Business overview
- 15.2.2.2 Products/Solutions/Services offered
- 15.2.2.3 MnM view
- 15.2.3 NUTRIPEA
- 15.2.3.1 Business overview
- 15.2.3.2 Products/Solutions/Services offered
- 15.2.3.3 MnM view
- 15.2.4 SOTEXPRO
- 15.2.4.1 Business overview
- 15.2.4.2 Products/Solutions/Services offered
- 15.2.4.3 MnM view
- 15.2.5 NATURZ ORGANICS
- 15.2.5.1 Business overview
- 15.2.5.2 Products/Solutions/Services offered
- 15.2.5.3 MnM view
- 15.2.1 THE GREEN LABS, LLC
- 15.3 OTHER KEY PLAYERS
- 15.3.1 FENCHEM INC.
- 15.3.2 VISGRANA
- 15.3.3 AGRO SOLVENT PRODUCTS PVT. LTD.
- 15.3.4 ALL ORGANIC TREASURES GMBH
- 15.3.5 STDM FOOD & BEVERAGES PRIVATE LIMITED
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.1.1 Key data from secondary sources
- 16.1.2 PRIMARY DATA
- 16.1.2.1 Key data from primary sources
- 16.1.2.2 Breakdown of primary profiles
- 16.1.2.3 Key insights from industry experts
- 16.1.1 SECONDARY DATA
- 16.2 MARKET SIZE ESTIMATION
- 16.2.1 TOP-DOWN APPROACH
- 16.2.2 SUPPLY-SIDE ANALYSIS
- 16.2.3 BOTTOM-UP APPROACH (DEMAND SIDE)
- 16.3 DATA TRIANGULATION AND MARKET BREAKUP
- 16.4 RESEARCH ASSUMPTIONS
- 16.5 RESEARCH LIMITATIONS AND RISK ASSESSMENT
17 ADJACENT AND RELATED MARKETS
- 17.1 INTRODUCTION
- 17.2 ADJACENT MARKET STUDY LIMITATIONS
- 17.3 PLANT-BASED PROTEINS MARKET
- 17.3.1 MARKET DEFINITION
- 17.3.2 MARKET OVERVIEW
- 17.3.3 PLANT-BASED PROTEINS MARKET, BY NATURE
- 17.4 PEA PROCESSED INGREDIENTS MARKET
- 17.4.1 MARKET DEFINITION
- 17.4.2 MARKET OVERVIEW
- 17.4.3 PEA PROCESSED INGREDIENTS MARKET, BY SOURCE
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.4 RELATED REPORTS


