

|
시장보고서
상품코드
2138092
유세포 분석 시장 : 유형별, 기술별, 검출 방법별, 용도별, 최종사용자별, 지역별 - 세계 예측(-2034년)Flow Cytometry Market by Technology (Cell, Bead-based), Product [Cell Analyzer, Sorter, Antibodies, Assays & Kits (Apoptosis), Software], Service, Detection (Spectral), Application (Clinical, Research), End User, Competition - Global Forecast to 2034 |
||||||

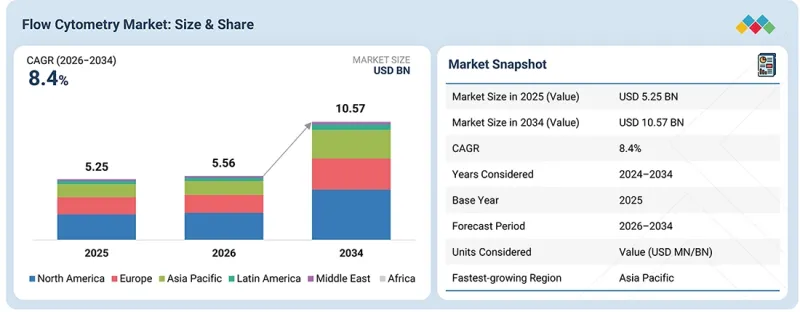
유세포 분석 시장 규모는 2026년 55억 6,000만 달러에서 2034년까지 105억 7,000만 달러에 달할 것으로 예측되며, 예측 기간 동안 CAGR은 8.4%가 될 전망입니다.
면역학, 종양학, 혈액학, 신약 개발, 세포·유전자 치료 및 임상 진단 분야에서 유세포 분석법의 활용이 확대됨에 따라, 해당 시장은 예측 기간 동안 꾸준한 성장을 이룰 것으로 예상됩니다. 기존 유세포 분석법, 스펙트럼 유세포 분석법, 이미징/하이브리드 유세포 분석법, 비드 기반 유세포 분석법 등의 기술을 통해 세포의 표현형, 생존율, 세포 사멸, 세포 주기, 세포 내 단백질, 사이토카인 및 기타 기능적 특성에 대한 상세한 분석이 가능해집니다. 이러한 기술은 암 진단, 자가면역 질환 평가, 줄기세포 연구, 체외 독성 시험, 세포 선별, 백신 제조, 세포·유전자 치료(CGT) 제조, 기타 생물학적 제제 제조 등 폭넓은 용도를 뒷받침하고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2034년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2034년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 유형별, 기술별, 검출 방법별, 용도별, 최종사용자별, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동, 아프리카 |
고성능 분석 장비, 스펙트럼 시스템, 복합 항체-염료 복합체, 멀티플렉스 분석법 및 자동 데이터 분석의 활용 확대에 힘입어 제약, 생명공학, 학술, 임상, CRO/CDMO 각 분야에서의 도입이 더욱 촉진되고 있습니다. 또한, 항체, 분석법 및 키트, 대조군, 교정 시약, 시스 용액, 기타 소모품에 대한 지속적인 수요가 시장의 지속적인 성장을 뒷받침하고 있습니다. 그러나 시장은 여전히 첨단 장비의 높은 비용, 다색 패널 설계의 복잡성, 숙련된 운영자의 필요성, 시약의 표준화, 그리고 고차원 유세포 분석 데이터의 해석과 같은 과제에 직면해 있습니다.
“비드 기반 유세포 분석 분야는 예측 기간 동안 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다.”
비드 기반 유세포 분석 부문은 제한된 검체량에서 여러 분석 대상 물질을 동시에 검출 및 정량하기 위한 다중 분석법의 채택이 증가하고 있어 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예측됩니다. 비드 기반 플랫폼은 사이토카인 프로파일링, 바이오마커 분석, 면역 측정, 신약 개발 연구, 특히 고처리량 다중 검사가 필요한 용도에서 점점 더 널리 활용되고 있습니다. 제약, 생명공학 및 연구 기관에서 효율적이고 확장성이 뛰어나며 다중 항목 분석이 가능한 분석 워크플로우에 대한 수요가 높아지고 있는 것이 이 부문의 성장을 견인하고 있습니다.
“시약 및 소모품 부문은 시장에서 가장 큰 점유율을 차지하고 있습니다.”
시약·소모품 부문은 유세포 분석 시장에서 가장 큰 점유율을 차지하고 있습니다. 이는 주로 일상적인 유세포 분석 워크플로우에서 항체, 항체-염료 복합체, 분석법 및 키트, 완충액, 대조군,교정 시약, 시스 용액, 기타 소모품이 지속적으로 필요하기 때문입니다. 이러한 제품들은 면역 표현형 분석, 사이토카인 검출, 세포 사멸 및 세포 생존율 분석, 다중 분석, 기타 세포 연구에 널리 사용되고 있습니다. 학술, 임상, 제약, 생명공학 및 CRO/CDMO 연구소에서 이러한 제품이 빈번하게 사용되고 있다는 점이 해당 부문 시장의 선도적 지위를 뒷받침하고 있습니다.
“예측 기간 동안 미국은 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다.”
미국은 주요 유세포 분석기 제조사와 제약·생명공학 기업의 강력한 입지, 선진적인 연구 인프라, 그리고 연구 및 임상 현장에서의 첨단 세포 분석 기술 보급률이 높기 때문에 유세포 분석 시장에서 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다. 종양학, 면역학, 혈액학, 신약 개발, 세포·유전자 치료 및 임상 진단 분야에서 유세포 분석의 활용 확대가 시장 성장을 주도하고 있습니다. 고매개변수 분석 장비, 스펙트럼 유세포 분석 시스템, 세포 선별기, 항체-염료 접합체, 멀티플렉스 분석법 및 첨단 데이터 분석 솔루션은 제약·바이오기술 기업, 학술·연구 기관, 병원·임상 검사실, CRO 및 CDMO에서 점점 더 널리 활용되고 있습니다.
BD(미국), Danaher Corporation(미국), Thermo Fisher Scientific Inc.(미국), Agilent Technologies, Inc.(미국), Bio-Rad Laboratories, Inc.(미국), Sony Corporation(일본), Miltenyi Biotec(독일), Enzo Biochem Inc.(미국),Sysmex Corporation(일본), Cytek Biosciences(미국), BIOMERIEUX(프랑스), Cytonome/ST LLC(미국), Sartorius AG(독일), Union Biometrica, Inc.(미국), Takara Bio Inc.(일본), Revvity(미국),Charles River Laboratories(미국), The Jackson Laboratory(미국), Apogee Flow Systems Ltd.(영국), Stratedigm, Inc.(미국), Nova Biomedical(미국), On-chip Biotechnologies Corporation(일본), Precision Cell Systems(미국), CytoBuoy(네덜란드), CUSABIO TECHNOLOGY LLC(미국), De Novo Software(미국), Altasciences(캐나다), RayBiotech, Inc.(미국), 및 KCAS Bio(미국)는 유세포 분석 관련 제품 및 서비스를 제공하는 주요 기업 중 일부입니다.
조사 범위
본 조사 보고서에서는 유세포 분석 시장을 유형별, 기술별, 검출 방식별, 용도별, 최종사용자별, 그리고 지역별로 조사하고 있습니다.
본 보고서의 범위에는 유세포 분석 시장의 성장에 영향을 미치는 주요 요인(촉진요인, 제약요인, 과제 및 기회 등)에 대한 상세한 정보가 포함되어 있습니다. 주요 업계 플레이어에 대한 종합적인 분석을 통해 각 기업의 사업 개요, 제품 포트폴리오, 주요 전략, 신제품 출시, 인수합병 및 유세포 분석 시장의 최근 동향에 대한 인사이트를 제공합니다. 또한, 본 보고서에는 유세포 분석 업계 생태계에서 두각을 나타내고 있는 스타트업 기업에 대한 경쟁 분석도 포함되어 있습니다.
본 보고서를 구매할 때의 주요 이점
본 보고서는 시장 전체 및 그 하위 부문의 매출 예측을 제공함으로써 시장을 선도하는 기업과 신규 진입 기업을 지원합니다. 또한 이해관계자가 경쟁 구도를 더 깊이 이해하고, 자사의 비즈니스를 효과적으로 포지셔닝하며, 적절한 시장 진입 전략을 수립하는 데 필요한 인사이트를 얻는 데에도 도움이 됩니다. 본 보고서를 통해 이해관계자는 시장 동향을 파악하고, 주요 시장 촉진요인, 억제요인, 기회 및 과제에 대한 인사이트를 얻을 수 있습니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다:
- 주요 촉진요인(종양학 연구 및 진단 분야에서 유세포 분석법의 채택 확대, 다중 매개변수 세포 분석을 위한 고매개변수 스펙트럼 유세포 분석법에 대한 수요 증가, 세포 및 유전자 치료의 개발 및 제조 분야에서 유세포 분석법의 응용 확대),제약요인(고성능 유세포 분석기의 높은 비용), 기회(임상 진단 및 바이오의약품 품질 관리 분야에서 유세포 분석법 채택 확대, 고처리량 및 복잡한 데이터 분석을 위한 자동화·AI 탑재형 유세포 분석기에 대한 수요 증가), 그리고 시장 성장에 영향을 미치는 과제(시약 개발과 관련된 복잡성)
- 제품 개발/혁신 : 유세포 분석 시장의 신제품 출시 및 혁신에 대한 상세한 분석
- 시장 개발 : 수익성이 높은 시장에 대한 종합적인 정보 및 각 지역별 시장 분석
- 시장 다각화 : 유세포 분석 시장의 신제품, 미개척 지역, 최근 동향 및 투자에 대한 종합적인 정보
- 경쟁 분석 : 주요 기업 - BD(미국), Danaher Corporation(미국), Thermo Fisher Scientific Inc.(미국), Agilent Technologies, Inc.(미국), Bio-Rad Laboratories, Inc.(미국),Sony Corporation(일본), Miltenyi Biotec(독일), Enzo Biochem Inc.(미국), Sysmex Corporation(일본), Cytek Biosciences(미국), Revvity(미국) 등, 유세포 분석 시장의 주요 기업별 시장 점유율, 성장 전략, 제품 및 서비스에 대한 상세한 평가
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI에 의한 영향, 특허, 혁신, 향후 응용
제7장 지속가능성과 규제 상황
제8장 고객 상황과 구매 행동
제9장 유세포 분석 제품 시장(유형별)
제10장 유세포 분석 제품 시장(기술별)
제11장 유세포 분석 제품 시장(검출 방식별)
제12장 유세포 분석 제품 시장(최종사용자별)
제13장 유세포 분석 서비스 시장(유형별)
제14장 유세포 분석 서비스 시장(최종사용자별)
제15장 유세포 분석 시장(용도별)
제16장 유세포 분석 시장(지역별)
제17장 경쟁 구도
제18장 기업 개요
제19장 조사 방법
제20장 부록
KSM 26.10.08The flow cytometry market is expected to reach USD 10.57 billion by 2034 from USD 5.56 billion in 2026, at a CAGR of 8.4% during the forecast period. The market is expected to grow steadily during the forecast period, driven by increasing use of flow cytometry in immunology, oncology, hematology, drug discovery, cell and gene therapy, and clinical diagnostics. Technologies such as conventional flow cytometry, spectral flow cytometry, imaging/hybrid flow cytometry, and bead-based flow cytometry enable detailed analysis of cell phenotype, viability, apoptosis, cell cycle, intracellular proteins, cytokines, and other functional characteristics. These technologies support applications across cancer diagnostics, autoimmune disease assessment, stem cell research, in vitro toxicity testing, cell sorting, vaccine manufacturing, CGT manufacturing, and other biologics manufacturing.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2034 |
| Base Year | 2025 |
| Forecast Period | 2026-2034 |
| Units Considered | Value (USD billion) |
| Segments | Product, Technology, Detection Modality, Application, End User (Product), Service Type, and End User (Service) |
| Regions covered | North America, Europe, the Asia Pacific, Latin America, the Middle East, and Africa |
The growing use of high-parameter analyzers, spectral systems, complex antibody-dye conjugates, multiplex assays, and automated data analysis is further strengthening adoption across pharmaceutical, biotechnology, academic, clinical, and CRO/CDMO settings. In addition, recurring demand for antibodies, assays & kits, controls, calibration reagents, sheath fluids, and other consumables is supporting sustained market growth. However, the market continues to face challenges related to the high cost of advanced instruments, the complexity of multicolor panel design, the need for skilled operators, reagent standardization, and the interpretation of high-dimensional flow cytometry data.
"Bead-based flow cytometry segment is expected to grow at the highest CAGR during the forecast period."
The bead-based flow cytometry segment is projected to grow at the highest CAGR due to the increasing adoption of multiplex assays for simultaneous detection and quantification of multiple analytes from limited sample volumes. Bead-based platforms are increasingly used for cytokine profiling, biomarker analysis, immunoassays, and drug discovery studies, particularly in applications requiring high-throughput multiplex testing. The growing demand for efficient, scalable, and multiplexed analytical workflows across pharmaceutical, biotechnology, and research laboratories is driving segment growth.
"The reagents & consumables segment holds the largest share of the market."
The reagents & consumables segment accounts for the largest share of the flow cytometry market, primarily due to the recurring requirement for antibodies, antibody-dye conjugates, assays & kits, buffers, controls, calibration reagents, sheath fluids, and other consumables in routine flow cytometry workflows. These products are extensively used in immunophenotyping, cytokine detection, apoptosis and cell viability analysis, multiplex assays, and other cellular studies. Their high frequency of consumption across academic, clinical, pharmaceutical, biotechnology, and CRO/CDMO laboratories supports the segment's leading market position.
"The US is expected to grow at the highest CAGR during the forecast period."
The US is expected to grow at the highest CAGR in the flow cytometry market due to its strong presence of leading flow cytometry manufacturers, pharmaceutical & biotechnology companies, advanced research infrastructure, and high adoption of sophisticated cell analysis technologies across research and clinical settings. Rising use of flow cytometry in oncology, immunology, hematology, drug discovery, cell & gene therapy, and clinical diagnostics is driving market growth. High-parameter analyzers, spectral flow cytometry systems, cell sorters, antibody-dye conjugates, multiplex assays, and advanced data analysis solutions are increasingly used across pharmaceutical & biotechnology companies, academic & research institutes, hospitals & clinical testing laboratories, and CROs & CDMOs.
The primary interviews conducted for this report can be categorized as follows:
- By Respondent: Supply Side (70%) and Demand Side (30%)
- By Designation: Managers (45%), CXOs and Directors (30%), and Executives (25%)
- By Region: North America (40%), Europe (25%), Asia Pacific (25%), Latin America (5%), and the Middle East & Africa (5%)
BD (US), Danaher Corporation (US), Thermo Fisher Scientific Inc. (US), Agilent Technologies, Inc. (US), Bio-Rad Laboratories, Inc. (US), Sony Corporation (Japan), Miltenyi Biotec (Germany), Enzo Biochem Inc. (US), Sysmex Corporation (Japan), Cytek Biosciences (US), BIOMERIEUX (France), Cytonome/ST LLC (US), Sartorius AG (Germany), Union Biometrica, Inc. (US), Takara Bio Inc. (Japan), Revvity (US), Charles River Laboratories (US), The Jackson Laboratory (US), Apogee Flow Systems Ltd. (UK), Stratedigm, Inc (US), Nova Biomedical (US), On-chip Biotechnologies Co., Ltd. Corporation (Japan), Precision Cell Systems (US), CytoBuoy (Netherlands), CUSABIO TECHNOLOGY LLC (US), De Novo Software (US), Altasciences (Canada), RayBiotech, Inc. (US), and KCAS Bio (US) are some of the key companies offering flow cytometry products and services.
Research Coverage
This research report categorizes the flow cytometry market by product {reagents & consumables [antibodies (unconjugated antibodies and antibody-dye conjugates), assays & kits (phenotyping assays & kits, cytokine detection assays & kits, multiplex assays & kits, apoptosis & cell viability assays, and other assays & kits) and other reagents & consumables], instruments [cell analyzers (high-plex/high-parameter analyzers, standard benchtop/mid-parameter analyzers, and compact/low-parameter analyzers), and cell sorters (high-range cell sorters, mid-range cell sorters, and low-range cell sorters)], software, and accessories}, technology (cell-based flow cytometry and bead-based flow cytometry), detection modality (conventional flow cytometry, spectral flow cytometry, and imaging/hybrid flow cytometry), application [research applications (drug discovery, stem cell research, in vitro toxicity testing, immunology, cell sorting, apoptosis, cell cycle analysis, cell viability, cell counting, and other research applications), clinical applications (cancer diagnostics, hematology, autoimmune diseases, organ transplantation, and other clinical applications), pharmaceutical & biotechnology applications, and industrial applications], product market by end user (academic & research institutes, hospitals & clinical testing laboratories, pharmaceutical & biotechnology companies, and CROs & CDMOs), service market by type (immunophenotyping services, cell sorting services, assay development services, and other services), service market by end user (academic & research institutes, hospitals & clinical testing laboratories, and pharmaceutical & biotechnology companies), and region (North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa).
The report's scope encompasses detailed information about the primary factors, including drivers, restraints, challenges, and opportunities, which influence the growth of the flow cytometry market. A comprehensive analysis of key industry players has been conducted to provide insights into their business overviews, product portfolios, key strategies, new product launches, acquisitions, and recent developments in the flow cytometry market. This report also includes a competitive analysis of emerging startups in the flow cytometry industry ecosystem.
Key Benefits of Buying the Report
The report will assist market leaders and new entrants by providing revenue estimates for the overall market and its subsegments. It will also help stakeholders better understand the competitive landscape and gain more insights to position their businesses effectively and develop suitable go-to-market strategies. This report will enable stakeholders to grasp the market's pulse and provide insights into key drivers, restraints, opportunities, and challenges.
The report provides insights into the following pointers:
- Analysis of key drivers (rising adoption of flow cytometry in oncology research and diagnostics, increasing demand for high-parameter and spectral flow cytometry for multiparameter cellular analysis, growing application of flow cytometry in cell and gene therapy development and manufacturing), restraints (high cost of advanced flow cytometers), opportunities (increasing adoption of flow cytometry in clinical diagnostics and biopharmaceutical quality control, growing demand for automated and AI-enabled flow cytometry for high-throughput and complex data analysis), and challenges (complexities related to reagent development) influencing the market growth
- Product Development/Innovation: Detailed insights into newly launched products and innovations in the flow cytometry market
- Market Development: Comprehensive information about lucrative markets and analysis of the market across varied regions
- Market Diversification: Exhaustive information about new products, untapped geographies, recent developments, and investments in the flow cytometry market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and products & services of leading players, BD (US), Danaher Corporation (US), Thermo Fisher Scientific Inc. (US), Agilent Technologies, Inc. (US), Bio-Rad Laboratories, Inc. (US), Sony Corporation (Japan), Miltenyi Biotec (Germany), Enzo Biochem Inc. (US), Sysmex Corporation (Japan), Cytek Biosciences (US), and Revvity (US), among others, for the flow cytometry market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONS COVERED
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.4 STAKEHOLDERS
- 1.5 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN FLOW CYTOMETRY MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 FLOW CYTOMETRY MARKET OVERVIEW
- 3.2 NORTH AMERICA: FLOW CYTOMETRY MARKET, BY PRODUCT & COUNTRY
- 3.3 FLOW CYTOMETRY MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
- 3.4 FLOW CYTOMETRY MARKET SHARE, BY TECHNOLOGY, 2026 VS. 2034 (%)
- 3.5 FLOW CYTOMETRY MARKET, BY OFFERING, 2024-2034 (USD MILLION)
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising adoption of flow cytometry in oncology research and diagnostics
- 4.2.1.2 Increasing demand for high-parameter and spectral flow cytometry for multiparameter cellular analysis
- 4.2.1.3 Growing applications in cell & gene therapy development and manufacturing
- 4.2.2 RESTRAINTS
- 4.2.2.1 High cost of advanced flow cytometers
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Increasing adoption in clinical diagnostics and biopharmaceutical quality control
- 4.2.3.2 Growing demand for automated and AI-enabled flow cytometry for high-throughput and complex data analysis
- 4.2.4 CHALLENGES
- 4.2.4.1 Complexities related to reagent development
- 4.2.1 DRIVERS
- 4.3 INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
- 4.4 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 INTENSITY OF COMPETITIVE RIVALRY
- 5.1.2 BARGAINING POWER OF SUPPLIERS
- 5.1.3 BARGAINING POWER OF BUYERS
- 5.1.4 THREAT FROM SUBSTITUTES
- 5.1.5 THREAT FROM NEW ENTRANTS
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL HEALTHCARE INDUSTRY
- 5.2.4 TRENDS IN GLOBAL BIOTECH INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.4.1 ROLE OF PLAYERS IN ECOSYSTEM
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TREND, BY KEY PLAYER, 2023-2025
- 5.5.2 AVERAGE SELLING PRICE TREND, BY REGION, 2023-2025
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 9027.50)
- 5.6.2 EXPORT SCENARIO (HS CODE 9027.50)
- 5.7 KEY CONFERENCES & EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.9 INVESTMENT & FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 AI-ASSISTED FLOW CYTOMETRY SUPPORTS MEASURABLE RESIDUAL DISEASE ASSESSMENT FOR CHRONIC LYMPHOCYTIC LEUKEMIA
- 5.10.2 SPECTRAL FLOW CYTOMETRY EXPANDS HIGH-DIMENSIONAL IMMUNE PROFILING
- 5.10.3 NO-WASH FLOW CYTOMETRY IMPROVES CAR-T CELL MONITORING
- 5.11 IMPACT OF 2025 US TARIFFS-FLOW CYTOMETRY MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRIES/REGIONS
- 5.11.4.1 US
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 IMPACT ON END-USE INDUSTRIES
- 5.11.5.1 Academic & Research Institutes
- 5.11.5.2 Hospitals & Clinical Testing Laboratories
- 5.11.5.3 Pharmaceutical & Biotechnology Companies
- 5.11.5.4 CROs & CDMOs
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGIES
- 6.1.1.1 Mass cytometry
- 6.1.1.2 Microfluidics
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Single-cell analysis
- 6.1.2.2 Spatial analysis
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 Single-cell RNA sequencing
- 6.1.3.2 High-content screening
- 6.1.1 KEY TECHNOLOGIES
- 6.2 TECHNOLOGY ROADMAP
- 6.3 PATENT ANALYSIS
- 6.3.1 METHODOLOGY
- 6.3.2 NUMBER OF PATENTS FILED, BY DOCUMENT TYPE
- 6.3.3 LIST OF KEY PATENTS
- 6.4 FUTURE APPLICATIONS
- 6.5 IMPACT OF AI/GEN AI ON FLOW CYTOMETRY MARKET
- 6.5.1 TOP USE CASES AND MARKET POTENTIAL
- 6.5.2 BEST PRACTICES IN AI-ENABLED FLOW CYTOMETRY DATA ANALYSIS AND INTERPRETATION
- 6.5.3 CASE STUDIES OF AI IMPLEMENTATION IN FLOW CYTOMETRY MARKET
- 6.5.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.5 CLIENTS' READINESS TO ADOPT AI-INTEGRATED FLOW CYTOMETRY SOLUTIONS
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.1.2.1 North America
- 7.1.2.2 Europe
- 7.1.2.3 Asia Pacific
- 7.1.2.4 Rest of the world
- 7.2 SUSTAINABILITY INITIATIVES
- 7.3 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 KEY BUYING CRITERIA, BY END USER
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
9 FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 REAGENTS & CONSUMABLES
- 9.2.1 ANTIBODIES
- 9.2.1.1 Unconjugated Antibodies
- 9.2.1.1.1 Expanding assay customization and biomarker validation to drive market
- 9.2.1.2 Antibody Dye Conjugates
- 9.2.1.2.1 Expanding multicolor and spectral workflows to boost market
- 9.2.1.1 Unconjugated Antibodies
- 9.2.2 ASSAYS & KITS
- 9.2.2.1 Phenotyping Assays & Kits
- 9.2.2.1.1 Standardized immune profiling and expanding cell therapy characterization to drive market
- 9.2.2.2 Cytokine Detection Assays & Kits
- 9.2.2.2.1 Growing emphasis on functional immune-response assessment to boost market
- 9.2.2.3 Multiplex Assays & Kits
- 9.2.2.3.1 Broader biomarker profiling and sample-efficient testing to drive market
- 9.2.2.4 Apoptosis & Cell Viability Assays & Kits
- 9.2.2.4.1 Expanding drug-response testing and cell quality assessment to boost market
- 9.2.2.5 Other Assays & Kits
- 9.2.2.1 Phenotyping Assays & Kits
- 9.2.3 OTHER REAGENTS & CONSUMABLES
- 9.2.1 ANTIBODIES
- 9.3 INSTRUMENTS
- 9.3.1 CELL ANALYZERS
- 9.3.1.1 High-Plex/ High-Parameter Analyzers
- 9.3.1.1.1 Expanding high-dimensional immune profiling and biomarker research to accelerate market growth
- 9.3.1.2 Standard Benchtop/ Mid-Parameter Analyzers
- 9.3.1.2.1 Increasing demand for accessible, compact, and simplified routine cell analysis to drive market
- 9.3.1.3 Compact/Low-Parameter Analyzers
- 9.3.1.3.1 Decentralized routine testing and demand for simpler cell analysis to expand adoption
- 9.3.1.1 High-Plex/ High-Parameter Analyzers
- 9.3.2 CELL SORTERS
- 9.3.2.1 High-Range Cell Sorters
- 9.3.2.1.1 High-dimensional research and rare-cell recovery to drive market
- 9.3.2.2 Mid-Range Cell Sorters
- 9.3.2.2.1 Expanding in-house research workflows and demand for flexible, cost-efficient cell purification to drive market
- 9.3.2.3 Low-Range Cell Sorters
- 9.3.2.3.1 Affordability, ease of use, and decentralized access to boost growth
- 9.3.2.1 High-Range Cell Sorters
- 9.3.1 CELL ANALYZERS
- 9.4 SOFTWARE
- 9.4.1 RISING DATA COMPLEXITY AND AUTOMATION REQUIREMENTS TO DRIVE MARKET
- 9.5 ACCESSORIES
- 9.5.1 EXPANDING INSTRUMENT INSTALLATIONS, TECHNOLOGY UPGRADES, AND CALIBRATION REQUIREMENTS TO DRIVE MARKET
10 FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY
- 10.1 INTRODUCTION
- 10.2 CELL-BASED FLOW CYTOMETRY
- 10.2.1 RISING DEMAND FOR HIGH-PARAMETER CELLULAR ANALYSIS TO BOOST MARKET GROWTH
- 10.3 BEAD-BASED FLOW CYTOMETRY
- 10.3.1 GROWING DEMAND FOR MULTIPLEX BIOMARKER ANALYSIS TO FUEL SEGMENT
11 FLOW CYTOMETRY PRODUCTS MARKET, BY DETECTION MODALITY
- 11.1 INTRODUCTION
- 11.2 CONVENTIONAL FLOW CYTOMETRY
- 11.2.1 ESTABLISHED FILTER-BASED DETECTION, VALIDATED ASSAYS, AND ROUTINE CLINICAL WORKFLOWS TO DRIVE MARKET
- 11.3 SPECTRAL FLOW CYTOMETRY
- 11.3.1 HIGH-PARAMETER ANALYSIS, SPECTRAL UNMIXING, AND EXPANDING PANEL COMPLEXITY TO PROPEL GROWTH
- 11.4 IMAGING/HYBRID FLOW CYTOMETRY
- 11.4.1 DEMAND FOR SIMULTANEOUS MORPHOLOGICAL AND FLUORESCENCE-BASED CHARACTERIZATION TO DRIVE MARKET
12 FLOW CYTOMETRY PRODUCTS MARKET, BY END USER
- 12.1 INTRODUCTION
- 12.2 ACADEMIC & RESEARCH INSTITUTES
- 12.2.1 EXPANDING RESEARCH INFRASTRUCTURE TO BOOST MARKET GROWTH
- 12.3 HOSPITALS & CLINICAL TESTING LABORATORIES
- 12.3.1 EXPANDING CLINICAL DIAGNOSTICS AND DISEASE MONITORING TO FUEL SEGMENT
- 12.4 PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES
- 12.4.1 EXPANDING DRUG DISCOVERY AND CELL THERAPY PIPELINES TO DRIVE MARKET
- 12.5 CROS & CDMOS
- 12.5.1 RISING OUTSOURCING OF COMPLEX BIOANALYTICAL WORKFLOWS TO DRIVE GROWTH
13 FLOW CYTOMETRY SERVICES MARKET, BY TYPE
- 13.1 INTRODUCTION
- 13.2 IMMUNOPHENOTYPING SERVICES
- 13.2.1 EXPANDING BIOMARKER-DRIVEN TRIALS AND ADVANCED THERAPIES TO BOOST MARKET GROWTH
- 13.3 CELL SORTING SERVICES
- 13.3.1 INCREASING DEMAND FOR RARE-CELL ISOLATION, SINGLE-CELL WORKFLOWS, AND ADVANCED SPECTRAL SORTING TO FUEL SEGMENT
- 13.4 ASSAY DEVELOPMENT SERVICES
- 13.4.1 INCREASING THERAPEUTIC COMPLEXITY AND DEMAND FOR VALIDATED, CUSTOMIZED HIGH-PARAMETER ASSAYS TO DRIVE MARKET
- 13.5 OTHER SERVICES
14 FLOW CYTOMETRY SERVICES MARKET, BY END USER
- 14.1 INTRODUCTION
- 14.2 ACADEMIC & RESEARCH INSTITUTES
- 14.2.1 EXPANDING ACCESS TO SPECIALIZED CYTOMETRY EXPERTISE TO BOOST MARKET GROWTH
- 14.3 HOSPITALS & CLINICAL TESTING LABORATORIES
- 14.3.1 RISING DEMAND FOR SPECIALIZED CLINICAL TESTING TO FUEL SEGMENT
- 14.4 PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES
- 14.4.1 EXPANDING OUTSOURCING OF COMPLEX BIOANALYTICAL TESTING TO DRIVE MARKET
15 FLOW CYTOMETRY MARKET, BY APPLICATION
- 15.1 INTRODUCTION
- 15.2 RESEARCH APPLICATIONS
- 15.2.1 DRUG DISCOVERY
- 15.2.1.1 High-throughput cellular screening and deeper phenotypic analysis to boost market growth
- 15.2.2 STEM CELL RESEARCH
- 15.2.2.1 Expanding iPSC research to drive market
- 15.2.3 IN VITRO TOXICITY TESTING
- 15.2.3.1 Growing mechanistic safety testing to drive market
- 15.2.4 IMMUNOLOGY
- 15.2.4.1 High-dimensional immune profiling to aid market growth
- 15.2.5 CELL SORTING
- 15.2.5.1 Rare-cell isolation and integration with downstream single-cell analysis to drive market
- 15.2.6 APOPTOSIS
- 15.2.6.1 Expanding cancer therapy research to propel market growth
- 15.2.7 CELL CYCLE ANALYSIS
- 15.2.7.1 Expanding cell cycle-targeted drug research to drive market
- 15.2.8 CELL VIABILITY
- 15.2.8.1 Growing cell-based research and increasing emphasis on standardized cell quality assessment to drive market growth
- 15.2.9 CELL COUNTING
- 15.2.9.1 Increasing demand for accurate population-specific quantification to drive market
- 15.2.10 OTHER RESEARCH APPLICATIONS
- 15.2.1 DRUG DISCOVERY
- 15.3 CLINICAL APPLICATIONS
- 15.3.1 CANCER DIAGNOSTICS
- 15.3.1.1 High-parameter cancer immunophenotyping and expanding residual disease assessment to drive market
- 15.3.2 HEMATOLOGY
- 15.3.2.1 Expanding stem cell transplantation and specialized blood cell assessment to propel market growth
- 15.3.3 AUTOIMMUNE DISEASES
- 15.3.3.1 Advanced immune profiling and biomarker-based patient stratification to drive market
- 15.3.4 ORGAN TRANSPLANTATION
- 15.3.4.1 Increasing demand for sensitive donor-recipient compatibility assessment to drive market
- 15.3.5 OTHER CLINICAL APPLICATIONS
- 15.3.1 CANCER DIAGNOSTICS
- 15.4 PHARMACEUTICAL & BIOTECHNOLOGY APPLICATIONS
- 15.4.1 HIGH-THROUGHPUT DRUG DISCOVERY AND EXPANDING ADVANCED THERAPY DEVELOPMENT TO DRIVE MARKET
- 15.5 INDUSTRIAL APPLICATIONS
- 15.5.1 DEMAND FOR RAPID MICROBIAL QUALITY ASSESSMENT TO DRIVE MARKET
16 FLOW CYTOMETRY MARKET, BY REGION
- 16.1 INTRODUCTION
- 16.2 NORTH AMERICA
- 16.2.1 US
- 16.2.1.1 Advanced biomedical research and expanding cell therapy development to drive market
- 16.2.2 CANADA
- 16.2.2.1 Public research investment and expanding advanced cellular research to boost market growth
- 16.2.1 US
- 16.3 EUROPE
- 16.3.1 GERMANY
- 16.3.1.1 Research infrastructure investment and growing high-dimensional cellular studies to aid market growth
- 16.3.2 UK
- 16.3.2.1 Research infrastructure funding and expanding translational science to spur market growth
- 16.3.3 FRANCE
- 16.3.3.1 Public research infrastructure investment and advanced oncology research to fuel market growth
- 16.3.4 ITALY
- 16.3.4.1 Research infrastructure modernization to boost market growth
- 16.3.5 SPAIN
- 16.3.5.1 Advanced hematology diagnostics and expanding translational research to augment market growth
- 16.3.6 REST OF EUROPE
- 16.3.1 GERMANY
- 16.4 ASIA PACIFIC
- 16.4.1 CHINA
- 16.4.1.1 Expanding cell therapy research, clinical adoption, and localized instrument manufacturing to support market growth
- 16.4.2 JAPAN
- 16.4.2.1 Regenerative medicine leadership and investment in advanced shared cytometry infrastructure to drive market
- 16.4.3 INDIA
- 16.4.3.1 Expanding biopharma research and access to advanced cytometry infrastructure to drive market
- 16.4.4 AUSTRALIA
- 16.4.4.1 Research infrastructure modernization and expanding precision medicine to propel market growth
- 16.4.5 SOUTH KOREA
- 16.4.5.1 Increasing adoption of high-dimensional cellular analysis to spur market growth
- 16.4.6 SINGAPORE
- 16.4.6.1 Biomedical research investment and localization of advanced cytometry manufacturing to drive market
- 16.4.7 INDONESIA
- 16.4.7.1 Healthcare modernization and expanding biomedical research to drive market
- 16.4.8 REST OF ASIA PACIFIC
- 16.4.1 CHINA
- 16.5 LATIN AMERICA
- 16.5.1 BRAZIL
- 16.5.1.1 Expanding advanced biomedical research and modernization of shared cytometry infrastructure to boost market growth
- 16.5.2 MEXICO
- 16.5.2.1 Expanding shared research infrastructure to fuel market growth
- 16.5.3 REST OF LATIN AMERICA
- 16.5.1 BRAZIL
- 16.6 MIDDLE EAST
- 16.6.1 GCC COUNTRIES
- 16.6.1.1 Saudi Arabia
- 16.6.1.1.1 Advanced hematology diagnostics to boost market growth
- 16.6.1.2 UAE
- 16.6.1.2.1 Expanding advanced diagnostic infrastructure to drive market
- 16.6.1.3 Rest of GCC countries
- 16.6.1.1 Saudi Arabia
- 16.6.2 REST OF MIDDLE EAST
- 16.6.1 GCC COUNTRIES
- 16.7 AFRICA
- 16.7.1 PUBLIC HEALTH INVESTMENT AND EXPANDING BIOMEDICAL RESEARCH INFRASTRUCTURE TO PROPEL MARKET GROWTH
17 COMPETITIVE LANDSCAPE
- 17.1 INTRODUCTION
- 17.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2021-2025
- 17.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN FLOW CYTOMETRY MARKET, JANUARY 2023-JULY 2026
- 17.3 REVENUE ANALYSIS, 2021-2025
- 17.4 MARKET SHARE ANALYSIS, 2025
- 17.5 BRAND COMPARISON
- 17.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 17.6.1 STARS
- 17.6.2 EMERGING LEADERS
- 17.6.3 PERVASIVE PLAYERS
- 17.6.4 PARTICIPANTS
- 17.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 17.6.5.1 Company footprint
- 17.6.5.2 Region footprint
- 17.6.5.3 Product & service footprint
- 17.6.5.4 Technology footprint
- 17.6.5.5 Application footprint
- 17.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 17.7.1 PROGRESSIVE COMPANIES
- 17.7.2 RESPONSIVE COMPANIES
- 17.7.3 DYNAMIC COMPANIES
- 17.7.4 STARTING BLOCKS
- 17.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 17.7.5.1 Detailed list of key startup/SME players
- 17.7.5.2 Competitive benchmarking of startups/SMEs
- 17.8 COMPANY VALUATION AND FINANCIAL METRICS
- 17.8.1 COMPANY VALUATION
- 17.8.2 FINANCIAL METRICS
- 17.9 COMPETITIVE SCENARIO
- 17.9.1 PRODUCT LAUNCHES
- 17.9.2 DEALS
18 COMPANY PROFILES
- 18.1 KEY PLAYERS
- 18.1.1 BD
- 18.1.1.1 Business overview
- 18.1.1.2 Products/services/solutions offered
- 18.1.1.3 Recent developments
- 18.1.1.3.1 Product launches and product enhancements
- 18.1.1.3.2 Deals
- 18.1.1.4 MnM view
- 18.1.1.4.1 Right to win
- 18.1.1.4.2 Strategic choices
- 18.1.1.4.3 Weaknesses & competitive threats
- 18.1.2 DANAHER CORPORATION
- 18.1.2.1 Business overview
- 18.1.2.2 Products/services/solutions offered
- 18.1.2.3 Recent developments
- 18.1.2.3.1 Product launches
- 18.1.2.3.2 Deals
- 18.1.2.4 MnM view
- 18.1.2.4.1 Right to win
- 18.1.2.4.2 Strategic choices
- 18.1.2.4.3 Weaknesses & competitive threats
- 18.1.3 THERMO FISHER SCIENTIFIC INC.
- 18.1.3.1 Business overview
- 18.1.3.2 Products/services/solutions offered
- 18.1.3.3 Recent developments
- 18.1.3.3.1 Product launches
- 18.1.3.4 MnM view
- 18.1.3.4.1 Right to win
- 18.1.3.4.2 Strategic choices
- 18.1.3.4.3 Weaknesses & competitive threats
- 18.1.4 REVVITY
- 18.1.4.1 Business overview
- 18.1.4.2 Products/services/solutions offered
- 18.1.4.3 MnM view
- 18.1.4.3.1 Right to win
- 18.1.4.3.2 Strategic choices
- 18.1.4.3.3 Weaknesses & competitive threats
- 18.1.5 AGILENT TECHNOLOGIES, INC.
- 18.1.5.1 Business overview
- 18.1.5.2 Products/services/solutions offered
- 18.1.5.3 Recent developments
- 18.1.5.3.1 Product launches
- 18.1.6 SONY GROUP CORPORATION
- 18.1.6.1 Business overview
- 18.1.6.2 Products/services/solutions offered
- 18.1.6.3 Recent developments
- 18.1.6.3.1 Product launches
- 18.1.6.3.2 Deals
- 18.1.7 BIO-RAD LABORATORIES, INC.
- 18.1.7.1 Business overview
- 18.1.7.2 Products/Services/Solutions offered
- 18.1.7.3 Recent developments
- 18.1.7.3.1 Product launches
- 18.1.8 MILTENYI BIOTEC
- 18.1.8.1 Business overview
- 18.1.8.2 Products/services/solutions offered
- 18.1.9 ENZO BIOCHEM, INC.
- 18.1.9.1 Business overview
- 18.1.9.2 Products/services/solutions offered
- 18.1.10 SYSMEX CORPORATION
- 18.1.10.1 Business overview
- 18.1.10.2 Products/services/solutions offered
- 18.1.11 CYTEK BIOSCIENCES, INC.
- 18.1.11.1 Business overview
- 18.1.11.2 Products/services/solutions offered
- 18.1.11.3 Recent developments
- 18.1.11.3.1 Product launches
- 18.1.11.3.2 Deals
- 18.1.12 BIOMERIEUX
- 18.1.12.1 Business overview
- 18.1.12.2 Products/services/solutions offered
- 18.1.12.3 Recent developments
- 18.1.12.3.1 Deals
- 18.1.13 CYTONOME/ST, LLC
- 18.1.13.1 Business overview
- 18.1.13.2 Products/services/solutions offered
- 18.1.14 SARTORIUS AG
- 18.1.14.1 Business overview
- 18.1.14.2 Products/services/solutions offered
- 18.1.14.3 Recent developments
- 18.1.14.3.1 Product launches
- 18.1.15 UNION BIOMETRICA, INC.
- 18.1.15.1 Business overview
- 18.1.15.2 Products/services/solutions offered
- 18.1.16 TAKARA BIO INC.
- 18.1.16.1 Business overview
- 18.1.16.2 Products/services/solutions offered
- 18.1.17 CHARLES RIVER LABORATORIES INTERNATIONAL, INC.
- 18.1.17.1 Business overview
- 18.1.17.2 Products/services/solutions offered
- 18.1.18 THE JACKSON LABORATORY
- 18.1.18.1 Business overview
- 18.1.18.2 Products/services/solutions offered
- 18.1.1 BD
- 18.2 OTHER PLAYERS
- 18.2.1 APOGEE FLOW SYSTEMS LTD
- 18.2.2 STRATEDIGM, INC.
- 18.2.3 NOVA BIOMEDICAL CORPORATION
- 18.2.4 ON-CHIP BIOTECHNOLOGIES CO., LTD.
- 18.2.5 PRECISION CELL SYSTEMS, INC.
- 18.2.6 CYTOBUOY B.V.
- 18.2.7 CUSABIO TECHNOLOGY LLC
- 18.2.8 DE NOVO SOFTWARE
- 18.2.9 ALTASCIENCES
- 18.2.10 RAYBIOTECH, INC.
- 18.2.11 KCAS BIO
19 RESEARCH METHODOLOGY
- 19.1 RESEARCH DATA
- 19.1.1 SECONDARY DATA
- 19.1.1.1 Key data from secondary sources
- 19.1.2 PRIMARY DATA
- 19.1.2.1 Key data from primary sources
- 19.1.2.2 Key primary participants
- 19.1.2.3 Breakdown of primary interviews
- 19.1.2.4 Key industry insights
- 19.1.1 SECONDARY DATA
- 19.2 MARKET SIZE ESTIMATION
- 19.2.1 GLOBAL FLOW CYTOMETRY MARKET ESTIMATION, 2025
- 19.2.2 SEGMENTAL MARKET SIZE ESTIMATION
- 19.3 MARKET GROWTH RATE PROJECTIONS
- 19.4 DATA TRIANGULATION
- 19.5 FACTOR ANALYSIS
- 19.6 RESEARCH ASSUMPTIONS
- 19.7 RESEARCH LIMITATIONS AND RISK ASSESSMENT
20 APPENDIX
- 20.1 DISCUSSION GUIDE
- 20.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 20.3 CUSTOMIZATION OPTIONS
- 20.4 RELATED REPORTS
- 20.5 AUTHOR DETAILS


