

|
시장보고서
상품코드
2144547
도로 안전 시장 예측(-2031년) : 제공별, 용도별Road Safety Market By Offering (Traffic Monitoring & Control, ANPR/ANPR, Incident Detection & Response, Smart Signs & Signals, Sensors, Cameras, Road Safety Audits), Application (Accident Prevention, Work Zone Safety) - Global Forecast to 2031 |
||||||

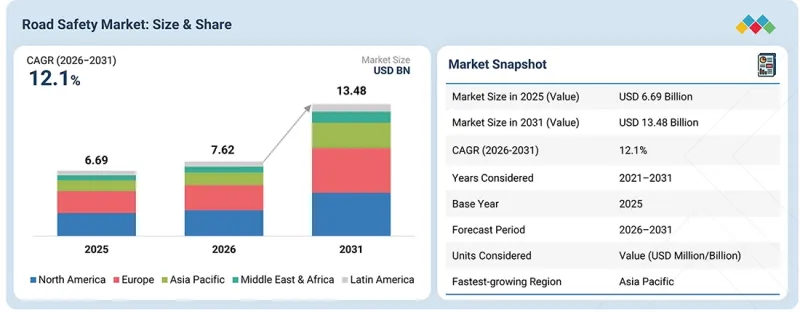
도로 안전 시장은 급속히 확대하고 있으며, 시장 규모는 2026년 76억 2,000만 달러에서 2031년까지 134억 8,000만 달러로 확대하며, 예측 기간 중 CAGR은 12.1%에 달할 것으로 전망되고 있습니다.
이러한 성장은 교통사고 사망자 수 감소를 위한 정부의 노력 강화, 자동 교통 단속 확대, AI를 활용한 영상 분석 기술의 도입 확대, 그리고 스마트 교통 인프라에 대한 투자에 힘입어 이루어지고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 달러(백만/10억) |
| 부문 | 제공 형태, 시행 형태, 용도, 최종사용자 및 지역 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 중동 및 아프리카 및 라틴아메리카 |
동시에, 실시간 사고 감지, 예방적 사고 방지, 취약한 도로 이용자 보호, 그리고 커넥티드 도로 인프라에 대한 수요 증가로 인해 카메라, 센서, ANPR/ALPR, 엣지 AI, V2X 통신, 예측 안전 분석의 도입이 가속화되고 있습니다. 그러나 인프라의 파편화, 레거시 교통 시스템과의 통합, 규제 및 데이터 개인정보 보호 관련 요건, 높은 도입 비용, 상호 운용성 문제는 여전히 대규모 보급에 있으며, 중요한 제약 요인으로 남아 있습니다.
"정부 및 지자체 부문이 가장 큰 시장 점유율을 차지할 전망"
정부 기관과 지자체는 도로 안전 솔루션의 주요 개발 주체입니다. 인식 제고 프로그램의 시행부터 포괄적인 안전 인프라 및 단속 시스템의 관리·도입에 이르기까지 중요한 역할을 수행하고 있습니다. 정부와 지자체는 안전 정책의 규제 당국인 동시에 시행 주체이기도 하여, 도로 안전 시장의 기반을 형성하고 있습니다. 자금 지원 및 프로그램을 통해 대규모 공공안전에 영향을 미칠 수 있습니다. 법규 준수를 철저히 하는 한편, 인프라 업그레이드를 위한 예산도 배정하고 있습니다. 도로상의 신호등과 표지판의 유지 관리에 책임을 질 뿐만 아니라, 적색 신호나 과속을 단속하기 위한 카메라 등 첨단 시스템을 도입하고, AI를 활용하여 위반 행위에 대응하며, 실시간 교통 관리 시스템을 구축하고 있습니다. 2024년 11월, 캐나다 브램턴시는 예노프틱(Yenoptik)사와 협력하여 학교 구역내 법규 준수율을 높이기 위해 180대 이상의 자동 속도 단속 카메라를 도입했습니다.
"통합 솔루션 중 사고 감지 및 대응 분야가 예측 기간 중 가장 빠른 성장을 보일 것으로 전망됩니다."
사고 감지·대응 부문은 도로 안전 시장에서 중요한 카테고리로, 교통사고를 신속하게 감지하고 긴급 서비스 제공자에게 즉시 신고함으로써 부상자, 사망자 및 교통 혼란을 줄이는 데 중점을 두고 있습니다. 이 부문은 스마트 감시, 통신 인프라 및 자동 대응을 통합하여 도로 안전성을 향상시키는 동시에, 사고나 위험한 상황에서 대응 시간을 단축합니다. 이 사고 감지 및 대응 부문은 도로상 사망 사고를 감소시키고, 응급 서비스가 기록을 분석하여 조기 개입을 통해 위험을 완화할 수 있도록 합니다. 도로상 사망자 수를 줄임으로써, 사고 감지 및 대응 부문은 사고로 인한 지연과 정체도 완화하고 전반적인 교통 효율을 향상시킵니다. 도로 안전 분야의 사고 감지 및 대응 부문은 ‘비전 제로(Vision Zero)’, 지능형 교통시스템(ITS), 그리고 자율주행차 도입 준비를 위한 기반으로서 가치를 제공하며, 전 세계 도로 안전 생태계에서 고성장 부문으로 자리매김하고 있습니다.
"북미가 시장 점유율에서 선두를 차지하는 한편, 아시아태평양은 도로 안전 시장에서 가장 빠르게 성장하는 지역으로 부상하고 있습니다."
북미는 현재 도로 안전 시장에서 가장 큰 시장 점유율을 차지하고 있으며, 이는 디지털 기술의 광범위한 도입, 스마트 인프라 기술, 그리고 주요 도로 안전 벤더들의 존재에 힘입은 것입니다. 북미 각국 정부는 ‘비전 제로(Vision Zero)’, 미국의 ‘국가 도로 안전 전략(NRSS)’, 캐나다의 ‘도로 안전 전략 2025’와 같은 프로그램을 도입하고 있으며, 이러한 프로그램들은 더 안전한 도로 이용자, 더 안전한 차량, 그리고 더 스마트한 인프라를 우선시하고 있습니다. 또한 미국 교통부는 ‘모두를 위한 안전한 거리 및 도로(Safe Streets and Roads for All, SS4A)’ 프로그램을 통해 도로 안전 혁신을 추진하고 있습니다. 이 프로그램에는 50억 달러의 예산이 투입되어 있으며, AI를 활용한 단속 프로그램 시행, 자동 속도 측정 카메라 도입, 스마트 신호등 및 보행자 보호 시설 설치 등이 이루어지고 있습니다. 아시아태평양(APAC) 지역은 도시화가 진행되고 자동차 보유율이 상승하며, 도로 교통사고로 인한 사망자 수를 억제하기 위한 정부의 노력이 강화됨에 따라 전 세계 도로 안전 분야에서 가장 빠르게 성장하는 지역으로 부상하고 있습니다. 이에 따라 인도, 중국, 일본, 한국, 호주 등의 국가들은 지능형 교통시스템(ITS)에 대한 대규모 투자, 스마트 시티 계획의 발전, 그리고 교통 단속 기술의 도입을 통해 이 분야를 선도하고 있습니다.
주요 조사 대상의 세부 내역
- 기업별: 티어 I-34%, 티어 II-43%, 티어 III-23%
- 직책별: C급 임원-50%, D급 임원-30%, 기타-20%
- 지역별: 북미-30%, 유럽-30%, 아시아태평양-25%, 중동 및 아프리카-10%, 라틴아메리카-5%
조사 범위
본 조사 보고서에서는 도로 안전 시장을 제공(솔루션(통합 솔루션(법 집행 솔루션, 사고 감지·대응, ALPR/ANPR, 교통 감시·제어, 보행자 안전, 커넥티드·협업형 도로 안전) 및 독립형 솔루션(하드웨어 및 소프트웨어)) 및 서비스),법 집행 유형(자동, 수동 또는 하이브리드), 용도(위반 관리, 교통 최적화, 사고 예방, 긴급 대응 및 시민 계몽·교육, 보행자·VRU(취약한 도로 이용자) 보호, 공사 현장 안전 관리, 보험 위험 평가),최종사용자(정부·지자체, 고속도로 당국, 법 집행 기관, 민간 유료 도로 사업자, 스마트 시티 통합 사업자, 건설 회사, 기타(차량 관리 사업자 및 보험사)) 및 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 라틴아메리카)을 기준으로 분류하고 있습니다. 이 보고서에서는 도로 안전 시장의 성장에 영향을 미치는 주요 요인(촉진요인, 억제요인, 과제, 기회 등)에 대한 상세한 정보를 포괄하고 있습니다. 주요 업계 플레이어에 대한 심층 분석을 통해 각 기업의 사업 개요, 솔루션, 서비스,주요 전략, 계약·제휴·합의, 신제품·서비스 출시, 합병·인수, 그리고 도로 안전 시장의 최근 동향에 대한 인사이트를 제공합니다. 또한 이 보고서에서는 도로 안전 시장 생태계에서 두각을 보이고 있는 스타트업 기업에 대한 경쟁 분석도 다루고 있습니다.
이 보고서를 구매할 때의 주요 이점
이 보고서는 이 시장의 시장 선도 기업 및 신규 진입 기업에게 도로 안전 시장 전체 및 그 하위 부문의 매출에 대한 가장 정확한 추정치를 제공합니다. 이를 통해 이해관계자는 경쟁 구도를 이해하고, 비즈니스를 개선하며, 적절한 시장 진입 전략을 수립하기 위한 추가적인 인사이트를 얻을 수 있습니다. 또한 이해관계자가 시장 동향을 파악하는 데 도움을 주며, 주요 시장 촉진요인, 억제요인, 과제 및 기회에 대한 정보를 제공합니다.
이 보고서는 다음 사항에 대한 인사이트를 제공합니다. :
- 주요 촉진요인 분석(도로 사고로 인한 사망자 및 중상자 감축에 대한 정부의 관심 증가, 자동 속도·신호 위반 단속 시스템의 도입 확대, AI를 활용한 영상 분석,ANPR/ALPR, 지능형 센싱의 채택 확대; 커넥티드 도로 인프라, V2X, 실시간 사고 감지에 대한 투자 증가; 보행자, 자전거 이용자, 공사 현장의 안전 솔루션에 대한 수요 증가),제약 요인(첨단 도로 안전 인프라에 대한 초기 투자 및 운영 비용의 높음; 파편화되고 노후화된 교통 관리 인프라; 카메라, 센서, 통신, 레거시 시스템 간의 상호 운용성 문제; 규제, 개인정보 보호, 데이터 거버넌스 관련 요건; 일부 관할 구역에서의 기술적 전문 지식 및 유지보수 능력 부족),기회(AI를 활용한 예측형 도로 안전 분석 및 예방적 사고 방지 확대; 커넥티드 교차로 및 V2X 기반 안전 애플리케이션 도입 확대; 취약한 도로 이용자 및 공사 현장 보호에 대한 수요 증가; 휴대폰 사용, 안전벨트 미착용,평균 속도 초과, 기타 위험 운전 위반에 대한 자동 단속 확대; 매니지드 서비스 및 통합형 도로 안전 플랫폼의 도입 확대), 그리고 과제(다양한 기상, 조명, 교통 상황 하에서 AI 기반 감지 시스템의 정확성과 신뢰성 확보; 연결된 카메라,차량, 인프라와 관련된 사이버 보안 및 개인정보 보호 위험에 대한 대응; 자동 단속 및 데이터 수집에 대한 일반 시민의 이해와 수용 확보; 여러 공급업체 및 기술에 걸친 상호 운용성 유지; 그리고 복잡하고 대규모의 도입을 관리하면서 측정 가능한 안전 성과를 입증하는 것).
- 제품 개발/혁신: 도로 안전 시장의 향후 기술, 연구개발 활동 및 제품·서비스 출시에 대한 상세 인사이트.
- 시장 개발: 수익성이 높은 시장에 대한 포괄적인 정보 - 이 보고서는 다양한 지역에 걸친 도로 안전 시장을 분석합니다.
- 시장 다각화: 도로 안전 시장의 신제품 및 서비스, 미개발 지역, 최근 동향 및 투자에 대한 포괄적인 정보.
- 경쟁 분석: 도로 안전 시장에서 각 기업의 시장 점유율, 성장 전략, 제품 포트폴리오에 대한 상세한 평가.
자주 묻는 질문
목차
제1장 서론
제2장 요약
제3장 주요 인사이트
- 도로 안전 시장의 매력적인 비즈니스 기회
- 도로 안전 시장: 지역별
- 도로 안전 시장: 상위 3대 최종사용자
- 북미: 도로 안전 시장(제공 및 단속 유형별)
- 도로 안전 시장: 지역별
제4장 시장 개요
- 시장 역학
- 촉진요인
- 억제요인
- 기회
- 과제
- 미충족 수요 및 미개발 분야
- 도로 안전 시장의 미충족 수요
- 미개발 시장의 기회
- 상호 연관된 시장 및 부문 간 기회
- 상호 연관된 시장
- 부문 간 기회
- Tier 1/2/3 기업의 전략적 움직임
- Tier 1/2/3 각 플레이어의 전략적 움직임
제5장 업계 동향
- 도로 안전의 변천사
- Porter's Five Forces 분석
- 신규 진입자의 위협
- 대체품의 위협
- 공급업체의 협상력
- 구매자의 협상력
- 경쟁 기업간 경쟁 관계의 격렬함
- 거시경제 전망
- GDP 동향 및 전망
- 전 세계 도로 안전 데이터 업계 동향
- 전 세계 AI 산업의 동향
- 공급망 분석
- 생태계 분석
- 자동 단속 및 도로 안전용 하드웨어
- 도로 안전 소프트웨어 및 분석
- 관리형 교통 단속 및 도로 안전 서비스
- 지능형 교통 관리 및 커넥티드 도로 안전
- 전문적인 도로 안전 및 단속 솔루션
- 가격 분석
- 주요 기업별 제품·서비스의 평균 판매 가격(2026년)
- 2026년 용도별 참고 가격 분석
- 무역 분석
- 도로 안전·교통 통제 장비(HSN: 853080)의 수출 시나리오
- 도로 안전·교통 통제 장비(HSN: 853080)의 수입 시나리오
- 2026-2027년 주요 회의 및 행사
- 고객의 비즈니스에 영향을 미치는 동향/파괴적 변화
- 투자 및 자금 조달 시나리오
- 사례 연구 분석
- SENSYS GATSO, 헤링플리트 다리에 고속 단속 시스템 도입
- JENOPTIK, 뉴욕에 자동 과속 단속 시스템을 도입하여 도로 안전을 향상시켰다.
- ACUSENSUS, 퀸즐랜드주에서 휴대폰 사용 및 안전벨트 착용 단속 실시
- KAPSCH, 인도에서 C-ITS를 활용한 커넥티드 도로 안전 실현
- DERQ, 프리몬트에 AI 기반 교차로 안전 분석 시스템 도입
- HAYDEN AI, 자전거 도로 자동 단속을 통해 도로 안전 향상
- NOTRAFFIC, 피닉스에서 교차로 안전성을 향상시켜 신호 위반을 줄였다.
- VITRONIC, 몽고메리 카운티에 관리형 자동 교통 단속 시스템 도입
- 2025년 미국 관세의 영향 - 도로 안전 시장
- 주요 관세율
- 가격에 미치는 영향 분석
- 국가 및 지역에 미치는 영향
- 최종 용도 산업에 미치는 영향
제6장 기술의 진보, 특허, 혁신 및 향후 응용
- 주요 신규 기술
- AI를 활용한 컴퓨터 비전 및 영상 분석
- LiDAR, 레이더 및 첨단 센싱 기술
- 자동 번호판 인식(ANPR/ALPR)
- 도로변 및 차량 탑재 센서
- 첨단 교통 단속 시스템
- 보완 기술
- 전지구위성항법시스템(GNSS) 및 고정밀 위치 측정
- 엣지 컴퓨팅 및 엣지 AI
- 클라우드 컴퓨팅 및 데이터 분석
- 도로 기상 정보 시스템(RWIS)
- 지리공간 및 디지털 매핑 기술
- 관련 기술
- 첨단 운전자 지원 시스템(ADAS)
- 커넥티드·자율주행차(CAV)
- 지능형 교통시스템(ITS)
- 협동형 적응형 크루즈 컨트롤(CACC)
- 교통 관리 및 적응형 신호 제어
- 기술 로드맵
- 특허 분석
- 조사 방법
- 2016-2026년 출원 특허(문서 유형별)
- 혁신과 특허 출원
- 미래의 응용
- 자율주행에서의 도로 안전 대책
- 지능형 도로 안전 공학
- 실시간 멀티모달 위험 모니터링
- 예측형 도로 안전 및 위험 분석
- 커넥티드·협동형 도로 안전 운영
제7장 규제 현황
- 지역별 규제 및 규정 준수
- 규제기관, 정부 기관 및 기타 조직
- 주요 규제
- 업계 표준
제8장 고객 현황과 구매 행동
- 의사결정 과정
- 구매자의 이해관계자와 구매 평가 기준
- 구매 기준
- 도입 장벽과 내부적 과제
- 다양한 업계의 최종사용자가 가진 충족되지 않은 요구
제9장 도로 안전 시장: 제공 유형별
- 솔루션 제공
- 서비스
제10장 도로 안전 시장: 단속 유형별
- 자동 단속
- 수동 단속
- 하이브리드형 단속
제11장 도로 안전 시장: 용도별
- 위반 관리
- 교통 최적화
- 사고 예방
- 긴급 대응
- 운전자 행동 모니터링
- 시민 대상 계몽 및 교육
- 보행자 및 취약한 도로 이용자 보호
- 공사 현장의 안전 관리
- 보험 위험 평가
제12장 도로 안전 시장: 최종사용자별
- 정부·지자체
- 고속도로 관리 기관
- 법 집행 기관
- 민간 유료 도로 운영 사업자
- 스마트 시티 통합 사업자
- 건설 회사
- 기타 최종사용자
제13장 도로 안전 시장: 지역별
- 북미
- 북미: 도로 안전 시장의 성장 촉진요인
- 미국
- 캐나다
- 유럽
- 유럽: 도로 안전 시장의 성장 촉진요인
- 영국
- 독일
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽
- 아시아태평양
- 아시아태평양: 도로 안전 시장의 성장 촉진요인
- 중국
- 일본
- 인도
- 호주·뉴질랜드
- 한국
- 기타 아시아태평양
- 중동 및 아프리카
- 중동 및 아프리카: 도로 안전 시장 촉진요인
- 중동 및 아프리카: 거시경제 전망
- 사우디아라비아
- 아랍에미리트(UAE)
- 남아프리카
- 기타 중동 및 아프리카
- 라틴아메리카
- 라틴아메리카: 도로 안전 시장의 성장 촉진요인
- 브라질
- 멕시코
- 아르헨티나
- 기타 라틴아메리카
제14장 경쟁 현황
- 개요
- 주요 기업의 전략(2025-2026년)
- 수익 분석(2021-2025년)
- 시장 점유율 분석(2025년)
- 시장 순위 분석(2025년)
- 제품 비교 분석
- 하드웨어별 제품 비교 분석(도로 안전)
- 소프트웨어별 제품 비교 분석(도로 안전)
- 기업 평가 매트릭스: 주요 기업(통합 솔루션), 2025년
- 스타 기업
- 신흥 리더
- 광범위한 기업
- 진입 기업
- 기업 사업 전개: 주요 기업, 2025년
- 기업 평가 매트릭스: 주요 기업(독립형 솔루션 - 하드웨어 공급업체), 2025년
- 스타 기업
- 신흥 리더
- 광범위한 기업
- 진입 기업
- 기업 사업 전개: 하드웨어, 2025년
- 기업 평가 매트릭스: 주요 기업(독립형 솔루션 - 소프트웨어 제공업체), 2025년
- 스타 기업
- 신흥 리더
- 광범위한 기업
- 진입 기업
- 기업 사업 전개: 소프트웨어 제공업체, 2025년
- 기업 평가 및 재무 지표
- 경쟁 시나리오 및 동향
- 제품 출시 및 기능 강화
- 거래
제15장 기업 개요
- 주요 기업
- JENOPTIK
- KAPSCH TRAFFICCOM
- SENSYS GATSO GROUP
- VERRA MOBILITY
- TELEDYNE FLIR
- MOTOROLA SOLUTIONS
- IDEMIA
- SWARCO
- VITRONIC
- SIEMENS
- CUBIC CORPORATION
- 기타 주요 기업
- DAHUA TECHNOLOGY
- LASER TECHNOLOGY
- TRAFFIC MANAGEMENT TECHNOLOGIES
- TRIFOIL
- KRIA
- SYNTELL
- TRUVELO
- CLEARVIEW INTELLIGENCE
- SIMICON
- FRED ENGINEERING
- KODIAK ROBOTICS
- HUMANISING AUTONOMY
- VEBITS AI
- CONNECTED WISE LLC
- SAFEROAD
- LIVEROAD ANALYTICS
- VIVACITY
- NOTRAFFIC
- VALERANN
- ACUSENSUS
- HAYDEN AI
- DERQ
제16장 조사 방법론
제17장 인접 및 관련 시장
- 지능형 교통시스템(ITS) 시장 - 2030년까지의 세계 전망
- 시장 정의
- 시장 개요
- 교통 관리 시장 - 2029년까지의 세계 전망
- 시장 정의
- 시장 개요
제18장 부록
KSA 26.10.15The road safety market is expanding rapidly, with a projected market size rising from USD 7.62 billion in 2026 to USD 13.48 billion by 2031, at a CAGR of 12.1% during the forecast period. Growth is being supported by increasing government focus on reducing road fatalities, expanding automated traffic enforcement, rising adoption of AI-powered video analytics, and investments in intelligent transportation infrastructure.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | USD (Million/Billion) |
| Segments | Offering, Enforcement Type, Application, End User, and Region |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, and Latin America |
At the same time, the increasing need for real-time incident detection, proactive accident prevention, vulnerable road user protection, and connected road infrastructure is accelerating the deployment of cameras, sensors, ANPR/ALPR, edge AI, V2X communication, and predictive safety analytics. However, fragmented infrastructure, integration with legacy traffic systems, regulatory and data-privacy requirements, high deployment costs, and interoperability challenges remain important constraints to large-scale adoption.
"Government & municipalities segment to hold the largest market share"
Government agencies and municipalities are key adopters of road safety solutions. They play a major role, from running awareness programs to managing and deploying comprehensive safety infrastructure and enforcement systems. Governments and municipalities represent the backbone of the road safety market as both regulators and implementers of safety policy. They can influence public safety at scale through funding and programs. They enforce compliance with legislation; however, they also allocate budgets for infrastructure upgrades. They are accountable for maintaining traffic signals and signs on roadways, but also deploy advanced systems like cameras for red-light and speed enforcement, use AI to counter violations, and deploy real-time traffic management systems. In November 2024, the city of Brampton in Canada worked with Jenoptik to deploy over 180 automated speed enforcement cameras to improve the compliance rate in school zones.
"By integrated solution, incident detection & response to account for fastest growth during the forecast period"
The incident detection and response segment is a significant category within the road safety market, focusing on quickly detecting traffic incidents and swiftly informing emergency service providers to reduce injuries, fatalities, and traffic disruption. The incident detection and response segment integrates smart surveillance, communications infrastructure, and automated responses to improve roadway safety and reduce response times in accidents or dangerous situations. This incident detection & response segment will reduce road fatalities, enabling emergency services to analyze documentation and mitigate risks through early intervention. By reducing road fatalities, the incident detection & response segment will also reduce delays and congestion from accidents and improve overall traffic efficiency. The incident detection and response segment of road safety offers value as a building block for Vision Zero, intelligent transport systems (ITS), and autonomous vehicle readiness, making it a high-growth segment of the global road safety ecosystem.
"North America leads in market share while Asia Pacific emerges as the fastest-growing region in the road safety market"
North America currently holds the largest market share in the Road safety market, driven by widespread digital adoption, smart infrastructure technologies, and the presence of major road safety vendors. Governments in North America are introducing programs such as Vision Zero, the US National Roadway Safety Strategy (NRSS), and Canada's Road Safety Strategy 2025, which prioritize safer road users, safer vehicles, and smarter infrastructure. The US Department of Transportation is also encouraging road-safety innovation through its Safe Streets and Roads for All (SS4A) program, backed by USD 5 billion to implement AI-based enforcement programs, deploy automated speed cameras, and install smart traffic signals and pedestrian protections. The Asia-Pacific (APAC) region is emerging as the fastest-growing region in the global road safety landscape as it continues to urbanize, with rising motorization rates and growing government efforts to curb road traffic fatalities. In line with this, countries like India, China, Japan, South Korea, and Australia are leading the way with their large investments in intelligent transportation systems (ITS), evolving smart city programs, and traffic enforcement technologies.
Breakdown of Primaries
In-depth interviews were conducted with Chief Executive Officers (CEOs), innovation and technology directors, system integrators, and executives from various key organizations operating in the road safety market.
- By Company: Tier I - 34%, Tier II - 43%, and Tier III - 23%
- By Designation: C-Level Executives - 50%, D-Level Executives -30%, and others - 20%
- By Region: North America - 30%, Europe - 30%, Asia Pacific - 25%, Middle East & Africa - 10%, and Latin America - 5%
The report studies key players in the road safety market. It profiles major vendors in the road safety market. The major market players include JENOPTIK (Germany), Kapsch TrafficCom (Austria), Sensys Gatso Group (Sweden), IDEMIA (France), Teledyne FLIR (US), Motorola Solutions (US), Verra Mobility (US), SWARCO (Austria), Siemens (Germany), Cubic Corporation (US), Conduent (US), VITRONIC (Germany), Dahua Technology (China), Laser Technology (US), Traffic Management Technology (South Africa), Truvelo (UK), Kria (Italy), Syntell (South Africa), Clearview Intelligence (UK), Simicon (Russia), FRED Engineering (Italy), Kodiak Robotics (US), Humanising Autonomy (UK), Vebit AI (US), Connected Wise LLC (US), Saferoad (Germany), LiveRoad Analytics (US), Acusensus (Australia), Valerann (UK), NoTraffic (Israel), and Vivacity (UK).
Research Coverage
This research report categorizes the Road safety market based on offering (solutions (integrated solutions (enforcement solution, incident detection & response, ALPR/ANPR, traffic monitoring & control, pedestrian safety, connected & cooperative road safety), and standalone solutions (hardware and software)) and services), enforcement type (automated, manual, or hybrid), application (violation management, traffic optimization, accident prevention, emergency response, and public awareness & training, pedestrian & VRU protection, work zone safety management, insurance risk assessment), end user (government & municipalities, highway authorities, law enforcement agencies, private toll operators, smart city integrators, construction companies, others (fleet operators and insurance providers)), and region (North America, Europe, Asia Pacific, Middle East & Africa, and Latin America). The report covers detailed information on major factors, such as drivers, restraints, challenges, and opportunities, influencing the growth of the road safety market. A detailed analysis of key industry players provides insights into their business overview, solutions, and services; key strategies; contracts, partnerships, agreements, new product & service launches, and mergers and acquisitions; and recent developments in the road safety market. This report also covers a competitive analysis of upcoming startups in the road safety market ecosystem.
Key Benefits of Buying the Report
The report would provide the market leaders/new entrants in this market with information on the closest approximations of the revenue numbers for the overall road safety market and its subsegments. It would help stakeholders understand the competitive landscape and gain more insights to better their business and plan suitable go-to-market strategies. It also helps stakeholders understand the market pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insights on the following pointers:
- Analysis of key drivers (Increasing government focus on reducing road fatalities and serious injuries; growing deployment of automated speed and red-light enforcement; rising adoption of AI-powered video analytics, ANPR/ALPR, and intelligent sensing; increasing investments in connected road infrastructure, V2X, and real-time incident detection; growing demand for pedestrian, cyclist, and work-zone safety solutions), restraints (High upfront investment and operating costs for advanced road-safety infrastructure; fragmented and aging traffic-management infrastructure; interoperability challenges across cameras, sensors, communications, and legacy systems; regulatory, privacy, and data-governance requirements; limited technical expertise and maintenance capabilities in some jurisdictions), opportunities (Expansion of AI-enabled predictive road-safety analytics and proactive accident prevention; growing deployment of connected intersections and V2X-based safety applications; increasing demand for vulnerable road-user and work-zone protection; expansion of automated enforcement into mobile-phone, seatbelt, average-speed, and other unsafe-driving violations; increasing adoption of managed services and integrated road-safety platforms), and challenges (Ensuring accuracy and reliability of AI-based detection systems under varying weather, lighting, and traffic conditions; addressing cybersecurity and privacy risks associated with connected cameras, vehicles, and infrastructure; securing public acceptance of automated enforcement and data collection; maintaining interoperability across multiple vendors and technologies; and demonstrating measurable safety outcomes while managing complex, large-scale deployments).
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and product & service launches in the road safety market.
- Market Development: Comprehensive information about lucrative markets - the report analyzes the road safety market across varied regions.
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the road safety market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies and product portfolios of JENOPTIK (Germany), Kapsch TrafficCom (Austria), Sensys Gatso Group (Sweden), IDEMIA (France), Teledyne FLIR (US), Motorola Solutions (US), Verra Mobility (US), SWARCO (Austria), Siemens (Germany), and Cubic Corporation (US), among others, in the road safety market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION AND SCOPE
- 1.2.1 INCLUSIONS AND EXCLUSIONS
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN ROAD SAFETY MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES IN ROAD SAFETY MARKET
- 3.2 ROAD SAFETY MARKET, BY REGION
- 3.3 ROAD SAFETY MARKET: TOP THREE END USERS
- 3.4 NORTH AMERICA: ROAD SAFETY MARKET, BY OFFERING AND ENFORCEMENT TYPE
- 3.5 ROAD SAFETY MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing government focus on reducing road fatalities and serious injuries
- 4.2.1.2 Growing deployment of automated speed and red-light enforcement
- 4.2.1.3 Rising adoption of AI-powered video analytics, ANPR/ALPR, and intelligent sensing
- 4.2.1.4 Increasing investments in connected road infrastructure, V2X, and real-time incident detection
- 4.2.2 RESTRAINTS
- 4.2.2.1 High upfront investment and operating costs for advanced road-safety infrastructure
- 4.2.2.2 Fragmented and aging traffic-management infrastructure
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expansion of AI-enabled predictive road-safety analytics and proactive accident prevention
- 4.2.3.2 Growing deployment of connected intersections and V2X-based safety applications
- 4.2.3.3 Increasing demand for vulnerable road-users and work-zone protection
- 4.2.4 CHALLENGES
- 4.2.4.1 Ensuring accuracy and reliability of AI-based detection systems under varying weather, lighting, and traffic conditions
- 4.2.4.2 Addressing cybersecurity and privacy risks associated with connected cameras, vehicles, and infrastructure
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN ROAD SAFETY MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 EVOLUTION OF ROAD SAFETY
- 5.2 PORTER'S FIVE FORCES ANALYSIS
- 5.2.1 THREAT OF NEW ENTRANTS
- 5.2.2 THREAT OF SUBSTITUTES
- 5.2.3 BARGAINING POWER OF SUPPLIERS
- 5.2.4 BARGAINING POWER OF BUYERS
- 5.2.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.3 MACROECONOMIC OUTLOOK
- 5.3.1 INTRODUCTION
- 5.3.2 GDP TRENDS AND FORECAST
- 5.3.3 TRENDS IN THE GLOBAL ROAD SAFETY DATA INDUSTRY
- 5.3.4 TRENDS IN GLOBAL ARTIFICIAL INTELLIGENCE INDUSTRY
- 5.4 SUPPLY CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.5.1 AUTOMATED ENFORCEMENT & ROAD SAFETY HARDWARE
- 5.5.2 ROAD SAFETY SOFTWARE & ANALYTICS
- 5.5.3 MANAGED ENFORCEMENT & ROAD SAFETY SERVICES
- 5.5.4 INTELLIGENT TRAFFIC MANAGEMENT & CONNECTED ROAD SAFETY
- 5.5.5 SPECIALIZED ROAD SAFETY & ENFORCEMENT SOLUTIONS
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE OF OFFERINGS, BY KEY PLAYER, 2026
- 5.6.2 INDICATIVE PRICING ANALYSIS, BY APPLICATION, 2026
- 5.7 TRADE ANALYSIS
- 5.7.1 EXPORT SCENARIO OF ROAD-SAFETY AND TRAFFIC-CONTROL EQUIPMENT (HSN: 853080)
- 5.7.2 IMPORT SCENARIO OF ROAD-SAFETY AND TRAFFIC-CONTROL EQUIPMENT (HSN: 853080)
- 5.8 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.9 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.10 INVESTMENT AND FUNDING SCENARIO
- 5.11 CASE STUDY ANALYSIS
- 5.11.1 SENSYS GATSO DEPLOYED RAPID SPEED ENFORCEMENT AT THE HARINGVLIETBRIDGE
- 5.11.2 JENOPTIK IMPROVED ROAD SAFETY THROUGH AUTOMATED SPEED ENFORCEMENT IN NEW YORK
- 5.11.3 ACUSENSUS ENABLED MOBILE-PHONE AND SEATBELT ENFORCEMENT IN QUEENSLAND
- 5.11.4 KAPSCH ENABLED CONNECTED ROAD SAFETY THROUGH C-ITS IN INDIA
- 5.11.5 DERQ DEPLOYED AI-BASED INTERSECTION SAFETY ANALYTICS IN FREMONT
- 5.11.6 HAYDEN AI IMPROVED ROAD SAFETY THROUGH AUTOMATED BIKE-LANE ENFORCEMENT
- 5.11.7 NOTRAFFIC IMPROVED INTERSECTION SAFETY AND REDUCED RED-LIGHT RUNNING IN PHOENIX
- 5.11.8 VITRONIC IMPLEMENTED MANAGED AUTOMATED TRAFFIC ENFORCEMENT IN MONTGOMERY COUNTY
- 5.12 IMPACT OF 2025 US TARIFF - ROAD SAFETY MARKET
- 5.12.1 INTRODUCTION
- 5.12.1.1 Tariff/Trade Policy Updates (June-August 2026)
- 5.12.2 KEY TARIFF RATES
- 5.12.3 PRICE IMPACT ANALYSIS
- 5.12.3.1 Strategic shifts and emerging trends
- 5.12.4 IMPACT ON COUNTRY/REGION
- 5.12.4.1 US
- 5.12.4.2 China
- 5.12.4.3 Europe
- 5.12.4.4 Asia Pacific (excluding China)
- 5.12.5 IMPACT ON END-USE INDUSTRIES
- 5.12.1 INTRODUCTION
6 TECHNOLOGICAL ADVANCEMENTS, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 AI-BASED COMPUTER VISION & VIDEO ANALYTICS
- 6.1.2 LIDAR, RADAR & ADVANCED SENSING
- 6.1.3 AUTOMATED NUMBER PLATE RECOGNITION (ANPR/ALPR)
- 6.1.4 ROADSIDE & VEHICLE-MOUNTED SENSORS
- 6.1.5 ADVANCED TRAFFIC ENFORCEMENT SYSTEMS
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 GLOBAL NAVIGATION SATELLITE SYSTEMS (GNSS) & HIGH-PRECISION POSITIONING
- 6.2.2 EDGE COMPUTING & EDGE AI
- 6.2.3 CLOUD COMPUTING & DATA ANALYTICS
- 6.2.4 ROAD WEATHER INFORMATION SYSTEMS (RWIS)
- 6.2.5 GEOSPATIAL & DIGITAL MAPPING TECHNOLOGIES
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 ADVANCED DRIVER ASSISTANCE SYSTEMS (ADAS)
- 6.3.2 CONNECTED & AUTOMATED VEHICLES (CAV)
- 6.3.3 INTELLIGENT TRANSPORTATION SYSTEMS (ITS)
- 6.3.4 COOPERATIVE ADAPTIVE CRUISE CONTROL (CACC)
- 6.3.5 TRAFFIC MANAGEMENT & ADAPTIVE SIGNAL CONTROL
- 6.4 TECHNOLOGY ROADMAP
- 6.5 PATENT ANALYSIS
- 6.5.1 METHODOLOGY
- 6.5.2 PATENTS FILED, BY DOCUMENT TYPE, 2016-2026
- 6.5.3 INNOVATION AND PATENT APPLICATIONS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 AUTONOMOUS ROAD SAFETY OPERATIONS
- 6.6.2 INTELLIGENT ROAD SAFETY ENGINEERING
- 6.6.3 REAL-TIME MULTIMODAL RISK MONITORING
- 6.6.4 PREDICTIVE ROAD SAFETY & RISK ANALYTICS
- 6.6.5 CONNECTED & COOPERATIVE ROAD SAFETY OPERATIONS
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 KEY REGULATIONS
- 7.1.2.1 North America
- 7.1.2.1.1 National Roadway Safety Strategy (US)
- 7.1.2.1.2 Speed Safety Camera Enforcement (US)
- 7.1.2.2 Europe
- 7.1.2.2.1 EU Road Safety Policy Framework 2021-2030
- 7.1.2.2.2 General Safety Regulation (EU) 2019/2144
- 7.1.2.2.3 Road Infrastructure Safety Management Directive (EU)
- 7.1.2.3 Asia Pacific
- 7.1.2.3.1 Electronic Monitoring and Enforcement of Road Safety (India)
- 7.1.2.3.2 12th Basic Plan for Traffic Safety Measures (Japan)
- 7.1.2.3.3 Law on Road Traffic Safety (China)
- 7.1.2.4 Middle East & Africa
- 7.1.2.4.1 Saudi Road Code (Saudi Arabia)
- 7.1.2.4.2 National Road Traffic Act (South Africa)
- 7.1.2.5 Latin America
- 7.1.2.5.1 Brazilian Traffic Code (Brazil)
- 7.1.2.5.2 Federal Traffic Regulation for Roads and Bridges (Mexico)
- 7.1.2.1 North America
- 7.1.3 INDUSTRY STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS INDUSTRY END USERS
9 ROAD SAFETY MARKET, BY OFFERING
- 9.1 INTRODUCTION
- 9.2 SOLUTIONS
- 9.2.1 INCREASING GOVERNMENT FOCUS ON REDUCING ROAD FATALITIES AND SERIOUS INJURIES
- 9.2.2 INTEGRATED SOLUTIONS
- 9.2.2.1 Enforcement solutions
- 9.2.2.1.1 Speed enforcement systems
- 9.2.2.1.2 Red light enforcement
- 9.2.2.1.3 Seat belt & mobile phone enforcement
- 9.2.2.1.4 DUI enforcement
- 9.2.2.1.5 Temporary speed enforcement
- 9.2.2.1.6 Work-zone & road-worker safety enforcement
- 9.2.2.2 ALPR/ANPR
- 9.2.2.2.1 Fixed alpr systems
- 9.2.2.2.2 Mobile alpr systems
- 9.2.2.2.3 Portable alpr
- 9.2.2.2.4 AI-powered alpr analytics
- 9.2.2.2.5 AI-based vehicle identification & classification
- 9.2.2.3 Incident detection and response
- 9.2.2.3.1 Violation detection
- 9.2.2.3.2 Accident detection
- 9.2.2.3.3 Emergency vehicle preemption and notification
- 9.2.2.3.4 Congestion/queue detection
- 9.2.2.3.5 Driver behavior monitoring systems
- 9.2.2.3.6 AI-based safety & risk analytics
- 9.2.2.4 Traffic monitoring & control
- 9.2.2.4.1 Smart traffic signals
- 9.2.2.4.2 Variable message signs
- 9.2.2.4.3 Road weather information systems (RWIS)
- 9.2.2.4.4 Dynamic lane management
- 9.2.2.4.5 Connected & adaptive safety infrastructure
- 9.2.2.5 Pedestrian safety
- 9.2.2.5.1 Smart crosswalks
- 9.2.2.5.2 VRU detection
- 9.2.2.5.3 Pedestrian alert system
- 9.2.2.5.4 Cyclist & micromobility detection
- 9.2.2.5.5 VRU detection & analytics
- 9.2.2.6 Connected & cooperative road safety
- 9.2.2.6.1 V2V safety systems
- 9.2.2.6.2 V2I safety systems
- 9.2.2.6.3 V2X road-hazard warning
- 9.2.2.6.4 Connected intersection safety
- 9.2.2.6.5 Emergency vehicle connectivity
- 9.2.2.1 Enforcement solutions
- 9.2.3 STANDALONE SOLUTIONS
- 9.2.3.1 Hardware
- 9.2.3.1.1 Cameras
- 9.2.3.1.2 Sensors
- 9.2.3.1.3 Smart signs & signals
- 9.2.3.1.4 Roadside units (RSUS)
- 9.2.3.1.5 Other hardware
- 9.2.3.2 Software
- 9.2.3.2.1 Violation detection engines
- 9.2.3.2.2 AI/ML analytics platform
- 9.2.3.2.3 LPR/OCR recognition software
- 9.2.3.2.4 Command & simulation tools
- 9.2.3.2.5 Other software
- 9.2.3.1 Hardware
- 9.3 SERVICES
- 9.3.1 OFFER PROFESSIONAL AND MANAGED SERVICES FOR INSTALLATION, COMMISSIONING, CALIBRATION, AND FUNCTIONAL TESTING OF CRITICAL ROAD SAFETY EQUIPMENT
- 9.3.2 PROFESSIONAL SERVICES
- 9.3.2.1 Consulting
- 9.3.2.2 System integration
- 9.3.2.3 Training
- 9.3.2.4 Road safety audits
- 9.3.3 MANAGED SERVICES
- 9.3.3.1 Outsourced operations
- 9.3.3.2 System maintenance
- 9.3.3.3 Analytics as a service
- 9.3.3.4 Back-office processing
10 ROAD SAFETY MARKET, BY ENFORCEMENT TYPE
- 10.1 INTRODUCTION
- 10.1.1 ENFORCEMENT TYPE: ROAD SAFETY MARKET DRIVERS
- 10.2 AUTOMATED ENFORCEMENT
- 10.2.1 DEPLOYING INTELLIGENT TECHNOLOGY-DRIVEN SYSTEMS TO ENABLE CONTINUOUS, UNBIASED, AND FULLY AUTOMATED ENFORCEMENT OF TRAFFIC VIOLATIONS ACROSS DIVERSE ENVIRONMENTS
- 10.3 MANUAL ENFORCEMENT
- 10.3.1 CONDUCTING FIELD-LEVEL ENFORCEMENT OPERATIONS THROUGH HUMAN INTERVENTION TO ENSURE REGULATORY COMPLIANCE AND ADDRESS SITUATIONAL ROAD SAFETY CHALLENGES
- 10.4 HYBRID ENFORCEMENT
- 10.4.1 ENSURE RELIABLE, FLEXIBLE, AND REAL-TIME AI DELIVERY WITH ADVANCED MODEL DEPLOYMENT AND SERVING FUNCTIONALITIES
11 ROAD SAFETY MARKET, BY APPLICATION
- 11.1 INTRODUCTION
- 11.1.1 APPLICATION: ROAD SAFETY MARKET DRIVERS
- 11.2 VIOLATION MANAGEMENT
- 11.2.1 IMPLEMENTING INTELLIGENT ROAD SAFETY SOLUTIONS TO AUTOMATE VIOLATION DETECTION AND STREAMLINE CITATION PROCESSING FOR SAFER ROAD NETWORKS
- 11.3 TRAFFIC OPTIMIZATION
- 11.3.1 USING DATA-DRIVEN CONTROL STRATEGIES AND REAL-TIME OPTIMIZATION TECHNOLOGIES TO REDUCE CONGESTION AND ENHANCE MOBILITY ACROSS URBAN ROAD NETWORKS
- 11.4 ACCIDENT PREVENTION
- 11.4.1 DEPLOYING PREDICTIVE ANALYTICS AND ENVIRONMENTAL SENSING TECHNOLOGIES TO IDENTIFY RISK ZONES AND IMPLEMENT PROACTIVE MEASURES
- 11.5 EMERGENCY RESPONSE
- 11.5.1 ENABLING ACCELERATED INCIDENT DETECTION AND REAL-TIME COORDINATION OF EMERGENCY SERVICES TO REDUCE RESPONSE TIME
- 11.6 DRIVER BEHAVIOR MONITORING
- 11.6.1 LEVERAGING IN-VEHICLE ANALYTICS AND SENSOR FUSION TO TRACK AND CORRECT UNSAFE DRIVING BEHAVIORS FOR LONG-TERM BEHAVIORAL CHANGE AND CRASH REDUCTION
- 11.7 PUBLIC AWARENESS/TRAINING
- 11.7.1 PROMOTING ROAD SAFETY CULTURE THROUGH IMMERSIVE AWARENESS PROGRAMS AND STRUCTURED TRAINING
- 11.8 PEDESTRIAN & VRU PROTECTION
- 11.8.1 INTEGRATING SMART INFRASTRUCTURE AND DETECTION SYSTEMS TO SAFEGUARD PEDESTRIANS AND VULNERABLE ROAD USERS THROUGH REAL-TIME ALERTS
- 11.9 WORK ZONE SAFETY MANAGEMENT
- 11.9.1 ENHANCING SAFETY IN ACTIVE WORK ZONES BY DEPLOYING CONNECTED ENFORCEMENT SYSTEMS AND DYNAMIC WARNINGS TO PREVENT COLLISIONS AND PROTECT ROAD CREWS
- 11.10 INSURANCE RISK ASSESSMENT
- 11.10.1 UTILIZING BEHAVIORAL ANALYTICS AND TELEMATICS TO ACCURATELY ASSESS DRIVER RISK PROFILES AND INFORM DYNAMIC, USAGE-BASED INSURANCE AND SAFETY STRATEGIES
12 ROAD SAFETY MARKET, BY END USER
- 12.1 INTRODUCTION
- 12.1.1 END USER: ROAD SAFETY MARKET DRIVERS
- 12.2 GOVERNMENT & MUNICIPALITIES
- 12.2.1 GOVERNMENTS AND MUNICIPALITIES LEAD ROAD SAFETY EFFORTS THROUGH FUNDING, REGULATION, AND SMART CITY INITIATIVES
- 12.3 HIGHWAY AUTHORITIES
- 12.3.1 HIGHWAY AUTHORITIES ADOPT SMART INFRASTRUCTURE TO ENSURE SAFETY ON HIGH-SPEED ROAD NETWORKS
- 12.4 LAW ENFORCEMENT AGENCIES
- 12.4.1 LAW ENFORCEMENT AGENCIES EMBRACE SURVEILLANCE AND ANALYTICS TO MONITOR AND CONTROL TRAFFIC VIOLATIONS
- 12.5 PRIVATE TOLL OPERATORS
- 12.5.1 TOLL OPERATORS INVEST IN INTELLIGENT SYSTEMS TO ENSURE SAFE, EFFICIENT, AND COMPLIANT ROAD USAGE
- 12.6 SMART CITY INTEGRATORS
- 12.6.1 SMART CITY INTEGRATORS EMBED ROAD SAFETY WITHIN BROADER URBAN DIGITAL INFRASTRUCTURE
- 12.7 CONSTRUCTION COMPANIES
- 12.7.1 CONSTRUCTION FIRMS IMPLEMENT SAFETY PROTOCOLS AND TECHNOLOGIES ACROSS ROAD DEVELOPMENT PHASES
- 12.8 OTHER END USERS
13 ROAD SAFETY MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 NORTH AMERICA: ROAD SAFETY MARKET DRIVERS
- 13.2.2 US
- 13.2.2.1 Institutionalizing cross-sector data integration and predictive enforcement to scale vision zero across diverse urban and rural mobility ecosystems
- 13.2.3 CANADA
- 13.2.3.1 Align safety modernization with climate goals through municipal co-funding, open data mandates, and community-based AI enforcement
- 13.3 EUROPE
- 13.3.1 EUROPE: ROAD SAFETY MARKET DRIVERS
- 13.3.2 UK
- 13.3.2.1 UK's nationwide deployment of AI-powered speed enforcement, smart crossings, and connected mobility zones for driving toward zero fatalities
- 13.3.3 GERMANY
- 13.3.3.1 Germany scaling road safety through V2X integration, dynamic lane controls, and urban zero-vision zones
- 13.3.4 FRANCE
- 13.3.4.1 France's tech-driven road safety surge expanding autonomous radar networks, smart signage, and urban speed harmonization
- 13.3.5 ITALY
- 13.3.5.1 Italy is building safer streets through urban ITS deployment, smart crosswalks, and behavioral analytics to protect vulnerable road users
- 13.3.6 SPAIN
- 13.3.6.1 Spain's smart enforcement strategy scaling intelligent cameras, real-time incident detection, and speed harmonization for safer mobility
- 13.3.7 REST OF EUROPE
- 13.4 ASIA PACIFIC
- 13.4.1 ASIA PACIFIC: ROAD SAFETY MARKET DRIVERS
- 13.4.2 CHINA
- 13.4.2.1 China scales AI-driven enforcement in tier-2/3 cities
- 13.4.3 JAPAN
- 13.4.3.1 Japan is deploying smart crosswalks with embedded LED alerts and pedestrian protection systems
- 13.4.4 INDIA
- 13.4.4.1 Accelerating road safety transformation through data-driven enforcement and public-private innovation
- 13.4.5 AUSTRALIA & NEW ZEALAND
- 13.4.5.1 Pioneering smart safety through predictive analytics and digital infrastructure for zero fatality roads
- 13.4.6 SOUTH KOREA
- 13.4.6.1 Korea driving vision zero through AI-powered pedestrian safety and urban intelligence
- 13.4.7 REST OF ASIA PACIFIC
- 13.5 MIDDLE EAST & AFRICA
- 13.5.1 MIDDLE EAST & AFRICA: ROAD SAFETY MARKET DRIVERS
- 13.5.2 MIDDLE EAST & AFRICA: MACROECONOMIC OUTLOOK
- 13.5.3 KSA
- 13.5.3.1 Drive holistic integration of AI, infrastructure, and enforcement under Vision 2030 mobility goals
- 13.5.4 UNITED ARAB EMIRATES (UAE)
- 13.5.4.1 Expand interoperable urban safety platforms leveraging AI, V2X, and municipal data integration
- 13.5.5 SOUTH AFRICA
- 13.5.5.1 Expand multi-layered safety programs integrating enforcement, education, and urban design in high-risk zones
- 13.5.6 REST OF MIDDLE EAST & AFRICA
- 13.6 LATIN AMERICA
- 13.6.1 LATIN AMERICA: ROAD SAFETY MARKET DRIVERS
- 13.6.2 BRAZIL
- 13.6.2.1 Modernize legacy enforcement networks through regionalized, data-centric road safety platforms
- 13.6.3 MEXICO
- 13.6.3.1 Expand municipal safety intelligence systems to address VRU vulnerability and informal transit risks
- 13.6.4 ARGENTINA
- 13.6.4.1 Strengthen data-driven enforcement and crash analytics amid institutional decentralization
- 13.6.5 REST OF LATIN AMERICA
14 COMPETITIVE LANDSCAPE
- 14.1 OVERVIEW
- 14.2 KEY PLAYER STRATEGIES, 2025-2026
- 14.3 REVENUE ANALYSIS, 2021-2025
- 14.4 MARKET SHARE ANALYSIS, 2025
- 14.4.1 MARKET RANKING ANALYSIS, 2025
- 14.5 PRODUCT COMPARATIVE ANALYSIS
- 14.5.1 PRODUCT COMPARATIVE ANALYSIS, BY HARDWARE (ROAD SAFETY)
- 14.5.1.1 TruSpeed Laser (Laser Technology)
- 14.5.1.2 Redflex RadarCam (Traffic Management Technologies)
- 14.5.1.3 Camera-Based Speed System (Syntell)
- 14.5.1.4 Gatso T-Series (Sensys Gatso Group)
- 14.5.2 PRODUCT COMPARATIVE ANALYSIS, BY SOFTWARE (ROAD SAFETY)
- 14.5.2.1 TRIPS Platform (FRED Engineering)
- 14.5.2.2 Behavioral AI (Humanising Autonomy)
- 14.5.2.3 SafeCam AI (Vebits AI)
- 14.5.2.4 FLUX, PULS, and XILIUM (Sensys Gatso Group)
- 14.5.1 PRODUCT COMPARATIVE ANALYSIS, BY HARDWARE (ROAD SAFETY)
- 14.6 COMPANY EVALUATION MATRIX: KEY PLAYERS (INTEGRATED SOLUTIONS), 2025
- 14.6.1 STARS
- 14.6.2 EMERGING LEADERS
- 14.6.3 PERVASIVE PLAYERS
- 14.6.4 PARTICIPANTS
- 14.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 14.6.5.1 Company Footprint
- 14.6.5.2 Regional Footprint
- 14.6.5.3 Offering Footprint
- 14.6.5.4 Application Footprint
- 14.6.5.5 End User Footprint
- 14.7 COMPANY EVALUATION MATRIX: KEY PLAYERS (STANDALONE SOLUTIONS - HARDWARE PROVIDERS), 2025
- 14.7.1 STARS
- 14.7.2 EMERGING LEADERS
- 14.7.3 PERVASIVE PLAYERS
- 14.7.4 PARTICIPANTS
- 14.7.5 COMPANY FOOTPRINT: HARDWARE, 2025
- 14.7.5.1 Company Footprint
- 14.7.5.2 Regional Footprint
- 14.7.5.3 Hardware Footprint
- 14.7.5.4 Application Footprint
- 14.7.5.5 End User Footprint
- 14.8 COMPANY EVALUATION MATRIX: KEY PLAYERS (STANDALONE SOLUTIONS - SOFTWARE PROVIDERS), 2025
- 14.8.1 STARS
- 14.8.2 EMERGING LEADERS
- 14.8.3 PERVASIVE PLAYERS
- 14.8.4 PARTICIPANTS
- 14.8.5 COMPANY FOOTPRINT: SOFTWARE PROVIDERS, 2025
- 14.8.5.1 Company Footprint
- 14.8.5.2 Regional Footprint
- 14.8.5.3 Software Footprint
- 14.8.5.4 Application Footprint
- 14.8.5.5 End User Footprint
- 14.9 COMPANY VALUATION AND FINANCIAL METRICS
- 14.10 COMPETITIVE SCENARIO AND TRENDS
- 14.10.1 PRODUCT LAUNCHES AND ENHANCEMENTS
- 14.10.2 DEALS
15 COMPANY PROFILES
- 15.1 MAJOR PLAYERS
- 15.1.1 JENOPTIK
- 15.1.1.1 Business overview
- 15.1.1.2 Products/Solutions/Services offered
- 15.1.1.3 Recent developments
- 15.1.1.3.1 Product launches and enhancements
- 15.1.1.3.2 Deals
- 15.1.1.4 MNM view
- 15.1.1.4.1 Key strengths/Right to win
- 15.1.1.4.2 Strategic choices
- 15.1.1.4.3 Weaknesses and competitive threats
- 15.1.2 KAPSCH TRAFFICCOM
- 15.1.2.1 Business overview
- 15.1.2.2 Products/Solutions/Services offered
- 15.1.2.3 Recent developments
- 15.1.2.3.1 Product launches and enhancements
- 15.1.2.3.2 Deals
- 15.1.2.4 MNM view
- 15.1.2.4.1 Key strengths/Right to win
- 15.1.2.4.2 Strategic choices
- 15.1.2.4.3 Weaknesses and competitive threats
- 15.1.3 SENSYS GATSO GROUP
- 15.1.3.1 Business overview
- 15.1.3.2 Products/Solutions/Services offered
- 15.1.3.3 Recent developments
- 15.1.3.3.1 Product launches and enhancements
- 15.1.3.3.2 Deals
- 15.1.3.4 MnM view
- 15.1.3.4.1 Key strengths/Right to win
- 15.1.3.4.2 Strategic choices
- 15.1.3.4.3 Weaknesses and competitive threats
- 15.1.4 VERRA MOBILITY
- 15.1.4.1 Business overview
- 15.1.4.2 Products/Solutions/Services offered
- 15.1.4.3 Recent developments
- 15.1.4.3.1 Product launches and enhancements
- 15.1.4.3.2 Deals
- 15.1.4.3.3 Others
- 15.1.4.4 MnM view
- 15.1.4.4.1 Key strengths/Right to win
- 15.1.4.4.2 Strategic choices
- 15.1.4.4.3 Weaknesses and competitive threats
- 15.1.5 TELEDYNE FLIR
- 15.1.5.1 Business overview
- 15.1.5.2 Products/Solutions/Services offered
- 15.1.5.3 Recent developments
- 15.1.5.3.1 Product launches and enhancements
- 15.1.5.3.2 Deals
- 15.1.5.4 MnM view
- 15.1.5.4.1 Right to win
- 15.1.5.4.2 Strategic choices
- 15.1.5.4.3 Weaknesses and competitive threats
- 15.1.6 MOTOROLA SOLUTIONS
- 15.1.6.1 Business overview
- 15.1.6.2 Products/Solutions/Services offered
- 15.1.6.3 Recent developments and enhancements
- 15.1.6.3.1 Product launches and enhancements
- 15.1.6.3.2 Deals
- 15.1.6.3.3 Others
- 15.1.7 IDEMIA
- 15.1.7.1 Business overview
- 15.1.7.2 Products/Solutions/Services offered
- 15.1.7.3 Recent developments
- 15.1.7.3.1 Product launches and enhancements
- 15.1.7.3.2 Deals
- 15.1.8 SWARCO
- 15.1.8.1 Business overview
- 15.1.8.2 Products/Solutions/Services offered
- 15.1.8.3 Recent developments
- 15.1.8.3.1 Product launches and enhancements
- 15.1.8.3.2 Deals
- 15.1.9 VITRONIC
- 15.1.9.1 Business overview
- 15.1.9.2 Products/Solutions/Services offered
- 15.1.9.3 Recent developments
- 15.1.9.3.1 Product launches and enhancements
- 15.1.9.3.2 Deals
- 15.1.10 SIEMENS
- 15.1.10.1 Business overview
- 15.1.10.2 Products/Solutions/Services offered
- 15.1.10.3 Recent developments
- 15.1.10.3.1 Product launches and enhancements
- 15.1.11 CUBIC CORPORATION
- 15.1.11.1 Business overview
- 15.1.11.2 Products/Solutions/Services offered
- 15.1.11.3 Recent developments
- 15.1.11.3.1 Product launches and enhancements
- 15.1.11.3.2 Deals
- 15.1.1 JENOPTIK
- 15.2 OTHER PLAYERS
- 15.2.1 DAHUA TECHNOLOGY
- 15.2.2 LASER TECHNOLOGY
- 15.2.3 TRAFFIC MANAGEMENT TECHNOLOGIES
- 15.2.4 TRIFOIL
- 15.2.5 KRIA
- 15.2.6 SYNTELL
- 15.2.7 TRUVELO
- 15.2.8 CLEARVIEW INTELLIGENCE
- 15.2.9 SIMICON
- 15.2.10 FRED ENGINEERING
- 15.2.11 KODIAK ROBOTICS
- 15.2.12 HUMANISING AUTONOMY
- 15.2.13 VEBITS AI
- 15.2.14 CONNECTED WISE LLC
- 15.2.15 SAFEROAD
- 15.2.16 LIVEROAD ANALYTICS
- 15.2.17 VIVACITY
- 15.2.18 NOTRAFFIC
- 15.2.19 VALERANN
- 15.2.20 ACUSENSUS
- 15.2.21 HAYDEN AI
- 15.2.22 DERQ
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.2 PRIMARY DATA
- 16.1.2.1 Breakdown of primaries
- 16.1.2.2 Key industry insights
- 16.2 MARKET BREAKUP AND DATA TRIANGULATION
- 16.3 MARKET SIZE ESTIMATION
- 16.3.1 TOP-DOWN APPROACH
- 16.3.2 BOTTOM-UP APPROACH
- 16.4 MARKET FORECAST
- 16.5 RESEARCH ASSUMPTIONS
- 16.6 RESEARCH LIMITATIONS
17 ADJACENT AND RELATED MARKETS
- 17.1 INTRODUCTION
- 17.2 INTELLIGENT TRANSPORTATION SYSTEMS (ITS) MARKET - GLOBAL FORECAST TO 2030
- 17.2.1 MARKET DEFINITION
- 17.2.2 MARKET OVERVIEW
- 17.2.2.1 Intelligent Transportation Systems (ITS) Market, By Mode
- 17.2.2.2 Intelligent Transportation Systems (ITS) Market, System Type
- 17.2.2.3 Intelligent Transportation Systems (ITS) Market, By Offering
- 17.3 TRAFFIC MANAGEMENT MARKET - GLOBAL FORECAST TO 2029
- 17.3.1 MARKET DEFINITION
- 17.3.2 MARKET OVERVIEW
- 17.3.2.1 Traffic Management Market, By Offering
- 17.3.2.2 Traffic Management Market, By Area of Application
- 17.3.2.3 Traffic Management Market, By End User
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS


