

|
시장보고서
상품코드
2158068
이온교환수지 시장 예측(-2031년) : 유형, 용도, 최종 용도 산업, 지역별lon Exchange Resins Market by Type (Cationic Resins, Anionic Resins), Application (Water, Non-Water), End-Use Industry (Power, Chemicals & Petrochemicals, Pharmaceuticals, Food & Beverage, Electrical & Electronics), and Region - Global Forecast to 2031 |
||||||

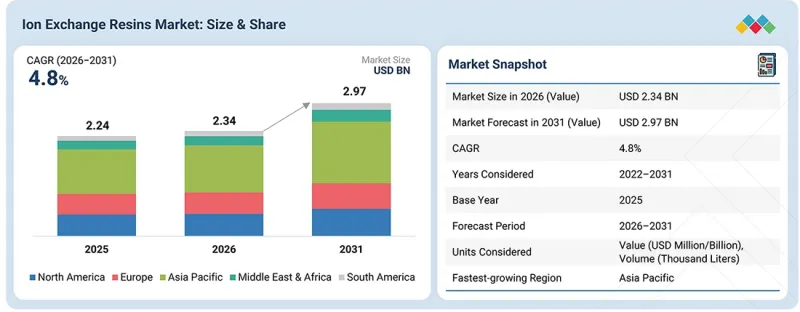
이온교환수지 시장은 2026년 23억 4,000만 달러에서 2031년까지 29억 7,000만 달러로 연평균 성장률(CAGR) 4.8%를 기록하며 확대될 것으로 전망됩니다.
이러한 성장은 지자체 및 산업 분야의 수처리·정화 수요 증가에 의해 주도되고 있습니다. 물 부족의 심화와 폐수량 증가로 인해 각 산업에서는 물 재사용이 추진되고 있습니다. 이온 교환 기술은 물의 연화, 탈염 및 용해 물질 제거를 통해 이러한 노력을 지원하고 있습니다. 발전이나 반도체 제조 등의 용도에서는 거의 절대적인 순도의 물이 요구되며, 설비를 보호하고 안정적인 공정 운영을 확보하기 위해 특수한 이온교환수지가 사용되고 있습니다. 또한 환경 규제 및 폐수 규제의 강화로 인해 기업은 물 관리 관행을 개선할 수밖에 없는 한편, 급수 품질에 대한 감시도 점점 더 엄격해지고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2022-2031년 |
| 기준 연도 | 2025 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(백만/십억 달러) 수량(천 리터) |
| 부문 | 유형, 용도, 최종 용도 산업 및 지역 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카 |
동시에, 각 제조사들은 더 높은 흡착 용량, 더 뛰어난 선택성, 효율 향상 및 특정 용도에서의 성능 향상을 실현하는 새로운 이온교환수지를 개발하고 있습니다. 이러한 발전으로 인해 더 폭넓은 산업 분야에서 채택이 촉진되고 있으며, 시장 성장이 더욱 가속화되고 있습니다.
"전기·전자 업계는 금액 기준으로 가장 빠르게 성장하는 최종 용도 산업이 될 것으로 예측됩니다."
전기·전자 산업은 여러 요인의 지원을 받아 이온교환수지 시장에서 가장 빠르게 성장하는 최종 용도 산업이 될 것으로 예측됩니다. 이 산업은 가장 성장세가 두드러진 산업 중 하나이며, 전자 부품의 신뢰성과 성능을 확보하기 위해 고순도 원자재와 공정에 크게 의존하고 있습니다. 이온교환수지는 전자 기기의 성능을 저하시킬 수 있는 하전된 금속 이온이나 유기 오염 물질 등의 불순물을 효과적으로 제거합니다. 예를 들어 반도체나 회로 기판 제조 과정에서 이온교환수지는 우수한 전도성과 반도체 성능에 필요한 순도 수준을 실현합니다. 전자 재료에 오염 물질이 포함되어 있지 않음을 보장함으로써, 전자 제품의 신뢰성과 수명을 향상시킵니다. 첨단 전자 기기에 대한 수요가 증가함에 따라 이온교환수지는 제조 공정에서 품질과 효율을 확보하는 데 있으며, 매우 중요한 역할을 하고 있습니다.
"2026년에는 상수도 용도가 수처리 용도 부문에서 금액 기준으로 가장 큰 점유율을 차지할 것으로 예상됩니다."
상수도 부문은 공공 상수도 시스템을 통해 깨끗하고 안전하며 고품질의 물을 공급함으로써 이온교환수지 시장에서 매우 중요한 역할을 수행하고 있습니다. 수처리 시설에서는 이온교환수지가 주로 물의 연화 및 탈이온화에 사용됩니다. 물 연화 처리에서는 물의 경도를 유발하는 칼슘 이온과 마그네슘 이온을 제거하고, 이를 나트륨 이온으로 대체합니다. 이를 통해 스케일 침적을 방지하고, 배관 및 가전제품의 수명을 연장할 수 있습니다. 반면, 탈이온 처리에서는 양이온교환수지와 음이온교환수지를 조합하여 사용함으로써 이온성 불순물을 사실상 모두 제거하고, 중요한 용도에 적합한 초순수를 생성합니다.
"예측 기간 중 이온교환수지 시장에서 유형별로는 양이온교환수지가 주류를 이룰 것으로 전망됩니다."
양이온교환수지는 이온교환수지 중 가장 일반적인 유형로, 수처리, 정수 및 화학 처리 분야에서 널리 사용되고 있습니다. 칼슘, 마그네슘, 철, 망간 등 양전하를 띤 이온을 제거하므로 물의 연화, 탈염 및 정수에 매우 효과적입니다. 강산성 양이온교환수지는 특히 경도를 제거하여 고순도 물을 생산하는 데 사용되는 반면, 약산성 양이온교환수지는 선택적인 이온 제거가 필요한 상황에서 사용됩니다. 수처리, 발전, 제약, 식품 및 음료, 화학 산업 등 폭넓은 분야의 실적이 안정적인 수요를 지원하고 있습니다. 처리수 및 고순도수에 대한 수요 증가에 더해, 산업화의 진전과 수질 기준의 엄격화가 맞물리면서 양이온교환수지의 채택이 더욱 가속화되고 있습니다. 그 범용성과 입증된 성능 덕분에 시장에서 확고한 지배적 지위를 굳건히 하고 있습니다.
"예측 기간 중 북미는 이온교환수지 시장에서 2위 규모의 지역이 될 것으로 예상됩니다."
북미는 전 세계 이온교환수지 시장에서 중요한 위치를 차지하고 있습니다. 해당 지역의 시장은 성숙기에 접어들었기 때문에 전력, 화학, 제약, 전기·전자 등의 최종 용도 산업에서 완만한 성장이 예상됩니다. 듀폰(미국), 에콜라보(미국), 바이오래드 래버러토리즈(미국)는 북미의 주요 기업으로, 전 세계 고객에게 서비스를 제공하고 있습니다. 이 시장의 특징은 광범위한 제품 포트폴리오를 보유한, 경쟁력이 매우 높은 대형 기업이 여러 곳 존재한다는 점입니다. 그 결과, 소규모 기업은 막대한 자본 비용이 소요되므로 연구개발이나 마케팅의 여지가 제한적입니다. 북미의 주요 기업은 시장 점유율을 확대하고 이온교환수지에 대한 수요 증가에 부응하기 위해 파트너십, 계약, 제휴, 신제품·신기술 개발, 생산 능력 확대, 신규 공장 설립 등의 전략을 채택하고 있습니다.
2차 조사를 통해 도출된 몇 가지 부문 및 하위 부문 시장 규모를 파악하고 검증하기 위해 광범위한 1차 인터뷰가 실시되었습니다.
1차 인터뷰의 내역은 다음과 같습니다. :
- 부서별: Tier 1: 40%, Tier 2: 25%, Tier 3: 35%
- 직책별: C레벨 임원: 35%, 이사: 30%, 기타: 35%
- 지역별: 북미: 25%, 유럽: 45%, 아시아태평양: 20%, 남미: 5%, 중동 및 아프리카: 5%
조사 범위
본 시장 조사는 다양한 부문에 걸친 이온교환수지 시장을 대상으로 합니다. 유형, 용도, 최종 용도 산업 및 지역별로 시장 규모와 성장 가능성을 추정하는 것을 목적으로 합니다. 또한 본 조사에는 시장의 주요 기업에 대한 상세한 경쟁 분석, 각 기업의 프로필, 제품 유형 및 사업 내용에 관한 주요 관찰 사항, 최근 동향, 그리고 이온교환수지 시장에서 입지를 강화하기 위해 채택되고 있는 주요 성장 전략도 포함되어 있습니다.
이 보고서를 구매할 때의 주요 이점
이 보고서는 이온교환수지 시장 전체 및 그 부문·하위 부문에 대해 입수 가능한 가장 정확한 매출 데이터를 제공함으로써, 시장을 선도하는 기업과 신규 진입 기업을 지원하는 데 기여할 것으로 기대됩니다. 또한 이해관계자가 시장의 경쟁 구도를 이해하고, 자사의 사업 위치를 향상시키기 위한 인사이트를 얻어 적절한 시장 진입 전략을 수립하는 데에도 도움이 됩니다. 더불어, 이 보고서는 주요 시장 촉진요인 및 과제에 대한 정보를 제공함으로써, 이해관계자가 시장 동향을 파악하는 데 일조합니다.
이 보고서는 다음 사항에 대한 인사이트를 제공합니다. :
- 주요 촉진요인(아시아태평양의 도시 인구 증가, 신흥 경제국에서의 원자력 발전 수요 확대, 그리고 엄격한 수처리 규제), 제약 요인(원자재 가격 변동 및 역삼투막 기술에 의한 경쟁), 기회(신흥 경제국에서의 산업화 진전 및 물 재이용·재순환의 중요성 증대), 그리고 과제(이온교환수지의 새로운 용도 개발 및 개발도상 지역에서의 엄격한 규제 부재)에 관한 분석
- 제품 개발/혁신: 이온교환수지 시장의 향후 기술, 연구개발 활동, 그리고 제품 및 서비스 출시에 관한 상세 인사이트
- 시장 개발: 각 지역의 이온교환수지 시장 분석을 통해 수익성이 높은 시장에 대한 포괄적인 정보를 제공합니다
- 시장 다각화: 이온교환수지 시장의 신제품·서비스, 미개발 지역, 최근 동향 및 투자에 관한 포괄적인 정보
- 경쟁 분석: 주요 기업의 시장 점유율, 성장 전략, 서비스 제공에 대한 상세한 평가
자주 묻는 질문
목차
제1장 서론
제2장 요약
제3장 주요 인사이트
- 이온교환수지 시장에서 사업자에게 매력적인 기회
- 이온교환수지 시장: 유형별
- 이온교환수지 시장: 용도별
- 이온교환수지 시장: 최종 용도 산업별
- 이온교환수지 시장: 주요 국가별
제4장 시장 개요
- 시장 역학
- 촉진요인
- 억제요인
- 기회
- 과제
- Porter's Five Forces 분석
- 대체품의 위협
- 공급업체의 협상력
- 신규 진입자의 위협
- 구매자의 협상력
- 경쟁 기업간 경쟁 관계의 격렬함
- 주요 이해관계자와 구매 기준
- 구매 과정에서 주요 이해관계자
- 구매 기준
- 밸류체인 분석
- 원자재
- 제조업체
- 유통
- 최종사용자
- 거시경제 전망
- 세계 GDP 동향
- 발전 통계
- 생태계 분석
- 사례 연구 분석
- HELLENIC PETROLEUM SA에서의 듀폰사 앰버라이트 수지 활용
- 호주 리튼에 위치한 COOGEE CHEMICALS의 염소-알칼리 브라인 정화
- PUROLITE 이온교환수지를 통한 비용 절감 및 음용수 경도 처리
- 규제 현황
- 규제기관, 정부 기관 및 기타 조직
- 기술 분석
- 주요 기술
- 보완 기술
- 인접 기술
- 고객의 사업에 영향을 미치는 동향/파괴적 혁신
- 무역 분석
- 수입 시나리오(HS 코드 391400)
- 수출 시나리오(HS 코드 391400)
- 2026-2027년 주요 회의 및 행사
- 가격 분석
- 지역별 평균 판매 가격 동향
- 유형별 평균 판매 가격 동향
- 투자 및 자금 조달 시나리오
- 특허 분석
- 특허의 법적 현황
- 관할 구역 분석
- AI/생성형 AI의 영향
- 영향 개요
제5장 이온교환수지 시장: 유형별
- 양이온교환수지
- 음이온교환수지
- 기타 유형
제6장 이온교환수지 시장: 용도별
- 물
- 물 이외
제7장 이온교환수지 시장: 최종 용도 산업별
- 전력
- 화학·석유화학
- 식품 및 음료
- 전기·전자
- 의약품
- 금속·광업
- 기타 최종 용도 산업
제8장 이온교환수지 시장: 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 프랑스
- 이탈리아
- 영국
- 스페인
- 러시아
- 네덜란드
- 기타 유럽
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- 태국
- 인도네시아
- 대만
- 기타 아시아태평양
- 중동 및 아프리카
- GCC
- 터키
- 남아프리카
- 기타 중동 및 아프리카
- 남미
- 브라질
- 아르헨티나
- 기타 남미
제9장 경쟁 현황
- 주요 진입 기업의 전략/강점, 2023-2026년
- 수익 분석, 2023-2025년
- 시장 점유율 분석(2025년)
- DUPONT
- LANXESS
- ECOLAB
- MITSUBISHI CHEMICAL GROUP CORPORATION
- SAMYANG CORPORATION
- 기업 가치 평가 및 재무 지표
- 브랜드 및 제품 비교
- 기업 평가 매트릭스: 주요 기업, 2025년
- 스타
- 신흥 리더
- 광범위한 입지를 가진 기업
- 진출 기업
- 기업의 사업 전개: 주요 기업, 2025년
- 기업 평가 매트릭스: 스타트업/중소기업, 2025년
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 경쟁사 벤치마킹: 스타트업/중소기업, 2025년
- 경쟁 시나리오
- 신제품 출시
- 거래
- 사업 확장
제10장 기업 개요
- 주요 기업
- DUPONT
- LANXESS
- ECOLAB(PUROLITE)
- MITSUBISHI CHEMICAL GROUP CORPORATION
- SAMYANG CORPORATION
- ION EXCHANGE INDIA(IEI)
- JACOBI RESINS
- THERMAX LIMITED
- OVIVO
- SUNRESIN NEW MATERIALS CO., LTD.
- 기타 주요 기업
- RESINTECH, INC.
- EVOQUA WATER TECHNOLOGIES LLC
- ALDEX CHEMICAL COMPANY, LTD.
- GFS CHEMICALS, INC.
- SUQING GROUP
- APPLEXION
- ANHUI SANXING RESIN TECHNOLOGY CO., LTD.
- RESINDION S.R.L.
- KOVALUS SEPARATION SOLUTIONS
- ACURO ORGANICS LIMITED
- WESTERN CARBON &CHEMICALS
- DOSHION POLYSCIENCE PVT. LTD.
- AQUAFILSEP
- GRAVER TECHNOLOGIES
- HYDROFLUX
제11장 조사 방법론
제12장 부록
KSA 26.11.03The ion exchange resins market is projected to grow from USD 2.34 billion in 2026 to USD 2.97 billion by 2031, at a CAGR of 4.8%. Growth is driven by rising demand for water treatment and purification across municipal and industrial sectors. Worsening water scarcity and increasing volumes of wastewater are prompting industries to adopt water reuse practices. Ion exchange technologies support these efforts through water softening, demineralization, and the removal of dissolved substances. Applications such as power generation and semiconductor manufacturing require water of near-absolute purity, and specialized ion exchange resins are used to protect equipment and ensure stable process operations. Stricter environmental and wastewater regulations are also compelling companies to improve their water management practices, while scrutiny of water supply quality continues to intensify.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) Volume (Thousand Liters) |
| Segments | Type, Application, End-use Industry, and Region |
| Regions covered | North America, Europe, Asia Pacific, South America, and Middle East & Africa |
At the same time, manufacturers are developing new ion exchange resins that offer higher capacity, greater selectivity, improved efficiency, and better performance in specific applications. These advancements are encouraging adoption across a wider range of industries, further accelerating market growth.
"The electrical & electronics end-use industry is projected to be the fastest-growing end-use industry in terms of value."
The electrical & electronics industry is projected to be the fastest-growing end-use industry in the ion exchange resins market, driven by several factors. It is among the fastest-growing industries and depends heavily on high-purity raw materials and processes to ensure the reliability and performance of electronic components. Ion exchange resins effectively remove impurities, such as charged metal ions and organic contaminants, that could compromise electronic devices. In semiconductor and circuit board manufacturing, for example, ion exchange resins deliver the purity levels required for good conductivity and semiconductor performance. By ensuring that electronic materials are free of contaminants, they enhance the reliability and service life of electronic products. With growing demand for advanced electronic devices, ion exchange resins play a vital role in ensuring quality and efficiency in the manufacturing process.
"The municipal water application is expected to account for the largest share of the water application segment in 2026 in terms of value."
The municipal water segment plays a crucial role in the ion exchange resins market by ensuring that clean, safe, and high-quality water is delivered through public water systems. In water treatment facilities, ion exchange resins are primarily used for water softening and deionization. Water softening removes the calcium and magnesium ions that cause water hardness and replaces them with sodium ions. This prevents scale buildup and extends the service life of plumbing and appliances. Deionization, by contrast, removes virtually all ionic impurities by using cation and anion exchange resins in combination, producing ultrapure water suitable for critical applications.
"Cationic resins are expected to dominate the ion exchange resins market, by type, during the forecast period."
Cationic resins are the most common type of ion exchange resins and are widely used in water treatment, purification, and chemical processing. They remove positively charged ions such as calcium, magnesium, iron, and manganese, making them highly effective for water softening, demineralization, and purification. Strong acid cationic resins are used specifically to remove hardness and produce high-purity water, while weak acid cationic resins are used where selective ion removal is required. Their proven use across the water treatment, power generation, pharmaceuticals, food & beverage, and chemical industries sustains steady demand. Rising demand for treated and high-purity water, coupled with growing industrialization and stricter water quality requirements, further supports the adoption of cationic resins. Their versatility and proven performance continue to secure their dominant market position.
"North America is expected to be the second-largest region in the ion exchange resins market during the forecast period."
North America holds a significant position in the global ion exchange resins market. The regional market is mature; hence, moderate growth is expected across end-use industries such as power, chemical, pharmaceuticals, and electrical & electronics. DuPont (US), Ecolab (US), and Bio-Rad Laboratories (US) are the major players in North America and serve customers globally. The market is characterized by the presence of several large, highly competitive players with extensive product portfolios. As a result, smaller players have limited scope for R&D and marketing due to the high capital costs involved. Major players in North America adopt strategies such as partnerships, agreements, and collaborations; new product and technology developments; capacity expansions; and new plant establishments to increase their market share and meet the growing demand for ion exchange resins.
Extensive primary interviews were conducted to determine and verify the market sizes of several segments and subsegments derived through secondary research.
The breakdown of the primary interviews is as follows:
- By Department: Tier 1: 40%, Tier 2: 25%, and Tier 3: 35%
- By Designation: C-level Executives: 35%, Directors: 30%, and Others: 35%
- By Region: North America: 25%, Europe: 45%, Asia Pacific: 20%, South America: 5%, and Middle East & Africa: 5%
DuPont (US), LANXESS (Germany), Mitsubishi Chemical Group Corporation (Japan), Samyang Corporation (South Korea), Ecolab (US), JACOBI RESINS (Sweden), Ovivo (Canada), IEI (India), Thermax Limited (India), and Sunresin New Materials Co., Ltd. (China) are among the key players in the ion exchange resins market. The study includes an in-depth competitive analysis of these key players, along with their company profiles, recent developments, and key market strategies.
Research Coverage
The market study covers the ion exchange resins market across various segments. It aims to estimate the market size and growth potential by type, application, end-use industry, and region. The study also includes an in-depth competitive analysis of key players in the market, their company profiles, key observations on their products and business offerings, recent developments, and key growth strategies adopted to improve their position in the ion exchange resins market.
Key Benefits of Buying the Report
The report is expected to help market leaders and new entrants by providing the most accurate available revenue figures for the overall ion exchange resins market and its segments and subsegments. It will also help stakeholders understand the competitive landscape of the market, gain insights to improve their businesses' positions, and plan suitable go-to-market strategies. In addition, the report helps stakeholders understand the pulse of the market by providing information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following:
- Analysis of key drivers (growing urban population in the Asia Pacific region, increasing demand for nuclear power in emerging economies, and stringent water treatment regulations), restraints (volatility in raw material prices and increasing competition from reverse osmosis membrane technology), opportunities (growing industrialization in emerging economies and the increasing importance of water recycling and reuse), and challenges (finding new applications for ion exchange resins and the lack of strict regulations in developing regions)
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product and service launches in the ion exchange resins market
- Market Development: Comprehensive information about lucrative markets through an analysis of the ion exchange resins market across various regions
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the ion exchange resins market
- Competitive Assessment: In-depth assessment of market share, growth strategies, and service offerings of leading players such as DuPont (US), LANXESS (Germany), Mitsubishi Chemical Group Corporation (Japan), Samyang Corporation (South Korea), Ecolab (US), JACOBI RESINS (Sweden), Ovivo (Canada), IEI (India), Thermax Limited (India), and Sunresin New Materials Co., Ltd. (China), among others, in the ion exchange resins market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 UNITS CONSIDERED
- 1.6 STAKEHOLDERS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN ION EXCHANGE RESINS MARKET
- 2.4 HIGH GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN ION EXCHANGE RESINS MARKET
- 3.2 ION EXCHANGE RESINS MARKET, BY TYPE
- 3.3 ION EXCHANGE RESINS MARKET, BY APPLICATION
- 3.4 ION EXCHANGE RESINS MARKET, BY END-USE INDUSTRY
- 3.5 ION EXCHANGE RESINS MARKET, BY KEY COUNTRIES
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing urban population in Asia Pacific
- 4.2.1.2 Increasing demand for nuclear power in emerging economies
- 4.2.1.3 Stringent water treatment regulations in US and Europe
- 4.2.2 RESTRAINTS
- 4.2.2.1 Volatility in raw material prices
- 4.2.2.2 Increasing competition from reverse osmosis membrane and other emerging technologies
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expansion of PFAS-selective resin applications
- 4.2.3.2 Increasing adoption of water recycling and re-use
- 4.2.4 CHALLENGES
- 4.2.4.1 Resin fouling and performance degradation
- 4.2.4.2 Complex mixed-contaminant streams
- 4.2.1 DRIVERS
- 4.3 PORTER'S FIVE FORCES ANALYSIS
- 4.3.1 THREAT OF SUBSTITUTES
- 4.3.2 BARGAINING POWER OF SUPPLIERS
- 4.3.3 THREAT OF NEW ENTRANTS
- 4.3.4 BARGAINING POWER OF BUYERS
- 4.3.5 INTENSITY OF COMPETITIVE RIVALRY
- 4.4 KEY STAKEHOLDERS AND BUYING CRITERIA
- 4.4.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 4.4.2 BUYING CRITERIA
- 4.5 VALUE CHAIN ANALYSIS
- 4.5.1 RAW MATERIAL
- 4.5.2 MANUFACTURER
- 4.5.3 DISTRIBUTION
- 4.5.4 END USER
- 4.6 MACROECONOMIC OUTLOOK
- 4.6.1 GLOBAL GDP TRENDS
- 4.6.2 POWER GENERATION STATISTICS
- 4.7 ECOSYSTEM ANALYSIS
- 4.8 CASE STUDY ANALYSIS
- 4.8.1 HELLENIC PETROLEUM SA'S USE OF DUPONT AMBERLITE RESINS
- 4.8.2 CHLOR-ALKALI BRINE PURIFICATION AT COOGEE CHEMICALS IN LYTTON, AUSTRALIA
- 4.8.3 REDUCING COSTS AND TREATING HARDNESS IN DRINKING WATER WITH PUROLITE'S ION EXCHANGE RESINS
- 4.9 REGULATORY LANDSCAPE
- 4.9.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 4.10 TECHNOLOGY ANALYSIS
- 4.10.1 KEY TECHNOLOGIES
- 4.10.1.1 Mixed bed resin
- 4.10.1.2 Chelating ion exchange resin
- 4.10.1.3 Monodisperse resin
- 4.10.2 COMPLEMENTARY TECHNOLOGIES
- 4.10.2.1 Macroreticular technology
- 4.10.2.2 Integration of ion exchange resin with solvent extraction technology
- 4.10.3 ADJACENT TECHNOLOGIES
- 4.10.3.1 Sustainable regeneration process
- 4.10.3.2 Resin-in-Pulp
- 4.10.3.3 Adsorption technologies
- 4.10.1 KEY TECHNOLOGIES
- 4.11 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 4.12 TRADE ANALYSIS
- 4.12.1 IMPORT SCENARIO (HS CODE 391400)
- 4.12.2 EXPORT SCENARIO (HS CODE 391400)
- 4.13 KEY CONFERENCES AND EVENTS, 2026-2027
- 4.14 PRICING ANALYSIS
- 4.14.1 AVERAGE SELLING PRICE TREND, BY REGION
- 4.14.2 AVERAGE SELLING PRICE TREND, BY TYPE
- 4.15 INVESTMENT AND FUNDING SCENARIO
- 4.16 PATENT ANALYSIS
- 4.16.1 LEGAL STATUS OF PATENTS
- 4.16.2 JURISDICTION ANALYSIS
- 4.17 IMPACT OF AI/GENERATIVE AI
- 4.17.1 INTRODUCTION
- 4.17.2 OVERVIEW OF IMPACT
- 4.17.2.1 Role of GenAI in transforming chemicals industry
- 4.17.2.2 Role of AI in optimizing drug discovery and ion exchange resins
- 4.17.2.3 Impact of AI on ion exchange resin management in water treatment
5 ION EXCHANGE RESINS MARKET, BY TYPE
- 5.1 INTRODUCTION
- 5.2 CATIONIC RESINS
- 5.2.1 EXTENSIVE UTILIZATION OF CATIONIC RESINS IN WATER TREATMENT APPLICATIONS TO DRIVE GROWTH
- 5.3 ANIONIC RESINS
- 5.3.1 EFFECTIVENESS IN REMOVING NEGATIVELY CHARGED IONS FROM SOLUTIONS TO DRIVE GROWTH
- 5.4 OTHER TYPES
6 ION EXCHANGE RESINS MARKET, BY APPLICATION
- 6.1 INTRODUCTION
- 6.2 WATER
- 6.2.1 GROWTH IN VARIOUS END-USE INDUSTRIES TO DRIVE MARKET
- 6.2.2 MUNICIPAL
- 6.2.3 INDUSTRIAL
- 6.2.4 OTHERS
- 6.3 NON-WATER
- 6.3.1 PHARMACEUTICALS AND CHEMICALS & PETROCHEMICALS INDUSTRIES TO DRIVE GROWTH
7 ION EXCHANGE RESINS MARKET, BY END-USE INDUSTRY
- 7.1 INTRODUCTION
- 7.2 POWER
- 7.2.1 WATER TREATMENT & PURIFICATION APPLICATION TO DRIVE GROWTH
- 7.3 CHEMICALS & PETROCHEMICALS
- 7.3.1 WIDE USE IN WATER TREATMENT, PURIFICATION, AND SEPARATION TO DRIVE GROWTH
- 7.4 FOOD & BEVERAGE
- 7.4.1 HIGH-QUALITY WATER REQUIREMENT TO DRIVE GROWTH
- 7.5 ELECTRICAL & ELECTRONICS
- 7.5.1 DEMAND FOR HIGH-PERFORMANCE ELECTRONIC COMPONENTS TO DRIVE GROWTH
- 7.6 PHARMACEUTICALS
- 7.6.1 ABILITY OF ION EXCHANGE RESINS TO FORM DRUG-RESIN COMPLEXES TO DRIVE GROWTH
- 7.7 METAL & MINING
- 7.7.1 NEED FOR WASTEWATER TREATMENT TO DRIVE GROWTH
- 7.8 OTHER END-USE INDUSTRIES
- 7.8.1 WATER TREATMENT
- 7.8.2 AGRICULTURE
- 7.8.3 TEXTILES
- 7.8.4 PAPER
- 7.8.5 OIL & GAS
8 ION EXCHANGE RESINS MARKET, BY REGION
- 8.1 INTRODUCTION
- 8.2 NORTH AMERICA
- 8.2.1 US
- 8.2.1.1 PFAS remediation and high-purity water requirements to drive the market
- 8.2.2 CANADA
- 8.2.2.1 Municipal water infrastructure upgrades to drive the market
- 8.2.3 MEXICO
- 8.2.3.1 Desalination and industrial water treatment to drive the market
- 8.2.1 US
- 8.3 EUROPE
- 8.3.1 GERMANY
- 8.3.1.1 Chemical industry, ultrapure water, industrial demineralization to drive market
- 8.3.2 FRANCE
- 8.3.2.1 Nuclear power water treatment and radioactive resin management to drive market
- 8.3.3 ITALY
- 8.3.3.1 Spent nuclear resin treatment and industrial water purification to drive market
- 8.3.4 UK
- 8.3.4.1 Nuclear wastewater treatment and PFAS removal requirements to drive market
- 8.3.5 SPAIN
- 8.3.5.1 Surge in demand for desalinated water to drive growth
- 8.3.6 RUSSIA
- 8.3.6.1 Presence of large power industry to drive growth
- 8.3.7 NETHERLANDS
- 8.3.7.1 Increasing demand for pure water across various end-use industries to drive growth
- 8.3.8 REST OF EUROPE
- 8.3.1 GERMANY
- 8.4 ASIA PACIFIC
- 8.4.1 CHINA
- 8.4.1.1 Rising demand for nuclear energy to drive growth
- 8.4.2 INDIA
- 8.4.2.1 Consistently increasing manufacturing output to drive growth
- 8.4.3 JAPAN
- 8.4.3.1 Ultra-high-purity water requirements in semiconductor manufacturing to drive market
- 8.4.4 SOUTH KOREA
- 8.4.4.1 Increase in domestic wastewater and industrial wastewater to drive growth
- 8.4.5 THAILAND
- 8.4.5.1 Industrial process-water purification and boiler-water treatment to drive the market
- 8.4.6 INDONESIA
- 8.4.6.1 Large infrastructure budget to drive growth
- 8.4.7 TAIWAN
- 8.4.7.1 Growth of semiconductors industry to drive growth
- 8.4.8 REST OF ASIA PACIFIC
- 8.4.1 CHINA
- 8.5 MIDDLE EAST & AFRICA
- 8.5.1 GCC
- 8.5.1.1 Saudi Arabia
- 8.5.1.1.1 Increasing energy consumption to drive growth
- 8.5.1.2 UAE
- 8.5.1.2.1 Increasing desalination of seawater to drive growth
- 8.5.1.3 Rest of GCC
- 8.5.1.1 Saudi Arabia
- 8.5.2 TURKIYE
- 8.5.2.1 Growing electricity demand to drive growth
- 8.5.3 SOUTH AFRICA
- 8.5.3.1 Abundant natural resources, R&D capabilities, and established manufacturing base to drive growth
- 8.5.4 REST OF MIDDLE EAST & AFRICA
- 8.5.1 GCC
- 8.6 SOUTH AMERICA
- 8.6.1 BRAZIL
- 8.6.1.1 Sugar-ethanol purification and resource recovery to drive growth
- 8.6.2 ARGENTINA
- 8.6.2.1 Sustainable economic development to drive market
- 8.6.3 REST OF SOUTH AMERICA
- 8.6.1 BRAZIL
9 COMPETITIVE LANDSCAPE
- 9.1 INTRODUCTION
- 9.2 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2023-2026
- 9.3 REVENUE ANALYSIS, 2023-2025
- 9.4 MARKET SHARE ANALYSIS, 2025
- 9.4.1 DUPONT
- 9.4.2 LANXESS
- 9.4.3 ECOLAB
- 9.4.4 MITSUBISHI CHEMICAL GROUP CORPORATION
- 9.4.5 SAMYANG CORPORATION
- 9.5 COMPANY VALUATION AND FINANCIAL METRICS
- 9.6 BRAND/PRODUCT COMPARISON
- 9.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 9.7.1 STARS
- 9.7.2 EMERGING LEADERS
- 9.7.3 PERVASIVE PLAYERS
- 9.7.4 PARTICIPANTS
- 9.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 9.7.5.1 Company footprint
- 9.7.5.2 Region footprint
- 9.7.5.3 Type footprint
- 9.7.5.4 Application footprint
- 9.7.5.5 End-use industry footprint
- 9.8 COMPANY EVALUATION MATRIX: START-UPS/SMES, 2025
- 9.8.1 PROGRESSIVE COMPANIES
- 9.8.2 RESPONSIVE COMPANIES
- 9.8.3 DYNAMIC COMPANIES
- 9.8.4 STARTING BLOCKS
- 9.8.5 COMPETITIVE BENCHMARKING: START-UPS/SMES, 2025
- 9.8.5.1 List of start-ups/SMEs
- 9.8.5.2 Competitive benchmarking of start-ups/SMEs
- 9.9 COMPETITIVE SCENARIO
- 9.9.1 PRODUCT LAUNCHES
- 9.9.2 DEALS
- 9.9.3 EXPANSIONS
10 COMPANY PROFILES
- 10.1 KEY PLAYERS
- 10.1.1 DUPONT
- 10.1.1.1 Business overview
- 10.1.1.2 Products offered
- 10.1.1.3 Recent developments
- 10.1.1.3.1 Product launches
- 10.1.1.4 MnM view
- 10.1.1.4.1 Right to win
- 10.1.1.4.2 Strategic choices
- 10.1.1.4.3 Weaknesses and competitive threats
- 10.1.2 LANXESS
- 10.1.2.1 Business overview
- 10.1.2.2 Products offered
- 10.1.2.3 Recent developments
- 10.1.2.3.1 Product launches
- 10.1.2.3.2 Expansions
- 10.1.2.4 MnM view
- 10.1.2.4.1 Right to win
- 10.1.2.4.2 Strategic choices
- 10.1.2.4.3 Weaknesses and competitive threats
- 10.1.3 ECOLAB (PUROLITE)
- 10.1.3.1 Business overview
- 10.1.3.2 Products offered
- 10.1.3.3 Recent developments
- 10.1.3.3.1 Product launches
- 10.1.3.3.2 Deals
- 10.1.3.3.3 Expansions
- 10.1.3.4 MnM view
- 10.1.3.4.1 Right to win
- 10.1.3.4.2 Strategic choices
- 10.1.3.4.3 Weaknesses and competitive threats
- 10.1.4 MITSUBISHI CHEMICAL GROUP CORPORATION
- 10.1.4.1 Business overview
- 10.1.4.2 Products offered
- 10.1.4.3 Recent developments
- 10.1.4.3.1 Expansions
- 10.1.4.4 MnM view
- 10.1.4.4.1 Right to win
- 10.1.4.4.2 Strategic choices
- 10.1.4.4.3 Weaknesses and competitive threats
- 10.1.5 SAMYANG CORPORATION
- 10.1.5.1 Business overview
- 10.1.5.2 Products offered
- 10.1.5.3 MnM view
- 10.1.5.3.1 Right to win
- 10.1.5.3.2 Strategic choices
- 10.1.5.3.3 Weaknesses and competitive threats
- 10.1.6 ION EXCHANGE INDIA (IEI)
- 10.1.6.1 Business overview
- 10.1.6.2 Products offered
- 10.1.6.3 MnM view
- 10.1.6.3.1 Right to win
- 10.1.6.3.2 Strategic choices
- 10.1.6.3.3 Weaknesses and competitive threats
- 10.1.7 JACOBI RESINS
- 10.1.7.1 Business overview
- 10.1.7.2 Products offered
- 10.1.7.3 MnM view
- 10.1.8 THERMAX LIMITED
- 10.1.8.1 Business overview
- 10.1.8.2 Products offered
- 10.1.8.3 Recent developments
- 10.1.8.3.1 Deals
- 10.1.8.3.2 Expansions
- 10.1.8.4 MnM view
- 10.1.9 OVIVO
- 10.1.9.1 Business overview
- 10.1.9.2 Products offered
- 10.1.9.3 MnM view
- 10.1.10 SUNRESIN NEW MATERIALS CO., LTD.
- 10.1.10.1 Business overview
- 10.1.10.2 Products offered
- 10.1.10.3 MnM view
- 10.1.1 DUPONT
- 10.2 OTHER PLAYERS
- 10.2.1 RESINTECH, INC.
- 10.2.2 EVOQUA WATER TECHNOLOGIES LLC
- 10.2.3 ALDEX CHEMICAL COMPANY, LTD.
- 10.2.4 GFS CHEMICALS, INC.
- 10.2.5 SUQING GROUP
- 10.2.6 APPLEXION
- 10.2.7 ANHUI SANXING RESIN TECHNOLOGY CO., LTD.
- 10.2.8 RESINDION S.R.L.
- 10.2.9 KOVALUS SEPARATION SOLUTIONS
- 10.2.10 ACURO ORGANICS LIMITED
- 10.2.11 WESTERN CARBON & CHEMICALS
- 10.2.12 DOSHION POLYSCIENCE PVT. LTD.
- 10.2.13 AQUAFILSEP
- 10.2.14 GRAVER TECHNOLOGIES
- 10.2.15 HYDROFLUX
11 RESEARCH METHODOLOGY
- 11.1 RESEARCH DATA
- 11.1.1 SECONDARY DATA
- 11.1.1.1 Key secondary sources
- 11.1.1.2 Key data from secondary sources
- 11.1.2 PRIMARY DATA
- 11.1.2.1 Key data from primary sources
- 11.1.2.2 Key industry insights
- 11.1.2.3 Breakdown of interviews with experts
- 11.1.1 SECONDARY DATA
- 11.2 MARKET SIZE ESTIMATION
- 11.2.1 BOTTOM-UP APPROACH
- 11.2.2 TOP-DOWN APPROACH
- 11.3 DATA TRIANGULATION
- 11.4 FACTOR ANALYSIS
- 11.5 GROWTH FORECAST
- 11.5.1 SUPPLY SIDE
- 11.5.2 DEMAND SIDE
- 11.6 RESEARCH ASSUMPTIONS
- 11.7 RESEARCH LIMITATIONS
- 11.8 RISK ASSESSMENT
12 APPENDIX
- 12.1 DISCUSSION GUIDE
- 12.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 12.3 CUSTOMIZATION OPTIONS
- 12.4 RELATED REPORTS
- 12.5 AUTHOR DETAILS


