

|
시장보고서
상품코드
2158073
레이저 가공 시장 예측(-2033년) : 레이저 유형, 구성, 용도, 최종사용자, 지역별Laser Processing Market by Laser Type (Solid Lasers, Gas Lasers, Liquid Lasers), Configuration (Fixed Beam, Moving Beam, Hybrid Beam), Application (Cutting, Welding, Drilling), End User, and Region - Global Forecast to 2033 |
||||||

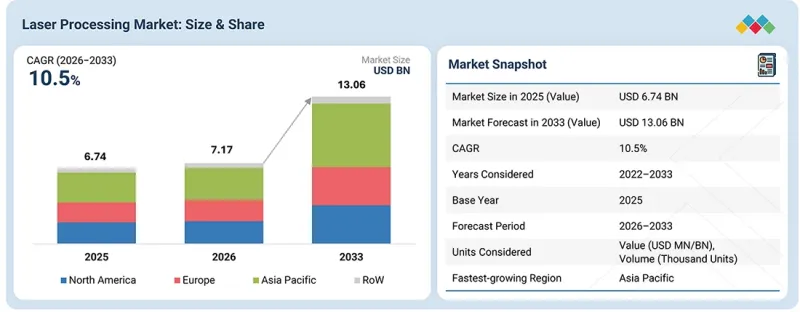
레이저 가공 시장은 2026년 71억 7,000만 달러에서 2033년에는 130억 6,000만 달러에 달할 것으로 예측되며, 2026-2033년 연평균 성장률(CAGR) 10.5%를 기록할 전망입니다.
이 시장은 고정밀 제조에 대한 수요 증가, 자동화 및 로봇 기술 도입 확대, 그리고 마이크로전자·반도체, 자동차, 의료·생명과학, 항공우주, 건축·건설 및 기타 최종 용도 산업에서의 레이저 가공 공정 활용 확대에 힘입어 예측 기간 중 강력한 성장을 이룰 것으로 전망됩니다. 각 기업은 생산 효율 향상, 가공 정밀도 향상, 재료 낭비 감소, 그리고 복잡한 제조 요구 사항에 대응하기 위해 레이저 가공 시스템에 대한 투자를 점점 더 늘리고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2033년 |
| 기준 연도 | 2025 |
| 예측 기간 | 2026-2033년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 레이저 유형, 구성, 용도, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양(APAC), 기타 지역(RoW) |
또한 고출력 고체 레이저, 가변 빔 및 하이브리드 빔 구성, 그리고 첨단 가공 기술의 채택이 확대됨에 따라 각 제조사는 유연하고 고성능인 레이저 솔루션을 활용하여 생산 공정의 현대화를 추진하고 있습니다. 자동화, 공정 효율, 제품 품질 및 첨단 제조 역량에 대한 관심이 높아지고 있는 점도 세계 시장의 장기적인 성장을 더욱 지원하고 있습니다.
"2026-2033년에 레이저 가공 시장에서 이동 빔 부문이 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다."
구성별로는 복잡한 제조 용도에서 유연하고 정밀한 레이저 가공에 대한 수요가 증가함에 따라 이동 빔 부문이 예측 기간 중 가장 높은 성장률을 기록할 것으로 전망됩니다. 기업은 다양한 재료, 형상, 부품 크기를 효율적으로 가공하기 위해 가동 빔 구성의 도입을 점점 더 확대하고 있습니다. 자동화된 레이저 시스템 및 로봇의 도입 확대는 유연한 빔 이동과 정밀한 가공 제어에 대한 수요를 더욱 가속화하고 있습니다. 또한 절단, 용접, 천공, 마킹 및 조각, 그리고 첨단 가공 분야의 응용 분야가 증가함에 따라 이동식 빔 솔루션에 대한 수요가 창출되고 있습니다. 이러한 기능들 덕분에 전 세계에서 이동식 빔 부문의 급속한 성장이 지원되고 있습니다.
"2033년에는 레이저 가공 시장에서 절단 부문이 가장 큰 점유율을 차지할 것으로 전망됩니다."
용도별로는 제조 업계 전반에서 고정밀·고효율의 자동화된 소재 가공 솔루션에 대한 수요가 높아지고 있으며, 2033년에는 절단 부문이 가장 큰 시장 점유율을 차지할 것으로 예상됩니다. 기업은 자동차, 항공우주, 마이크로전자·반도체, 건축·건설 및 기타 최종 용도 산업에 걸친 분야에서 금속 및 기타 재료를 가공하기 위해 레이저 절단 시스템 도입을 점점 더 확대하고 있습니다. 자동화 제조, 로봇 공학 및 첨단 레이저 기술의 채택 확대에 따라 고성능 레이저 절단 시스템에 대한 수요는 더욱 증가하고 있습니다. 또한 레이저 절단 솔루션이 고정밀도, 고속 가공, 재료 손실 감소 및 일관된 제품 품질을 실현할 수 있는 능력을 갖추고 있다는 점이 전 세계에서 절단 부문의 지속적인 성장을 지원하고 있습니다.
"예측 기간 중 레이저 가공 시장에서 아시아태평양이 가장 높은 성장률을 보일 것으로 전망됩니다."
아시아태평양은 첨단 제조에 대한 투자 증가, 전자 및 반도체 생산의 급속한 확대, 그리고 산업용 자동화 도입 확대로 인해 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다. 기업은 정밀 제조, 소재 가공 및 자동화 생산을 지원하기 위해 레이저 가공 솔루션 도입을 점점 더 확대하고 있습니다. 또한 중국, 일본, 한국, 인도에서의 제조 거점 확대와 더불어 반도체 제조, 자동차 생산, 전자기기 제조에 대한 투자 증가가 맞물려 첨단 레이저 가공 솔루션에 대한 강력한 수요가 발생하고 있습니다. 첨단 제조를 지원하는 정부의 노력과 자동화 및 고정밀 생산 기술에 대한 투자 확대도 이 지역의 시장 성장에 더욱 기여하고 있습니다.
2차 조사를 통해 수집된 각종 부문 및 하위 부문 시장 규모를 파악하고 검증하기 위해, 레이저 가공 생태계의 주요 업계 전문가들을 대상으로 광범위한 1차 인터뷰가 실시되었습니다. 이 보고서의 1차 인터뷰 대상자 구성은 다음과 같습니다. :
본 조사에는 레이저 제조사, 레이저 가공 장비 공급업체, 시스템 통합사업자, 부품 공급업체, 판매 대리점, 기술 컨설턴트, 최종사용자 등 다양한 업계 전문가들의 인사이트가 포함되어 있습니다. 1차 조사 대상자의 내역은 다음과 같습니다. :
- 기업 유형별: Tier 1-25%, Tier 2-40%, Tier 3-35%
- 직책별: C레벨 임원-30%, 이사-32%, 기타-38%
- 지역별: 북미-20%, 유럽-40%, 아시아태평양-35%, 기타 지역-5%
조사 범위
본 조사 보고서에서는 레이저 가공 시장을 레이저 유형, 구성, 용도, 최종 용도 산업 및 지역별로 분류하고 있습니다. 이 보고서에서는 시장과 관련된 주요 시장 촉진요인, 억제요인, 과제 및 기회에 대해 설명하고, 2033년까지의 시장 전망을 제시하고 있습니다.
이 외에도 이 보고서에는 레이저 가공 시장의 생태계에 포함된 모든 기업에 대한 리더십 매핑 및 분석도 포함되어 있습니다.
이 보고서를 구매할 때의 주요 이점
이 보고서는 레이저 가공 시장의 시장 선도 기업 및 신규 진입 기업에게 레이저 가공 시장 전체와 그 하위 부문에 대한 가장 정확한 수치 추정치를 제공합니다. 이 보고서는 이해관계자가 경쟁 구도를 이해하고, 자사의 비즈니스를 더 유리한 위치에 놓으며, 적절한 시장 진입 전략을 수립하기 위한 추가적인 인사이트를 얻는 데 도움이 됩니다. 또한 이 보고서는 이해관계자가 시장 동향을 파악할 수 있도록 지원하며, 주요 시장 촉진요인, 억제요인, 과제 및 기회에 대한 정보를 제공합니다.
이 보고서는 다음 사항에 대한 인사이트를 제공합니다. :
- 시장 역학: 주요 촉진요인(정밀 의료 및 맞춤형 치료에 레이저 기술 통합이 진행되고 있음, 기존 재료 가공 방식에서 첨단 레이저 기반 솔루션으로의 급속한 전환) 및 제약 요인(막대한 연구개발 투자와 초기 도입 비용, 숙련된 레이저 기술자 부족), 기회(자동차 분야에서의 레이저 기술 활용 확대, 소비재의 디자인, 기능성 및 개인화 향상에 대한 강력한 집중), 그리고 과제(희토류 원소에 대한 의존으로 인한 환경 문제 및 고출력 레이저 통합 시의 기술적 제약)에 대한 분석
- 제품 개발/혁신: 시장의 향후 기술, 연구개발 활동 및 신제품·솔루션 출시에 대한 상세 인사이트
- 시장 개발: 수익성이 높은 시장에 대한 포괄적인 정보 - 이 보고서는 다양한 지역에 걸친 시장을 분석하고 있습니다
- 시장 다각화: 신제품 및 솔루션, 미개발 지역, 최근 동향, 그리고 시장 투자에 관한 포괄적인 정보
- 경쟁 분석: 주요 기업의 시장 점유율, 성장 전략, 제품 라인업에 대한 상세한 평가
자주 묻는 질문
목차
제1장 서론
제2장 요약
제3장 주요 인사이트
- 레이저 가공 시장에서 사업자에게 매력적인 기회
- 레이저 가공 시장: 레이저 유형별
- 레이저 가공 시장: 구성별
- 레이저 가공 시장: 용도별
- 레이저 가공 시장: 최종 용도 산업별
- 레이저 가공 시장: 지역별
제4장 시장 개요
- 시장 역학
- 촉진요인
- 억제요인
- 기회
- 과제
- 미충족 수요와 미개발 분야
- 상호 연관된 시장 및 부문 간 기회
- Tier 1/2/3 주요 기업의 전략적 움직임
제5장 업계 동향
- Porter's Five Forces 분석
- 신규 진입자의 위협
- 대체품의 위협
- 공급업체의 협상력
- 구매자의 협상력
- 경쟁 기업간 경쟁 관계의 격렬함
- 거시경제 전망
- GDP 동향 및 전망
- 세계 제조업 동향
- 세계 자동차 및 전기자동차 산업의 동향
- 공급망 분석
- 생태계 분석
- 가격 분석
- 레이저 유형별 평균 판매 가격 동향(2022-2025년)
- 지역별 레이저 가공 솔루션의 평균 판매 가격 동향(2022-2025년)
- 무역 분석
- 수입 시나리오(HS 코드 901320)
- 수출 시나리오(HS 코드 901320)
- 주요 회의 및 행사(2026-2027년)
- 고객의 사업에 영향을 미치는 동향/파괴적 변화
- 투자 및 자금 조달 시나리오
- 사례 연구 분석
- 미국 관세의 영향 - 레이저 가공 시장
- 주요 관세율
- 가격에 미치는 영향 분석
- 국가 및 지역에 미치는 영향
- 최종 용도 산업에 미치는 영향
제6장 기술 발전, AI의 영향, 특허 및 혁신
- 주요 기술
- 기계학습과 인공지능
- 적층 제조
- 보완 기술
- LiDAR
- 관련 기술
- 광섬유
- 특허 분석
- AI가 레이저 가공 시장에 미치는 영향
- 주요 활용 사례 및 시장 잠재력
- 레이저 가공 시장에서 제조사/OEM이 실천하고 있는 베스트 프랙티스
- 레이저 가공 시장에서의 AI 도입에 관한 사례 연구
- 상호 연관된/인접한 생태계 및 시장 참여자에 미치는 영향
- 레이저 가공 시장에서 고객의 AI 도입 준비 현황
- 규제 현황
- 규제기관, 정부 기관 및 기타 조직
- 표준
제7장 고객 현황 및 구매 행동
- 의사결정 과정
- 구매 과정에 관여하는 주요 이해관계자와 그 구매 기준
- 구매 과정에 관여하는 주요 이해관계자
- 구매 기준
- 도입 장벽 및 사내 과제
- 각종 최종사용자 산업 분야의 미충족 수요
제8장 레이저 가공 장치의 구성 요소
- 레이저
- 레이저 시스템
제9장 레이저 가공 시장: 레이저 유형별
- 고체 레이저
- 가스 레이저
- 액체 레이저
- 기타 레이저 유형별
제10장 레이저 가공 시장: 구성별
- 고정 빔
- 이동 빔
- 하이브리드 빔
제11장 레이저 가공 시장: 용도별
- 절단
- 용접
- 천공
- 마킹 및 조각
- 첨단 가공
- 기타 용도
제12장 레이저 가공 시장: 최종 용도 산업별
- 마이크로전자 및 반도체
- 자동차
- 의료·생명과학
- 항공우주
- 건축·건설
- 기타 최종 용도 산업
제13장 레이저 가공 시장: 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 영국
- 독일
- 프랑스
- 이탈리아
- 스페인
- 네덜란드
- 스위스
- 폴란드
- 북유럽 국가들
- 기타 유럽
- 아시아태평양
- 중국
- 일본
- 한국
- 인도
- 호주
- 인도네시아
- 말레이시아
- 태국
- 베트남
- 기타 아시아태평양
- 기타 지역
- 중동
- 남미
- 아프리카
- 남아프리카
- 기타 아프리카 국가들
제14장 경쟁 현황
- 개요
- 주요 진입 기업의 전략/강점, 성공 요인, 2024-2026년
- 시장 점유율 분석, 2025년
- 수익 분석
- 기업 가치 평가 및 재무 지표
- 브랜드/제품 비교
- 기업 평가 매트릭스(주요 기업), 2025년
- 스타 기업
- 신흥 리더
- 광범위한 참여 기업
- 진입 기업
- 기업의 사업 전개: 주요 기업, 2025년
- 기업 평가 매트릭스: 스타트업/중소기업, 2025년
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 경쟁사 벤치마킹: 스타트업/중소기업, 2025년
- 경쟁 시나리오
- 제품 출시
- 거래
- 사업 확장
제15장 기업 개요
- 주요 기업
- COHERENT CORP.
- TRUMPF
- HAN'S LASER TECHNOLOGY INDUSTRY GROUP CO., LTD.
- IPG PHOTONICS CORPORATION
- JENOPTIK AG
- FIVES
- AXBIS
- LUMENTUM OPERATIONS LLC
- GRAVOTECH, INC.
- LASER STAR TECHNOLOGIES
- LUMIBIRD
- EPILOG LASER
- MKS INSTRUMENTS
- NOVANTA INC.
- EUROLASER GMBH
- 기타 주요 기업
- 600 GROUP PLC
- BYSTRONIC GROUP
- ALPHALAS GMBH
- APPLIED LASER TECHNOLOGY, INC.
- ARIMA LASERS CORP.
- FOCUSLIGHT TECHNOLOGIES INC.
- INNO LASER TECHNOLOGY CO., LTD.
- NKT PHOTONICS A/S
- PHOTONICS INDUSTRIES INTERNATIONAL. INC.
- SFX
- TOPTICA PHOTONICS AG
- UNIVERSAL LASER SYSTEMS, INC.
제16장 조사 방법론
제17장 부록
KSA 26.11.03The laser processing market is projected to reach USD 13.06 billion by 2033 from USD 7.17 billion in 2026, exhibiting a CAGR of 10.5% from 2026 to 2033. The market is expected to witness strong growth during the forecast period, driven by increasing demand for high-precision manufacturing, rising adoption of automation and robotics, and growing use of laser-based processes across microelectronics & semiconductors, automotive, medical & life sciences, aerospace, architecture & construction, and other end-use industries. Organizations are increasingly investing in laser processing systems to improve production efficiency, enhance processing precision, reduce material waste, and support complex manufacturing requirements.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2033 |
| Base Year | 2025 |
| Forecast Period | 2026-2033 |
| Units Considered | Value (USD Billion) |
| Segments | By Laser Type, Configuration, Application and Region |
| Regions covered | North America, Europe, APAC, RoW |
In addition, the growing adoption of high-power solid lasers, moving and hybrid beam configurations, and advanced processing technologies is encouraging manufacturers to modernize their production processes with flexible and high-performance laser solutions. The increasing focus on automation, process efficiency, product quality, and advanced manufacturing capabilities is further supporting long-term global market expansion.
"Moving beams segment to register the highest CAGR in the laser processing market from 2026 to 2033"
By configuration, the moving beams segment is expected to record the highest growth rate during the forecast period, driven by the increasing demand for flexible and precise laser processing across complex manufacturing applications. Organizations are increasingly adopting moving beam configurations to support efficient processing of different materials, geometries, and component sizes. The growing adoption of automated laser systems and robotics is further accelerating the demand for flexible beam movement and precise processing control. In addition, increasing applications in cutting, welding, drilling, marking and engraving, and advanced processing are creating demand for moving beam solutions. These capabilities are supporting the rapid growth of the moving beams segment globally.
"Cutting segment to account for the largest share of the laser processing market in 2033"
By application, the cutting segment is anticipated to capture the largest market share in 2033 due to the increasing demand for high-precision, efficient, and automated material processing solutions across manufacturing industries. Organizations are increasingly deploying laser cutting systems for processing metals and other materials in applications across automotive, aerospace, microelectronics & semiconductors, architecture & construction, and other end-use industries. The growing adoption of automated manufacturing, robotics, and advanced laser technologies is further increasing demand for high-performance laser cutting systems. In addition, the ability of laser cutting solutions to deliver high precision, faster processing, reduced material waste, and consistent product quality is supporting the continued growth of the Cutting segment globally.
"Asia Pacific to be the fastest-growing in the laser processing market during the forecast period"
Asia Pacific is expected to register the highest CAGR during the forecast period due to increasing investments in advanced manufacturing, rapid expansion of electronics and semiconductor production, and growing adoption of industrial automation. Organizations are increasingly deploying laser processing solutions to support precision manufacturing, material processing, and automated production. In addition, the growing manufacturing base across China, Japan, South Korea, and India, coupled with increasing investments in semiconductor fabrication, automotive production, and electronics manufacturing, is creating strong demand for advanced laser processing solutions. Government initiatives supporting advanced manufacturing and increasing investments in automation and high-precision production technologies are further contributing to the regional market growth.
Extensive primary interviews were conducted with key industry experts in the laser processing ecosystem to determine and verify the market size for various segments and subsegments gathered through secondary research. The breakdown of primary participants for the report is provided below:
The study contains insights from various industry experts, including laser manufacturers, laser processing equipment providers, system integrators, component suppliers, distributors, technology consultants, and end users. The breakdown of the primaries is as follows:
- By Company Type: Tier 1-25%, Tier 2-40%, and Tier 3-35%
- By Designation: C-level Executives-30%, Directors-32%, and Others-38%
- By Region: North America-20%, Europe-40%, Asia Pacific-35%, and RoW-5%
The report profiles key players in the laser processing market with their market ranking analysis. Prominent players profiled in this report are Coherent Corp. (US), TRUMPF (Germany), Han's Laser Technology Industry Group Co., Ltd. (China), IPG Photonics Corporation (US), and JENOPTIK AG (Germany). Apart from these, Fives (France), Lumentum Operations LLC (US), Gravotech, Inc. (France), Laser Star Technologies (US), and LUMIBIRD (France), among others, are among the other companies profiled in the market.
Research Coverage
This research report categorizes the laser processing market based on laser type, configuration, application, end-use industry, and region. The report describes the major drivers, restraints, challenges, and opportunities pertaining to the market and forecasts the market through 2033.
Apart from this, the report also consists of leadership mapping and analysis of all the companies included in the laser processing market ecosystem.
Key Benefits of Buying the Report
The report will help the market leaders/new entrants in the laser processing market with information on the closest approximations of the numbers for the overall laser processing market and its subsegments. This report will help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies. The report also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Market Dynamics: Analysis of key drivers (Rising integration of laser technologies into precision healthcare and tailored treatments, Rapid transition from traditional material processing methods to advanced laser-based solutions), restraints (Significant R&D investment and initial deployment costs, Limited availability of skilled laser technicians), opportunities (Expanding use of laser technologies in automotive sector, Strong focus on enhancing design, functionality, and personalization of consumer goods), and challenges (environmental concerns due to reliance on rare-earth elements and technical limitations in high-power laser integration) in the laser processing market
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and new product and solution launches in the market
- Market Development: Comprehensive information about lucrative markets-the report analyzes the market across varied regions
- Market Diversification: Exhaustive information about new products & solutions, untapped geographies, recent developments, and investments in the market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and product offerings of leading players, including Coherent Corp., TRUMPF, Han's Laser Technology Industry Group Co., Ltd., IPG Photonics Corporation, and JENOPTIK AG in the market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 UNIT CONSIDERED
- 1.6 LIMITATIONS
- 1.7 STAKEHOLDERS
- 1.8 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN LASER PROCESSING MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN LASER PROCESSING MARKET
- 3.2 LASER PROCESSING MARKET, BY LASER TYPE
- 3.3 LASER PROCESSING MARKET, BY CONFIGURATION
- 3.4 LASER PROCESSING MARKET, BY APPLICATION
- 3.5 LASER PROCESSING MARKET, BY END-USE INDUSTRY
- 3.6 LASER PROCESSING MARKET, BY GEOGRAPHY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing integration of laser technologies in precision healthcare and tailored treatments
- 4.2.1.2 Transition from traditional material processing methods to advanced laser-based solutions
- 4.2.1.3 Increasing dependence on laser technologies for nano- and micro-scale manufacturing
- 4.2.1.4 Expanding laser applications in marking and coding operations
- 4.2.2 RESTRAINTS
- 4.2.2.1 Significant R&D investment and initial deployment costs
- 4.2.2.2 Limited availability of skilled laser technicians
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expanding use of laser technologies in automotive sector
- 4.2.3.2 Growing adoption to enhance design, functionality, and personalization of consumer goods
- 4.2.3.3 Expanding role in scientific research and innovation
- 4.2.4 CHALLENGES
- 4.2.4.1 Environmental concerns due to use of rare-earth elements
- 4.2.4.2 Technical limitations in high-power laser integration
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 INTRODUCTION
- 5.2 PORTER'S FIVE FORCES ANALYSIS
- 5.2.1 THREAT OF NEW ENTRANTS
- 5.2.2 THREAT OF SUBSTITUTES
- 5.2.3 BARGAINING POWER OF SUPPLIERS
- 5.2.4 BARGAINING POWER OF BUYERS
- 5.2.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.3 MACROECONOMIC OUTLOOK
- 5.3.1 INTRODUCTION
- 5.3.2 GDP TRENDS AND FORECAST
- 5.3.3 TRENDS IN GLOBAL MANUFACTURING INDUSTRY
- 5.3.4 TRENDS IN GLOBAL AUTOMOTIVE AND ELECTRIC VEHICLE INDUSTRY
- 5.4 SUPPLY CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE TREND OF LASER TYPE, 2022-2025
- 5.6.2 AVERAGE SELLING PRICE TREND OF LASER PROCESSING SOLUTIONS, BY REGION, 2022-2025
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT SCENARIO (HS CODE 901320)
- 5.7.2 EXPORT SCENARIO (HS CODE 901320)
- 5.8 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.9 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.10 INVESTMENT AND FUNDING SCENARIO
- 5.11 CASE STUDY ANALYSIS
- 5.12 IMPACT OF US TARIFFS - LASER PROCESSING MARKET
- 5.12.1 INTRODUCTION
- 5.12.2 KEY TARIFF RATES
- 5.12.3 PRICE IMPACT ANALYSIS
- 5.12.4 IMPACT ON COUNTRIES/REGIONS
- 5.12.4.1 US
- 5.12.4.2 Europe
- 5.12.4.3 Asia Pacific
- 5.12.5 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, AND INNOVATIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 MACHINE LEARNING & ARTIFICIAL INTELLIGENCE
- 6.1.2 ADDITIVE MANUFACTURING
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 LIDAR
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 FIBER OPTICS
- 6.4 PATENT ANALYSIS
- 6.5 IMPACT OF AI ON LASER PROCESSING MARKET
- 6.5.1 TOP USE CASES AND MARKET POTENTIAL
- 6.5.2 BEST PRACTICES FOLLOWED BY MANUFACTURERS/OEMS IN LASER PROCESSING MARKET
- 6.5.3 CASE STUDIES RELATED TO AI IMPLEMENTATION IN LASER PROCESSING MARKET
- 6.5.4 INTERCONNECTED/ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.5 CLIENTS' READINESS TO ADOPT AI IN LASER PROCESSING MARKET
- 6.6 REGULATORY LANDSCAPE
- 6.6.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 6.6.2 STANDARDS
- 6.6.2.1 IEC 60825-1:2014
- 6.6.2.2 ANSI Z136.1
- 6.6.2.3 Federal Laser Product Performance Standard (FLPPS)
- 6.6.2.4 International Commission on Non-ionizing Radiation Protection (ICNIRP) (2013)
- 6.6.2.5 EN 60825 - Safety of Laser Products
7 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 7.1 DECISION-MAKING PROCESS
- 7.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR BUYING CRITERIA
- 7.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 7.2.2 BUYING CRITERIA
- 7.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 7.4 UNMET NEEDS OF VARIOUS END-USE INDUSTRIES
8 COMPONENTS OF LASER PROCESSING DEVICES
- 8.1 INTRODUCTION
- 8.2 LASERS
- 8.3 LASER SYSTEMS
9 LASER PROCESSING MARKET, BY LASER TYPE
- 9.1 INTRODUCTION
- 9.2 SOLID LASERS
- 9.2.1 FIBER LASERS
- 9.2.1.1 Rising adoption in cutting, welding, and marking applications to drive segmental growth
- 9.2.2 RUBY LASERS
- 9.2.2.1 Sustained demand in dermatology and scientific research to support segmental growth
- 9.2.3 YAG LASERS
- 9.2.3.1 Growing use in high-precision welding and cutting to propel segmental growth
- 9.2.4 SEMICONDUCTOR LASERS
- 9.2.4.1 Increasing deployment in additive manufacturing and compact laser systems to boost segmental growth
- 9.2.5 THIN-DISK LASERS
- 9.2.5.1 Rising need for high-power, high-beam quality processing to accelerate segmental growth
- 9.2.1 FIBER LASERS
- 9.3 GAS LASERS
- 9.3.1 CO2 LASERS
- 9.3.1.1 Rising demand for contactless processing of non-metallic materials to drive segmental growth
- 9.3.2 EXCIMER LASERS
- 9.3.2.1 Expanding use in semiconductor photolithography and vision correction to propel segmental growth
- 9.3.3 HELIUM-NEON LASERS
- 9.3.3.1 Sustained need for precision alignment and measurement tools to support segmental growth
- 9.3.4 ARGON LASERS
- 9.3.4.1 Continued adoption in ophthalmic procedures and scientific research to boost segmental growth
- 9.3.5 CHEMICAL LASERS
- 9.3.5.1 Growing investments in defense and high-energy research to sustain segmental growth
- 9.3.1 CO2 LASERS
- 9.4 LIQUID LASERS
- 9.4.1 ELEVATING DEPLOYMENT IN VEGETATION AND LAND COVER STUDIES TO DRIVE MARKET
- 9.5 OTHER LASER TYPES
10 LASER PROCESSING MARKET, BY CONFIGURATION
- 10.1 INTRODUCTION
- 10.2 FIXED BEAMS
- 10.2.1 EVOLUTION OF MOTION CONTROL AND CNC SYSTEMS TO SUPPORT MARKET EXPANSION
- 10.3 MOVING BEAMS
- 10.3.1 GOVERNMENT INVESTMENTS SUPPORTING SMART MANUFACTURING INITIATIVES TO FUEL MARKET GROWTH
- 10.4 HYBRID BEAMS
- 10.4.1 RISING FOCUS ON REDUCING PRODUCTION CYCLE TIMES AND IMPROVING PRODUCT QUALITY TO ACCELERATE DEMAND
11 LASER PROCESSING MARKET, BY APPLICATION
- 11.1 INTRODUCTION
- 11.2 CUTTING
- 11.2.1 ADVANCEMENTS IN MANUFACTURING SECTOR TO DRIVE SEGMENTAL GROWTH
- 11.3 WELDING
- 11.3.1 GROWTH IN ELECTRIC VEHICLE AND BATTERY PRODUCTION TO SUPPORT MARKET GROWTH
- 11.4 DRILLING
- 11.4.1 GROWING DEMAND FOR HIGH-PRECISION MICROFABRICATION TO FUEL MARKET GROWTH
- 11.5 MARKING & ENGRAVING
- 11.5.1 RISING USE OF LASER ENGRAVING IN MEDICAL DEVICE PRODUCTION FOR PRECISION AND STERILITY TO PROPEL MARKET
- 11.6 ADVANCED PROCESSING
- 11.6.1 ADVANCEMENTS IN ADDITIVE MANUFACTURING IN INDUSTRIAL AND HEALTHCARE SECTORS TO FOSTER MARKET GROWTH
- 11.7 OTHER APPLICATIONS
12 LASER PROCESSING MARKET, BY END-USE INDUSTRY
- 12.1 INTRODUCTION
- 12.1.1 KEY COMPETITORS
- 12.2 MICROELECTRONICS & SEMICONDUCTORS
- 12.2.1 MINIATURIZATION AND RISING CIRCUIT COMPLEXITY TO ACCELERATE DEMAND FOR ADVANCED LASER PROCESSING
- 12.2.2 CASE STUDY ANALYSIS
- 12.2.3 PCB DRILLING & CUTTING
- 12.2.4 WAFER DICING
- 12.2.5 OLED DISPLAY PATTERNING
- 12.2.5.1 List of clients in microelectronics & semiconductors industry
- 12.3 AUTOMOTIVE
- 12.3.1 SHIFT TOWARD LIGHTWEIGHT MATERIALS, ELECTRIC VEHICLES, AND AUTOMATED MANUFACTURING TO DRIVE MARKET
- 12.3.2 CASE STUDY ANALYSIS
- 12.3.3 BODY PANEL WELDING
- 12.3.4 BATTERY WELDING
- 12.3.5 PLASTIC COMPONENT MARKING
- 12.3.5.1 List of clients in automotive industry
- 12.4 MEDICAL & LIFE SCIENCES
- 12.4.1 ACCELERATED DEMAND FOR PRECISION AND MINIATURIZATION IN MEDICAL DEVICES TO FUEL MARKET GROWTH
- 12.4.2 CASE STUDY ANALYSIS
- 12.4.3 MEDICAL DEVICE MANUFACTURING
- 12.4.4 LASER MICROMACHINING FOR STENTS
- 12.4.5 DNA AND CELL MANIPULATION
- 12.4.5.1 List of clients in medical & life sciences industry
- 12.5 AEROSPACE
- 12.5.1 RISING FOCUS ON REDUCING MATERIAL WASTE AND EXPEDITING PRODUCTION TO STIMULATE DEMAND
- 12.5.2 CASE STUDY ANALYSIS
- 12.5.3 AIRCRAFT COMPONENT WELDING
- 12.5.4 COMPOSITE MATERIAL PROCESSING
- 12.5.5 LASER RANGE FINDERS & TARGETING SYSTEMS
- 12.5.5.1 List of clients in aerospace industry
- 12.6 ARCHITECTURE & CONSTRUCTION
- 12.6.1 HEIGHTENED USE OF AUTOMATED AND DIGITALLY CONTROLLED FABRICATION TO SUPPORT MARKET EXPANSION
- 12.6.2 CASE STUDY ANALYSIS
- 12.6.3 DECORATIVE LASER CUTTING
- 12.6.4 INTERIOR & FACADE ENGRAVING
- 12.6.4.1 List of clients in architecture & construction industry
- 12.7 OTHER END-USE INDUSTRIES
- 12.7.1 CASE STUDY ANALYSIS
- 12.7.1.1 List of clients in other end-use industries
- 12.7.1 CASE STUDY ANALYSIS
13 LASER PROCESSING MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 US
- 13.2.1.1 Growing need for micro-processing in electronics manufacturing to drive market growth
- 13.2.2 CANADA
- 13.2.2.1 Government-backed innovations in optics and photonics segment to support market growth
- 13.2.3 MEXICO
- 13.2.3.1 Development of smart manufacturing hubs to foster market expansion
- 13.2.1 US
- 13.3 EUROPE
- 13.3.1 UK
- 13.3.1.1 Increasing investments in photonics and laser research and development to propel market growth
- 13.3.2 GERMANY
- 13.3.2.1 Strong industrial foundation and investments in advanced manufacturing technologies to facilitate demand
- 13.3.3 FRANCE
- 13.3.3.1 Expanding medical, pharmaceuticals, and textiles sectors to create growth opportunities
- 13.3.4 ITALY
- 13.3.4.1 Expansion of local distribution network through international collaborations to support market growth
- 13.3.5 SPAIN
- 13.3.5.1 Investments in automation and smart manufacturing to contribute to market growth
- 13.3.6 NETHERLANDS
- 13.3.6.1 Growth in high-tech and precision manufacturing industries to support market growth
- 13.3.7 SWITZERLAND
- 13.3.7.1 Strong foundation and innovation in precision engineering and photonics to contribute to market growth
- 13.3.8 POLAND
- 13.3.8.1 Growing demand for precision manufacturing in electronics and semiconductors to drive market
- 13.3.9 NORDICS
- 13.3.9.1 Emphasis on advanced manufacturing, healthcare innovation, and sustainability to fuel demand
- 13.3.10 REST OF EUROPE
- 13.3.1 UK
- 13.4 ASIA PACIFIC
- 13.4.1 CHINA
- 13.4.1.1 Expansion of wafer fabrication, advanced packaging, and semiconductor equipment manufacturing to propel market
- 13.4.2 JAPAN
- 13.4.2.1 Presence of well-established manufacturing sector to offer lucrative growth opportunities
- 13.4.3 SOUTH KOREA
- 13.4.3.1 Advancement in additive manufacturing and 3D printing technologies to anticipate positive market growth
- 13.4.4 INDIA
- 13.4.4.1 Growing presence of international laser technology providers to contribute to market growth
- 13.4.5 AUSTRALIA
- 13.4.5.1 Strategic partnerships strengthening sovereign manufacturing capabilities to support market growth
- 13.4.6 INDONESIA
- 13.4.6.1 Government focus on semiconductor industry development to fuel market growth
- 13.4.7 MALAYSIA
- 13.4.7.1 Thriving semiconductor industry to create lucrative growth opportunities
- 13.4.8 THAILAND
- 13.4.8.1 Technology transfer from South Korean chipmaker to support market growth
- 13.4.9 VIETNAM
- 13.4.9.1 Increasing demand for laser processing solutions from battery manufacturers to fuel market growth
- 13.4.10 REST OF ASIA PACIFIC
- 13.4.1 CHINA
- 13.5 ROW
- 13.5.1 MIDDLE EAST
- 13.5.1.1 Bahrain
- 13.5.1.1.1 Strategic focus on industrial modernization to spur demand for laser processing
- 13.5.1.2 Kuwait
- 13.5.1.2.1 Policies under Kuwait Vision 2035 strategy to support market growth
- 13.5.1.3 Oman
- 13.5.1.3.1 Rising importance of laser-based solutions in commercial and industrial applications to support market growth
- 13.5.1.4 Qatar
- 13.5.1.4.1 Investment in advanced manufacturing and clean energy transition to contribute to market growth
- 13.5.1.5 Saudi Arabia
- 13.5.1.5.1 Expansion of domestic manufacturing capabilities using advanced technologies to fuel market growth
- 13.5.1.6 UAE
- 13.5.1.6.1 Investment in advanced battery manufacturing technologies to facilitate market growth
- 13.5.1.7 Rest of Middle East
- 13.5.1.1 Bahrain
- 13.5.2 SOUTH AMERICA
- 13.5.2.1 Major industrial trade fairs promoting technology awareness to strengthen market expansion
- 13.5.3 AFRICA
- 13.5.4 SOUTH AFRICA
- 13.5.4.1 Rising venture capital investment in ICT sector to boost adoption
- 13.5.5 OTHER AFRICAN COUNTRIES
- 13.5.1 MIDDLE EAST
14 COMPETITIVE LANDSCAPE
- 14.1 OVERVIEW
- 14.2 KEY PLAYER COMPETITIVE STRATEGIES, RIGHT TO WIN, 2024-2026
- 14.3 MARKET SHARE ANALYSIS, 2025
- 14.4 REVENUE ANALYSIS
- 14.5 COMPANY VALUATION AND FINANCIAL METRICS
- 14.6 BRAND/PRODUCT COMPARISON
- 14.7 COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- 14.7.1 STARS
- 14.7.2 EMERGING LEADERS
- 14.7.3 PERVASIVE PLAYERS
- 14.7.4 PARTICIPANTS
- 14.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 14.7.5.1 Company footprint
- 14.7.5.2 Region footprint
- 14.7.5.3 Laser type footprint
- 14.7.5.4 Application footprint
- 14.7.5.5 End-use industry footprint
- 14.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 14.8.1 PROGRESSIVE COMPANIES
- 14.8.2 RESPONSIVE COMPANIES
- 14.8.3 DYNAMIC COMPANIES
- 14.8.4 STARTING BLOCKS
- 14.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 14.8.5.1 Detailed list of additional start ups/SMES
- 14.8.5.2 Competitive benchmarking of key startups/SMEs
- 14.9 COMPETITIVE SCENARIO
- 14.9.1 PRODUCT LAUNCHES
- 14.9.2 DEALS
- 14.9.3 EXPANSIONS
15 COMPANY PROFILES
- 15.1 KEY PLAYERS
- 15.1.1 COHERENT CORP.
- 15.1.1.1 Business overview
- 15.1.1.2 Products/Solutions/Services offered
- 15.1.1.3 Recent developments
- 15.1.1.3.1 Product launches
- 15.1.1.4 MnM view
- 15.1.1.4.1 Key strengths/Right to win
- 15.1.1.4.2 Strategic choices
- 15.1.1.4.3 Weaknesses/Competitive threats
- 15.1.2 TRUMPF
- 15.1.2.1 Business overview
- 15.1.2.2 Products/Solutions/Services Offered
- 15.1.2.3 Recent developments
- 15.1.2.3.1 Product launches
- 15.1.2.3.2 Deals
- 15.1.2.4 MnM view
- 15.1.2.4.1 Key strengths/Right to win
- 15.1.2.4.2 Strategic choices
- 15.1.2.4.3 Weaknesses/Competitive threats
- 15.1.3 HAN'S LASER TECHNOLOGY INDUSTRY GROUP CO., LTD.
- 15.1.3.1 Business overview
- 15.1.3.2 Products/Solutions/Services offered
- 15.1.3.3 Recent developments
- 15.1.3.3.1 Product launches
- 15.1.3.4 MnM view
- 15.1.3.4.1 Key strengths/Right to win
- 15.1.3.4.2 Strategic choices
- 15.1.3.4.3 Weaknesses/Competitive threats
- 15.1.4 IPG PHOTONICS CORPORATION
- 15.1.4.1 Business overview
- 15.1.4.2 Products/Solutions/Services offered
- 15.1.4.3 Recent developments
- 15.1.4.3.1 Product launches
- 15.1.4.3.2 Deals
- 15.1.4.4 MnM view
- 15.1.4.4.1 Key strengths/Right to win
- 15.1.4.4.2 Strategic choices
- 15.1.4.4.3 Weaknesses/Competitive threats
- 15.1.5 JENOPTIK AG
- 15.1.5.1 Business overview
- 15.1.5.2 Products/Solutions/Services offered
- 15.1.5.3 Recent developments
- 15.1.5.3.1 Product launches
- 15.1.5.4 MnM view
- 15.1.5.4.1 Key strengths/Right to win
- 15.1.5.4.2 Strategic choices
- 15.1.5.4.3 Weaknesses/Competitive threats
- 15.1.6 FIVES
- 15.1.6.1 Business overview
- 15.1.6.2 Products/Solutions/Services offered
- 15.1.6.3 Recent developments
- 15.1.6.3.1 Expansions
- 15.1.7 AXBIS
- 15.1.7.1 Business overview
- 15.1.7.2 Products/Solutions/Services offered
- 15.1.8 LUMENTUM OPERATIONS LLC
- 15.1.8.1 Business overview
- 15.1.8.2 Products/Solutions/Services offered
- 15.1.8.3 Recent developments
- 15.1.8.3.1 Deals
- 15.1.8.3.2 Expansions
- 15.1.9 GRAVOTECH, INC.
- 15.1.9.1 Business overview
- 15.1.9.2 Products/Solutions/Services offered
- 15.1.9.3 Recent developments
- 15.1.9.3.1 Product launches
- 15.1.10 LASER STAR TECHNOLOGIES
- 15.1.10.1 Business overview
- 15.1.10.2 Products/Solutions/Services offered
- 15.1.11 LUMIBIRD
- 15.1.11.1 Business overview
- 15.1.11.2 Products/Solutions/Services offered
- 15.1.11.3 Recent developments
- 15.1.11.3.1 Deals
- 15.1.12 EPILOG LASER
- 15.1.12.1 Business overview
- 15.1.12.2 Products/Solutions/Services offered
- 15.1.12.3 Recent developments
- 15.1.12.3.1 Product launches
- 15.1.13 MKS INSTRUMENTS
- 15.1.13.1 Business overview
- 15.1.13.2 Products/Solutions/Services offered
- 15.1.13.3 Recent developments
- 15.1.13.3.1 Product launches
- 15.1.14 NOVANTA INC.
- 15.1.14.1 Business overview
- 15.1.14.2 Products/Solutions/Services offered
- 15.1.14.3 Recent developments
- 15.1.14.3.1 Product launches
- 15.1.15 EUROLASER GMBH
- 15.1.15.1 Business overview
- 15.1.15.2 Products/Solutions/Services offered
- 15.1.1 COHERENT CORP.
- 15.2 OTHER PLAYERS
- 15.2.1 600 GROUP PLC
- 15.2.2 BYSTRONIC GROUP
- 15.2.3 ALPHALAS GMBH
- 15.2.4 APPLIED LASER TECHNOLOGY, INC.
- 15.2.5 ARIMA LASERS CORP.
- 15.2.6 FOCUSLIGHT TECHNOLOGIES INC.
- 15.2.7 INNO LASER TECHNOLOGY CO., LTD.
- 15.2.8 NKT PHOTONICS A/S
- 15.2.9 PHOTONICS INDUSTRIES INTERNATIONAL. INC.
- 15.2.10 SFX
- 15.2.11 TOPTICA PHOTONICS AG
- 15.2.12 UNIVERSAL LASER SYSTEMS, INC.
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.1.1 Major secondary sources
- 16.1.1.2 Key data from secondary sources
- 16.1.2 PRIMARY DATA
- 16.1.2.1 Participants in primary interviews
- 16.1.2.2 Key data from primary sources
- 16.1.2.3 Key industry insights
- 16.1.2.4 Breakdown of primaries
- 16.1.3 SECONDARY AND PRIMARY RESEARCH
- 16.1.1 SECONDARY DATA
- 16.2 MARKET SIZE ESTIMATION
- 16.2.1 BOTTOM-UP APPROACH
- 16.2.1.1 Approach to estimate market size through bottom-up analysis (demand side)
- 16.2.2 TOP-DOWN APPROACH
- 16.2.2.1 Approach to estimate market size through top-down analysis (supply side)
- 16.2.2.2 Approach to estimate market size from supply side (approach 1)
- 16.2.2.3 Approach to estimate market size from supply side (approach 2)
- 16.2.1 BOTTOM-UP APPROACH
- 16.3 DATA TRIANGULATION
- 16.4 RESEARCH ASSUMPTIONS
- 16.5 PARAMETERS CONSIDERED TO ANALYZE RECESSION IMPACT ON LASER PROCESSING MARKET
- 16.6 RISK ASSESSMENT
- 16.7 RESEARCH LIMITATIONS
17 APPENDIX
- 17.1 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.2 CUSTOMIZATION OPTIONS
- 17.3 RELATED REPORTS
- 17.4 AUTHOR DETAILS


