

|
시장보고서
상품코드
2063414
반월판 수복 시스템 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Meniscus Repair Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
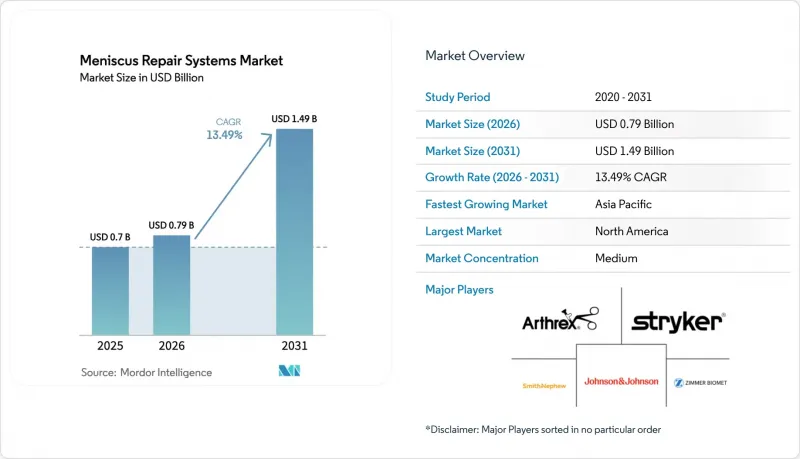
에 의하면, 반월판 수복 시스템 시장 규모는 2025년 7억 달러로 평가되었습니다. 2026년 7억 9,000만 달러에서 2031년까지 14억 9,000만 달러로 확대되고 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 13.49%를 나타낼 것으로 예측됩니다.
본 보고서는 수술 기법(올 인사이드, 인사이드 아웃, 아웃사이드-인, 반월상 연골 기저부 봉합, 하이브리드/증강 봉합), 최종 사용자(병원, 외래수술센터(ASC), 전문 정형외과 클리닉), 파열 유형(방사형, 수직 종단, 수평 파열 등), 지역(북미, 유럽 등)에 따라 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제공됩니다.
세계의 반월판 수복 시스템 시장 동향 및 인사이트
퇴행성 관절염의 진행을 억제하고 기능을 유지하기 위한 반월상 연골 절제술에서 복원술로의 전환
2024년 메타분석에 따르면, 반월상 연골 복원술은 부분 반월상 연골 절제술에 비해 X선 소견상 퇴행성 관절염의 10년 발병률을 51% 감소시키는 것으로 밝혀졌습니다. 이 데이터를 바탕으로 북미 및 유럽의 정형외과학회는 재건술을 권장하는 방향으로 지침을 개정했습니다. 보험사는 상환 제도 개편을 추진하고 있으며, 포괄 지급 모델에서는 보존적 치료를 선택한 의료기관에 인센티브가 제공되고 있습니다. 가치 기반 계약이 보급됨에 따라, 외과의사들은 과거에는 경미한 것으로 간주되던 파열도 복원하는 사례가 늘어나고 있으며, 이것이 반월판 수복 시스템 시장의 성장을 뒷받침하고 있습니다.
올 인사이드 및 매듭 없는 올 새튜어 시스템을 통해 적용 가능한 파단 범위가 확대됨
생체역학적 연구에 따르면, 매듭 없는 올 새처 복원법은 다양한 파열 유형에서 98.6%의 전개 성공률을 달성했으며, 실패율은 불과 6.35%에 그쳤습니다. Arthrex FiberTak(2025년 3월) 및 GMReis MENISCUS VERSAFLEX(2026년 2월)에 대한 FDA의 승인은 규제 당국의 신뢰를 확고히 하고 있습니다. 워크플로우의 간소화(포트 수 감소, 기구 제거에 따른 위험 없음, 수술 시간 단축)로 인해 적응증이 복잡한 열상, 방사형 열상, 수평 열상까지 확대되면서 반월판 수복 시스템 시장이 성장하고 있습니다.
GPO, 조달 및 타워/기기와의 번들링으로 인한 비용 압박
현재 GPO는 미국 병원 지출의 2,500억 달러 이상에 영향을 미치고 있으며, 수복용 기기와 관절경 타워를 묶어 판매함으로써 두 자릿수 할인율을 협상하고 있습니다. 제품 포트폴리오가 좁은 중견 공급업체들은 이익률 압박과 처방 목록에서 제외되는 상황에 직면해 있습니다. 제한된 예산으로 운영되는 ASC(외래수술센터(ASC))는 재처리 비용을 최소화할 수 있는 일회용 키트를 선호하지만, 그로 인해 제조 비용은 증가합니다. 이러한 동향으로 인해 반월판 수복 시스템 시장의 단기적인 가격 결정력은 억제되고 있습니다.
부문별 분석
2025년에는 올인사이드 시스템이 반월판 복원 시스템 시장 규모의 38.30%를 차지하며 해당 부문 매출을 주도했으며, 연평균 성장률(CAGR) 15.40%로 성장하고 있습니다. 매듭 없는 올서셔(All-Saturation) 구조는 하드웨어로 인한 합병증을 배제하고, 표준적인 전내측 및 전외측 포털만 필요로 하므로 수술 시간을 단축합니다. 인사이드아웃법은 최종 파단 하중값이 약간 더 높다는 이유로 학술계 외과의들 사이에서 틈새 시장을 유지하고 있지만, 시신 실험 데이터가 생체역학적 동등성을 보여주고 있기 때문에 그 점유율은 점차 줄어들고 있습니다. 한때 전각 파열 치료에 널리 사용되던 아웃사이드-인 기법은 올-인사이드 기기가 더 적은 절개로 동일한 병변을 치료할 수 있게 되면서 그 인기를 잃어가고 있습니다. 별도로 추적되고 있는 하위 범주인 치근 수복은 가장 빠르게 발전하고 있는 미세 분야입니다. 2024년부터 2025년에 승인된 전용 풀아웃 시스템을 통해 고정 재현성이 확보되었습니다. 봉합사와 압축 임플란트 또는 생체 스캐폴드를 결합한 하이브리드 복원법이 초기 도입 단계에 접어들었으며, 재수술이 필요한 경우나 조직의 질이 낮은 증례를 대상으로 하여 반월판 수복 시스템 시장에 프리미엄 가격대를 추가하고 있습니다.
이 시장의 확산은 외과의를 대상으로 한 교육, 가상현실(VR) 시뮬레이션, 그리고 예비 천공 절차를 생략할 수 있는 셀프 펀칭 팁 등의 설계 개선을 통해 촉진되고 있습니다. 각 제조업체는 ASC(외래수술센터(ASC))의 업무 흐름에 맞추어, 멸균 처리된 일회용 트레이에 임플란트를 포장하고 있습니다. 신뢰성, 학습 곡선의 단축, 처리 능력 향상이 맞물리면서 올인사이드 디바이스는 병원 및 수술센터의 설비 투자 계획에서 계속해서 핵심적인 위치를 차지하고 있으며, 반월판 복원 시스템 시장에서 그 주도적 지위를 확고히 하고 있습니다.
지역별 분석
북미는 2025년, 높은 관절경 수술 보급률, 폭넓은 스포츠 참여, 그리고 세계에서 가장 빠른 규제 사이클에 힘입어 반월판 수복 시스템 시장의 42.13%를 차지했습니다. FDA는 2025년부터 2026년에 걸쳐 여러 차세대 시스템을 승인함으로써, 지역 외과의사들이 매듭 없는 기술 및 치근 특이적 기술을 조기에 활용할 수 있게 되었습니다. ASC로의 전환은 순조롭게 진행되고 있으며, 보험사들은 저비용 의료 환경과 종합적 지불 방식을 선호하는 경향을 보이고 있습니다. 이는 수술 건수를 지속적으로 늘리고, 프리로드 키트의 프리미엄 가격을 유지하는 구조적인 촉진요인이 되고 있습니다.
유럽의 성장은 탄탄한 외과 의사 연수 네트워크와 국민건강보험 제도 덕분에 안정적이지만, 평균 2.5년이 소요되는 의료기기 규정(MDR) 심사 기간으로 인한 마찰에 직면해 있습니다. 인증 지연으로 인한 제품 시장 철수는 간헐적인 공급 부족을 초래하며, 풍부한 규제 대응 자원을 보유한 기존 기업들에게 유리하게 작용하고 있습니다. 그럼에도 불구하고 독일, 영국, 프랑스는 여전히 고부가가치 시장이며, 적절하게 관리되는 등록 기관이 이식 수술의 효과를 뒷받침하는 장기 데이터를 제공하고 있기 때문에 중앙 집중식 입찰로 인한 가격 압박이 커지는 상황에서도 수요는 견조한 추세를 보이고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 연평균 성장률(CAGR)은 15.12%로 전망됩니다. 중국은 3등급 정형외과 의료기기의 승인 절차를 간소화하여, 다국적 기업과 현지 기업 모두에게 ‘올인사이드’ 플랫폼의 비용 경쟁력 있는 버전을 출시할 수 있도록 지원하고 있습니다. 인도는 보험 적용 범위 확대와 2급 도시의 외과 인프라에 대한 정부 투자의 혜택을 누리고 있습니다. 일본과 한국은 이미 고도의 관절경 수술 체계를 갖추고 있으며, 근부 특이적 복원술과 하이브리드 복원술의 조기 도입이 진행되고 있습니다. 한편, 호주에서는 스포츠 문화가 뿌리내려 안정적인 수요를 유지하고 있습니다. 중동 및 아프리카 및 남미는 여전히 개발도상국이지만, 걸프협력회의(GCC) 회원국과 브라질, 아르헨티나의 사립 병원들이 최신 관절경 수술실을 도입함에 따라 그 성장세가 가속화되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.06.22According to Mordor Intelligence, the meniscus repair systems market size is projected to expand from USD 0.7 billion in 2025 and USD 0.79 billion in 2026 to USD 1.49 billion by 2031, registering a CAGR of 13.49% between 2026 to 2031.
This report is Segmented by Procedure Technique (All-Inside, Inside-Out, Outside-In, Meniscal Root Repair, Hybrid/Augmented Repairs), End User (Hospitals, Ambulatory Surgical Centers (ASCs), and Specialty Orthopedic Clinics), Tear Type (Radial, Vertical Longitudinal, Horizontal Cleavage, and More), and Geography (North America, Europe, and More). Market Forecasts are Provided in Terms of Value (USD).
Global Meniscus Repair Systems Market Trends and Insights
Shift From Meniscectomy to Repair to Reduce OA Progression and Preserve Function
A 2024 meta-analysis found that meniscal repair reduced the 10-year incidence of radiographic osteoarthritis by 51% compared with partial meniscectomy . The data spurred orthopedic societies in North America and Europe to update their guidelines in favor of repair. Payers are realigning reimbursement, and bundled payment models are rewarding centers that opt for preservation. As value-based contracts proliferate, surgeons are increasingly repairing tears once considered marginal, propelling the meniscus repair systems market.
All-Inside and Knotless All-Suture Systems Enable Broader Tear Indications
Biomechanical studies show that knotless all-suture repairs achieve 98.6% deployment success with only 6.35% failure rates across diverse tears . FDA clearances for Arthrex FiberTak (March 2025) and GMReis MENISCUS VERSAFLEX (February 2026) cement regulatory confidence. The simplified workflow-fewer portals, no risk of hardware removal, and shorter operative time-has widened indications to include complex, radial, and horizontal cleavage tears, expanding the meniscus repair systems market.
Cost Pressure From GPOs, Procurement, and Bundling with Towers/Instruments
GPOs now influence more than USD 250 billion in U.S. hospital spending and negotiate double-digit discounts by bundling repair devices with arthroscopy towers. Mid-tier suppliers with narrow portfolios face margin compression or exclusion from formularies. ASCs, operating on lean budgets, prefer single-use kits that minimize reprocessing costs but increase manufacturing costs. These dynamics temper near-term pricing power in the meniscus repair systems market.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Arthroscopy Volumes and Sports Injury Incidence
- Outpatient/ASC Adoption Accelerating Knee Arthroscopy Throughput
- Long-Term Repair Failure/Rehab Burden in Complex/Degenerative Tears
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
All-inside systems dominated segment revenue with 38.30% of the meniscus repair systems market size in 2025 and are growing at a 15.40% CAGR. Knotless all-suture constructs eliminate hardware complications and require only standard anteromedial and anterolateral portals, reducing operative time. Inside-out methods retain a niche among academic surgeons citing marginally higher ultimate load-to-failure values, yet share is eroding as cadaveric data show biomechanical parity. Outside-in techniques, once preferred for anterior horn tears, are losing traction because all-inside devices can treat the same pathology through fewer incisions. Root repair, a subset tracked separately, is the fastest-advancing micro-segment; dedicated pull-out systems cleared in 2024-2025 have made fixation reproducible. Hybrid repairs that pair sutures with compression implants or biologic scaffolds are entering early adoption, targeting revision or poor-quality tissue cases and adding premium price layers to the meniscus repair systems market.
Market adoption is reinforced by surgeon education, virtual-reality simulation, and design enhancements such as self-punching tips that remove pre-drilling steps. Manufacturers are packaging implants in sterile, single-use trays aligned with ASC workflows. The interplay of reliability, shorter learning curves, and throughput gains keeps all-inside devices at the center of capital planning for hospitals and surgery centers alike, securing their lead within the meniscus repair systems market.
Geography Analysis
North America commanded 42.13% of the meniscus repair systems market in 2025, driven by high arthroscopy penetration, broad sports participation, and the world's fastest regulatory cycle. The FDA cleared multiple next-generation systems in 2025-2026, giving regional surgeons early access to knotless and root-specific technologies. ASC migration is well advanced; payers favor lower-cost settings and bundled payments, a structural driver that continues to lift procedure volumes and sustain premium pricing for pre-loaded kits.
Europe's growth is steadied by robust surgeon training networks and universal coverage, but faces friction from Medical Device Regulation timelines averaging 2.5 years . Device withdrawals due to certification backlog create intermittent supply gaps that favor incumbents with deep regulatory resources. Nonetheless, Germany, the United Kingdom, and France remain high-value markets where well-maintained registries furnish long-term data supporting repair, anchoring demand even as pricing pressure from centralized tenders intensifies.
Asia-Pacific is the fastest-growing region, posting a projected 15.12% CAGR. China streamlined Class III orthopedic approvals, encouraging both multinationals and local firms to launch cost-matched versions of all-inside platforms. India benefits from rising insurance coverage and government investment in tier-2 city surgical infrastructure. Japan and South Korea, already saturated with advanced arthroscopy capacity, are early adopters of root-specific and hybrid repairs, while Australia's sports culture sustains steady volume. Middle East & Africa and South America remain nascent but gain traction as private hospitals in the Gulf Cooperation Council, Brazil, and Argentina install modern arthroscopy suites.
- Arcuro Medical
- Arthrex
- Auxein Medical
- Biotek SRL
- Changzhou Toolmed Medical Instrument
- Conmed
- Double Medical Technology
- Healthium Medtech
- Johnson & Johnson
- Karl Storz
- Medacta International SA
- Native Orthopaedics
- Orthovasive
- Sironix
- Smiths Group
- Stryker
- VIMS System
- Zimmer Biomet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Shift From Meniscectomy to Repair to Reduce OA Progression and Preserve Function
- 4.2.2 All-Inside And Knotless All-Suture Systems Enable Broader Tear Indications
- 4.2.3 Increasing Arthroscopy Volumes and Sports Injury Incidence
- 4.2.4 Outpatient/ASC Adoption Accelerating Knee Arthroscopy Throughput
- 4.2.5 Specialized Root-Repair Recognition and Dedicated Systems Expand Addressable Cases
- 4.2.6 Surgeon Education Ecosystems and Technique Standardization Improve Adoption
- 4.3 Market Restraints
- 4.3.1 Cost Pressure from GPOs/Procurement and Bundling with Towers/Instruments
- 4.3.2 Long-Term Repair Failure/Rehab Burden in Complex/Degenerative Tears
- 4.3.3 EU MDR-Driven Product Withdrawals and Intermittent Device Availability in Europe
- 4.3.4 Biomechanical/Chondral-Risk Concerns for Certain Implant Constructs and Techniques
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Procedure Technique
- 5.1.1 All-inside
- 5.1.2 Inside-out
- 5.1.3 Outside-in
- 5.1.4 Meniscal root repair
- 5.1.5 Hybrid/augmented repairs
- 5.2 By End User
- 5.2.1 Hospitals
- 5.2.2 Ambulatory Surgical Centers (ASCs)
- 5.2.3 Specialty Orthopedic Clinics
- 5.3 By Tear Type
- 5.3.1 Radial
- 5.3.2 Vertical longitudinal
- 5.3.3 Horizontal cleavage
- 5.3.4 Complex / bucket-handle
- 5.3.5 Root tears
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.3.1 Arcuro Medical
- 6.3.2 Arthrex
- 6.3.3 Auxein Medical
- 6.3.4 Biotek SRL
- 6.3.5 Changzhou Toolmed Medical Instrument
- 6.3.6 CONMED
- 6.3.7 Double Medical Technology
- 6.3.8 Healthium Medtech
- 6.3.9 Johnson & Johnson
- 6.3.10 KARL STORZ SE & Co. KG
- 6.3.11 Medacta International SA
- 6.3.12 Native Orthopaedics
- 6.3.13 Orthovasive
- 6.3.14 Sironix
- 6.3.15 Smith+Nephew
- 6.3.16 Stryker Corporation
- 6.3.17 VIMS System
- 6.3.18 Zimmer Biomet
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment


