

|
시장보고서
상품코드
2113397
유럽의 수력 터빈 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Hydro Turbine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 따르면 유럽의 수력 터빈 시장 규모는 2025년에 7억 5,579만 달러로 평가되며, 2026년 7억 6,720만 달러에서 2031년까지 8억 3,713만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 1.76%가 될 전망입니다.
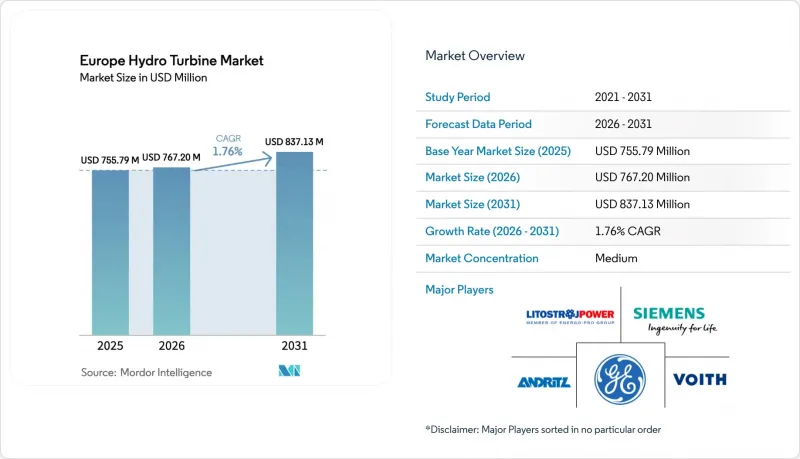
본 보고서는 기술별(반응식 터빈 및 충격식 터빈), 용량(대규모 수력발전, 중규모 수력발전, 소규모·마이크로 수력발전), 설치 형태(신규 건설 및 개보수·현대화), 구성 부품(러너 및 블레이드, 드래프트 튜브 및 기계 부품, 발전기, 제어·디지털 시스템, 기타), 지역(독일, 영국, 프랑스, 이탈리아, 북유럽 국가 등)별로 분류되어 있습니다.
유럽 수력 터빈 시장의 동향 및 인사이트
EU 그린딜은 개보수 및 신규 발전 용량 확대를 가속화하는 것을 목표로 하고 있습니다
2024년에 갱신된 ‘REPowerEU’ 계획은 2030년까지 최종 소비에서 재생에너지 비중을 42.5%로 할 것을 의무화하고 있으며, 유연성 서비스에서 수력발전의 중요성을 명확히 강조하고 있습니다. 2030년까지 5,840억 유로가 투입될 송전망 인프라 지출은 주파수 응답을 강화하는 양수 발전의 상호연결 및 터빈 교체에 자금이 배정되고 있습니다. EU 택소노미에 따르면, 프로젝트가 생태학적 유량 기준을 충족하는 것을 조건으로 개보수 사업이 우대 조치의 대상이 됩니다. 2024년에 승인된 그리스의 680 MW ‘암필로키아’ 계획과 오스트리아의 150 MW ‘에벤제’ 현대화 사업은 부흥 자금이 어떻게 수명 연장을 신속하게 추진하고 있는지를 보여줍니다. 에벤제에서 실시된 가변 속도 개조를 통해 현재는 전 부하에서 예비 출력으로의 전환을 90초 미만으로 실현하고 있으며, 이 서비스는 현재 부대 서비스 입찰에서 1MWh당 15-20유로에 거래되고 있습니다. 이러한 정책 수단이 성숙해짐에 따라, 유럽 수력 터빈 시장에서는 EU 핵심 경제권 전역에서 개조 계약이 지속적으로 발생할 것으로 보입니다.
화력 발전소의 폐쇄가 양수 발전에 의한 안정적인 공급에 대한 수요를 창출하고 있습니다
2024년부터 2025년까지 독일, 영국, 벨기에, 스페인에서는 석탄 화력 및 원자력발전소의 가동 중단으로 인해 12GW의 동기 발전 용량이 상실되었습니다. 이미 46 GW가 도입된 양수식 수력발전은 수명주기 저하를 초래하지 않으면서도 수 시간에 걸쳐 방전을 가능하게 하는 유일한 검증된 기술입니다. 영국의 600 MW 크루아찬 2호기와 스페인의 200 MW 살토 데 치라 프로젝트는 투자자들의 관심이 다시 높아지고 있음을 보여줍니다. 2024년에 가동을 시작한 포르투갈의 1,158 MW 타메가 복합 시설은 이미 국내 균형 조정 예비력의 40%를 공급하고 있습니다. 전력 회사가 계통 안정화를 통한 수익을 추구하는 가운데, 유럽의 수력 터빈 시장은 장시간의 전력 저장을 기반으로 확실한 성장 궤도에 올랐습니다.
장기화되는 환경영향평가(EIA) 및 인허가 절차
신규 댐 건설에 관한 종합적인 환경영향평가(EIA)는, 특히 프로젝트가 ‘나투라 2000’ 구역과 겹치거나 ‘에스포 협약’에 따른 협의가 필요한 경우, 5년에서 7년에 달할 수도 있습니다. 오스트리아에서 계획 중인 900 MW 쿠프타이 확장 프로젝트는 2021년부터 소송이 계속되고 있으며, 생물다양성 관련 문제가 투자를 지연시키고 있는 실례가 되고 있습니다. 스위스의 개정 수질보호법에서는 생물다양성에 대한 ‘순 긍정적 효과’가 요구되게 되었으며, 이에 따라 18-24개월의 신속한 심사를 받는 개보수 공사에 자금이 배정되고 있습니다. 개보수 공사는 심사 기간이 짧은 편이지만, 다운스트림 유량 관리에 관한 공청회로 인해 여전히 일정이 지연될 가능성이 있습니다.
부문별 분석
2025년, 유럽 수력 터빈 시장에서 반응형 터빈은 74.9%를 차지했습니다. 이는 더 높은 부수적 수익을 가져다주는 가변속 발전기에 의해 뒷받침되고 있습니다. 이 부문은 연평균 성장률(CAGR) 1.99%로 확대될 것으로 예측되며, 2031년까지 유럽 수력 터빈 시장 규모에 안정적인 기반이 될 것으로 전망됩니다. 높은 낙차가 있는 알프스 지역 프로젝트에서 펠톤 터빈을 필두로 한 임펄스식 터빈은, 빙하 용해로 인한 유입량 변화가 계절적 수류 패턴을 바꾸면서 다시 활기를 되찾고 있습니다. 공급업체에 따르면, 2024년부터 2025년에 걸친 프랜시스 터빈 수주량의 30%에는 이미 풀 컨버터 구동 시스템이 포함되어 있으며, 이는 2020년의 10%에서 급증한 수치로, 디지털화를 통한 업그레이드가 성능 기준을 재정의하고 있음을 여실히 보여줍니다.
가변 속도 제어를 통해 사업자는 수두 변동에 따라 효율을 미세 조정하고, 주파수 응답 시장에 대한 참여를 두 배로 늘리며, 유지보수 주기를 연장할 수 있게 됩니다. 카플란 터빈의 변형 모델에는 물고기 친화적인 블레이드가 채택되어 있어, 블레이드 충돌로 인한 사망률을 5% 미만으로 낮춤으로써 ‘나투라 2000’ 규정을 쉽게 준수할 수 있게 해줍니다. 타고 터빈은 5MW 미만의 지역 프로젝트에 점차 보급되고 있으며, 컴팩트한 설치 면적과 퇴적물에 대한 내성이 경제적 우위를 가져다주고 있습니다. 계통 운영 사업자가 급격한 출력 변동 대응 및 관성 서비스를 중시하는 가운데, 반응식 터빈 기술은 여전히 유럽 수력 터빈 시장의 주축을 이루고 있지만, 틈새 시장인 임펄스식 유닛은 더 소규모의 기반에서 평균 성장률을 상회하는 속도로 확대될 전망입니다.
100MW를 초과하는 설비는 2025년 매출의 50.1%를 차지했으나, 10MW 미만의 자산은 연평균 성장률(CAGR) 3.33%로 확대될 것으로 예측되며, 기존 초대형 프로젝트를 2대 1에 가까운 비율로 앞지를 전망입니다. 개정된 EU 규정에 따라 10MW 미만 프로젝트의 경우 환경영향평가(EIA)의 완전한 이행이 면제되어 소프트 비용이 대폭 절감되고 건설 주기가 가속화되고 있습니다. 독일, 오스트리아, 스위스의 지역 협동조합은 2024년부터 2025년까지 1억 8,000만 유로를 조달하여, 12년 이내에 투자 회수가 가능한 유수식 수력발전 사업을 지원했습니다. 이러한 동향은 유럽 수력 터빈 시장의 풀뿌리 수준을 뒷받침하는 기반이 되고 있습니다.
모듈식 터빈·발전기 스키드는 현재 공장에서 시험을 마친 상태로 출하되므로, 현장 작업 기간이 18개월에서 6개월로 단축되고, 융자 위험도 경감되고 있습니다. 10MW에서 100MW 규모의 중규모 시설에서는 기존 댐에 다운스트림 측 저수지를 증설하여 하이브리드 저장을 실현하는 개조 계약이 활발히 체결되고 있습니다. 스코틀랜드의 1,500MW급 ‘코이어 글라스(Coire Glas)’와 같은 대규모 프로젝트는 여전히 드물지만 매우 중요하며, 30GWh의 저장 용량을 추가함으로써 해상 풍력발전의 출력 변동을 완화하고 있습니다. 전반적으로, 규모의 다양성으로 인해 양질의 대규모 댐 건설 부지가 감소하고 있음에도 불구하고, 유럽의 수력 터빈 시장은 성장을 지속하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.08.25According to Mordor Intelligence, the Europe hydro turbine market size was valued at USD 755.79 million in 2025 and is estimated to grow from USD 767.20 million in 2026 to reach USD 837.13 million by 2031, at a CAGR of 1.76% during the forecast period (2026-2031).
This report is Segmented by Technology (Reaction Turbines and Impulse Turbines), Capacity (Large Hydro, Medium Hydro, and Small and Micro Hydro), Installation Type (New Build and Refurbishment/Modernisation), Component (Runner and Blades, Draft Tube and Mechanical Parts, Generator, Control and Digital Systems, and Others), and Geography (Germany, United Kingdom, France, Italy, NORDIC Countries, and More).
Europe Hydro Turbine Market Trends and Insights
EU Green Deal Targets Accelerating Refurbishment & Greenfield Capacity
The REPowerEU plan, updated in 2024, mandates 42.5% renewable energy in final consumption by 2030 and explicitly highlights hydropower for flexibility services. Grid-infrastructure spending of EUR 584 billion through 2030 is channeling funds toward pumped-storage interconnections and turbine replacements that strengthen frequency response. Refurbishment enjoys preferential treatment under the EU Taxonomy, provided projects meet ecological-flow standards. Greece's 680 MW Amfilochia scheme, approved in 2024, and Austria's 150 MW Ebensee modernization showcase how recovery funds are fast-tracking lifecycle extensions. Variable-speed upgrades at Ebensee now deliver full-load-to-reserve transitions in under 90 seconds, a service currently priced at EUR 15 to EUR 20 per MWh in ancillary-service auctions. As these policy levers mature, the European hydro turbine market will see a sustained flow of refurbishment contracts across core EU economies.
Retirement of Thermal Plants Creating Demand for Pumped-Storage Stability
Coal and nuclear shutdowns removed 12 GW of synchronous capacity across Germany, the UK, Belgium, and Spain between 2024 and 2025. Pumped-storage hydropower, with 46 GW already installed, is the only proven technology capable of delivering multi-hour discharge without cycle-life degradation. The UK's 600 MW Cruachan 2 and Spain's 200 MW Salto de Chira schemes underscore renewed investor appetite. Portugal's 1,158 MW Tamega complex, commissioned in 2024, already provides 40% of national balancing reserves. As utilities chase grid-stability revenue, the European hydro turbine market gains a dependable growth avenue anchored in long-duration storage.
Lengthy Environmental Impact Assessments and Permitting
Full EIAs for greenfield dams can stretch five to seven years, especially where projects intersect Natura 2000 zones or trigger Espoo Convention consultations. Austria's proposed 900 MW Kuhtai expansion has been in litigation since 2021, illustrating how biodiversity challenges stall investments. Switzerland's revised Water Protection Act now demands net-positive biodiversity outcomes, steering funds toward refurbishments that qualify for expedited 18- to 24-month reviews. Although refurbishment enjoys shorter timelines, public consultations on downstream flow regimes can still delay schedules.
Other drivers and restraints analyzed in the detailed report include:
- Carbon Pricing & Green Finance Improving Hydro ROI
- Fish-Friendly Turbine Designs Easing Biodiversity Approvals
- Price Competitiveness of Utility-Scale Solar + Battery Storage
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Reaction designs accounted for 74.9% of the European hydro turbine market in 2025, supported by variable-speed generators that unlock higher ancillary revenue. This segment is projected to expand at a 1.99% CAGR, assuring a stable anchor for the European hydro turbine market size through 2031. Impulse turbines, led by Pelton wheels in high-head Alpine projects, are regaining momentum as melting-glacier inflows shift seasonal profiles. Suppliers report that 30% of 2024-2025 Francis orders already include full-converter drives, a sharp rise from 10% in 2020, underlining how digital upgrades are redefining performance baselines.
Variable-speed controls allow operators to fine-tune efficiency across fluctuating heads, double participation in frequency-response markets, and extend maintenance intervals. Kaplan variants now integrate fish-friendly blades that reduce blade-strike mortality below 5%, easing Natura 2000 compliance. Turgo turbines are penetrating sub-5 MW community projects where their compact footprint and sediment tolerance offer economic advantages. As grid operators valorize rapid ramping and inertia services, reaction technology remains the backbone of the European hydro turbine market, yet niche impulse units will outpace average growth from a smaller base.
Installations above 100 MW retained 50.1% of 2025 revenue, but sub-10 MW assets are forecast to expand at a 3.33% CAGR, outpacing legacy giants by nearly two-to-one. Revised EU rules waive full EIAs for projects below 10 MW, slashing soft costs and accelerating build cycles. Community cooperatives in Germany, Austria, and Switzerland raised EUR 180 million between 2024 and 2025 to back run-of-river ventures that repay in under 12 years, a trend that anchors the grassroots tier of the European hydro turbine market.
Modular turbine-generator skids now ship factory-tested, reducing on-site works from 18 months to 6 months and de-risking loans. Medium facilities from 10 MW to 100 MW are thriving on refurbishment contracts that pair existing dams with lower-reservoir additions for hybrid storage. Large projects such as Scotland's 1,500 MW Coire Glas remain rare but critical, adding 30 GWh of storage to smooth offshore-wind swings. In aggregate, scale diversity ensures the European hydro turbine market continues growing even as prime large-dam sites vanish.
Complete Report Scope:
- By Technology
- Reaction Turbines
- Impulse Turbines
- By Capacity
- Large Hydro (Above 100 MW)
- Medium Hydro (10 to 100 MW)
- Small and Micro Hydro (Below 10 MW)
- By Installation Type
- New Build
- Refurbishment/Modernisation
- By Component
- Runner and Blades
- Draft Tube and Mechanical Parts
- Generator
- Control & Digital Systems
- Others
- By Geography
- Germany
- United Kingdom
- France
- Italy
- Spain
- NORDIC Countries
- Russia
- Rest of Europe
List of Companies Covered in this Report:
- Andritz AG
- Voith GmbH & Co. KGaA
- General Electric Co. (GE Vernova)
- Siemens Energy AG
- Litostroj Power Group
- Toshiba Energy Systems
- Alstom Hydro France
- Rainpower (SnPower)
- Canadian Hydro Components
- Norcan Hydraulic Turbine
- Gilkes & Co.
- Kirloskar Brothers
- IMPSA
- Harbin Electric Machinery
- BHEL
- CJ Turbines
- Hidrostal AG
- Voith Hydro Ocean Current
- Global Hydro Energy
- Energy Namibia Hydro
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Scope of the Study
- 1.2 Study Assumptions & Market Definition
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU Green Deal targets accelerating refurbishment & greenfield capacity
- 4.2.2 Retirement of thermal plants -> demand for pumped-storage stability
- 4.2.3 Carbon pricing & green finance improving hydro ROI
- 4.2.4 Fish-friendly turbine designs easing biodiversity approvals
- 4.2.5 Digital-twin O&M lowering OPEX for small utilities
- 4.2.6 Corporate renewable PPAs from data-center operators
- 4.3 Market Restraints
- 4.3.1 Lengthy Environmental Impact Assessments (EIA) and permitting
- 4.3.2 Price competitiveness of utility-scale solar + battery storage
- 4.3.3 Litigation against Alpine dam expansions
- 4.3.4 Specialty-steel supply shocks raising CAPEX volatility
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape (EU Water Framework, taxonomy, etc.)
- 4.6 Technological Outlook (variable-speed, additive manufacturing)
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Technology
- 5.1.1 Reaction Turbines
- 5.1.2 Impulse Turbines
- 5.2 By Capacity
- 5.2.1 Large Hydro (Above 100 MW)
- 5.2.2 Medium Hydro (10 to 100 MW)
- 5.2.3 Small and Micro Hydro (Below 10 MW)
- 5.3 By Installation Type
- 5.3.1 New Build
- 5.3.2 Refurbishment/Modernisation
- 5.4 By Component
- 5.4.1 Runner and Blades
- 5.4.2 Draft Tube and Mechanical Parts
- 5.4.3 Generator
- 5.4.4 Control & Digital Systems
- 5.4.5 Others
- 5.5 By Geography
- 5.5.1 Germany
- 5.5.2 United Kingdom
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 NORDIC Countries
- 5.5.7 Russia
- 5.5.8 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Andritz AG
- 6.4.2 Voith GmbH & Co. KGaA
- 6.4.3 General Electric Co. (GE Vernova)
- 6.4.4 Siemens Energy AG
- 6.4.5 Litostroj Power Group
- 6.4.6 Toshiba Energy Systems
- 6.4.7 Alstom Hydro France
- 6.4.8 Rainpower (SnPower)
- 6.4.9 Canadian Hydro Components
- 6.4.10 Norcan Hydraulic Turbine
- 6.4.11 Gilkes & Co.
- 6.4.12 Kirloskar Brothers
- 6.4.13 IMPSA
- 6.4.14 Harbin Electric Machinery
- 6.4.15 BHEL
- 6.4.16 CJ Turbines
- 6.4.17 Hidrostal AG
- 6.4.18 Voith Hydro Ocean Current
- 6.4.19 Global Hydro Energy
- 6.4.20 Energy Namibia Hydro
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


