

|
시장보고서
상품코드
2113411
이동식 파쇄기 및 선별기 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Mobile Crushers And Screeners - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
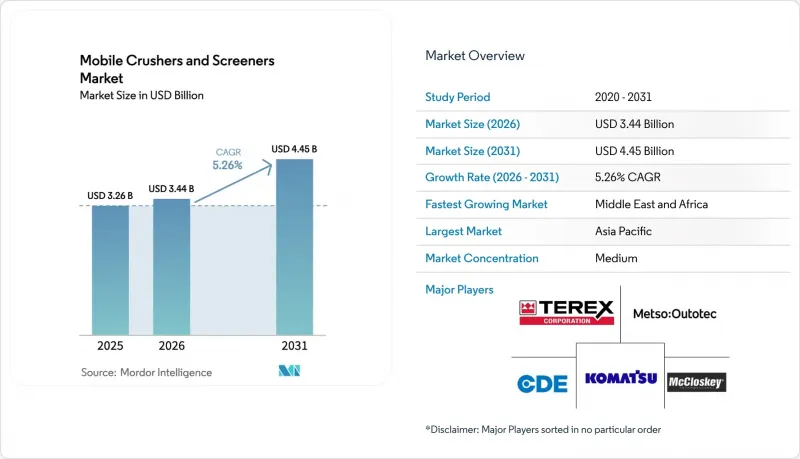
에 따르면 이동식 파쇄기 및 선별기 시장 규모는 2025년 32억 6,000만 달러에서 2026년에는 34억 4,000만 달러로 확대되어 2031년까지 44억 5,000만 달러에 달할 것으로 예상되며, 2026년부터 2031년까지 CAGR 5.26%로 성장할 것으로 전망됩니다.
본 보고서는 유형별(신품 및 재생품), 기계 유형별(이동식 파쇄기 및 이동식 선별기), 최종사용자 산업별(광업·야금, 골재 처리, 재활용 등), 처리 능력 범위별(200 T/H 이하 및 그 이상), 동력원별(디젤·유압식 및 완전 전기식), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 이동식 파쇄기 및 선별기 시장의 동향 및 인사이트
운반 비용 절감을 위한 현장 파쇄 수요 증가
이동식 조 크러셔나 콘 크러셔가 굴착 현장에서 불과 몇 미터 떨어진 곳에 설치되는 사례가 늘어나고 있으며, 이를 통해 운송 트럭의 디젤 소비량을 줄이고 프로젝트 기간을 최대 4분의 1까지 단축하고 있습니다. 렌탈 업체들은 30일 단위로 계약하여 파견할 수 있는 다양한 기종을 갖춘 차량단을 확대하고 있으며, 기존에는 50만-150만 달러의 자본 지출이었던 것을 예측 가능한 운영비로 전환하고 있습니다. 썬벨트 렌탈스는 2024년 4월 결산기에 89억 8,000만 파운드(114억 달러)의 매출을 기록하며, 자사 장비군의 높은 가동률을 입증하고 있습니다. 미국 노동통계국이 예측한 건설기계 운전사 수의 지속적인 증가는 장기적인 기계 수요를 더욱 뒷받침하고 있습니다.
도시화에 따른 건설 부문의 확대
인도, 인도네시아 및 걸프 국가들의 도시 철도, 고속도로, 브라운필드 재개발 프로젝트에서는 건설 단계의 진척에 맞춰 매주 이동이 가능한 궤도식 분쇄기가 점점 더 선호되고 있습니다. 인도의 ‘국가 인프라 파이프라인’에서는 2025년까지의 프로젝트에 1조 4,000억 달러가 배정되어 있습니다. 또한, 이동식 선별기는 고정식 플랜트가 차지하고 있던 2,000-3,000제곱미터의 귀중한 도시 용지를 확보해 줍니다. 이는 구역 지정 규제로 인해 중공업의 부지 면적이 제한되는 지역에서 결정적인 이점이 됩니다.
높은 초기 투자 비용
중형 이동식 파쇄기의 가격은 50만-150만 달러로, 설비 대출 금리가 여전히 높은 지역에서는 구매자에게 장벽이 되고 있습니다. 많은 아프리카 및 동남아시아 국가에서는 건설기계 지출에서 임대 이용률이 여전히 15% 미만에 머물러 있어, 최신형 저공해 차량의 도입을 저해하고 있습니다. 메츠오(Metso)와 같은 OEM 제조업체들은 용도별 투자액을 절감할 수 있는 모듈식 플랫폼을 판매하고 있지만, 국제통화기금(IMF)의 전망에서 지적된 높은 차입 비용으로 인해 일괄 구매는 계속해서 미뤄지고 있습니다.
부문 분석
2025년에는 재생 장비가 이동식 파쇄기 및 선별기 시장에서 점유율을 확대하여 2031년까지 연평균 성장률(CAGR) 6.90%로 성장할 것으로 예측됩니다. 이 부문은 신제품 성능의 최대 90%를 40-60% 낮은 비용으로 실현하는 인증 재생 프로그램의 혜택을 받고 있습니다. 캐터필러의 리매뉴팩처링 부문은 2023년에 1억 4,700만 파운드의 반환 자재를 처리하여 88%의 핵심 부품 회수율을 달성했습니다. 이는 배출량 보고 의무화와 부합하는 폐쇄형 공급망을 뒷받침하는 것입니다.
렌탈 사업자들은 이러한 가격 차이를 활용하여 단기 계약에는 재생 제품을, 장기 리스에는 신제품을 배정함으로써 전체 고객 부문에서 자산 활용을 최적화하고 있습니다. 매출의 대부분은 여전히 신제품이 차지하고 있지만, 수명주기 경제성, 매립 처리 비용 및 유럽연합(EU)의 순환 경제 관련 법규를 고려할 때, 재생 제품 시장은 지속적인 성장세를 보일 것으로 예상됩니다. 전반적으로, 재생 제품 판매와 관련된 이동식 파쇄기 및 선별기 시장 규모는 총 수요 증가율을 웃도는 속도로 확대될 전망입니다.
이동식 스크리너의 연평균 성장률(CAGR)은 5.81%로 예측되며, 이는 분쇄기의 5.26%를 상회할 전망입니다. 저전력 소비라는 장점 덕분에 진동식 모델이 주류를 이루고 있지만, 철광석이나 석탄의 처리 공정에서는 데크의 막힘으로 인해 직선식 스크리너의 처리 능력이 제한되기 때문에 높은 처리 능력을 갖춘 자이로트리식 스크리너의 점유율이 확대되고 있습니다. EU 지침 2018/851은 건설 및 해체 폐기물의 70% 회수를 의무화하고 있어, 범용성이 높은 선별 플랜트에 의존하는 현장에서의 분리 작업을 촉진하고 있습니다.
각 OEM 업체들은 풍력 선별기나 자력 분리기를 스크린 섀시에 통합하여, 단일 용도의 기계를 다단계 처리기로 전환하고 있습니다. Kleemann사의 10.5 m² 3단식 ‘MOBISCREEN MSS 1102 PRO’는 이러한 추세를 상징하는 제품으로, 건설업체는 자재를 중간 운송할 필요 없이 도로 노반 사양을 충족하는 재생 콘크리트 골재를 제조할 수 있게 됩니다. 이러한 혁신은 이동식 파쇄기 및 선별기 시장이 단순한 파쇄에서 부가가치가 있는 선별로 중심을 옮기고 있는 배경이 되고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 42.11%를 차지하고 있으며, 중국, 인도, 인도네시아에서는 철도, 도로, 저렴한 주택 건설에 막대한 투자가 이루어지고 있습니다. 이 지역은 대규모 채석 사업과 도시 재개발의 혜택을 모두 누리고 있어 설비의 안정적인 갱신이 보장되고 있습니다. 호주에서는 철광석 채굴 확대에 따라 시간당 500톤을 초과하는 분쇄기 조달이 계속되고 있는 반면, 동남아시아 국가들에서는 좁은 작업 현장에서도 대응 가능한 중용량 장비가 선호되고 있습니다.
중동 및 아프리카는 콩고 민주 공화국, 잠비아, 짐바브웨에서의 리튬 및 코발트 채굴이 확대됨에 따라 5.98%라는 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다. 이동식 플랜트는 영구적인 인프라가 완공되기 전에 조기 현금 흐름 창출을 가능하게 하며, 로비토-애틀랜틱 철도의 최근 개량으로 수출의 경제성이 더욱 향상되고 있습니다. 수력발전 및 물류 회랑에 대한 자금 지원으로 오프그리드 디젤 유압식 및 하이브리드 기계에 대한 지속적인 수요가 뒷받침되고 있습니다.
북미는 높은 임대 이용률과 현재 ‘인프라 투자 및 고용법’의 예산 배정을 통해 개보수가 진행되고 있는 노후화된 주간 고속도로망 덕분에 매출 규모에서 2위를 차지하고 있습니다. 유럽의 성숙한 건설 부문에서는 전반적인 성장이 둔화되고 있지만, 엄격한 배기가스 규제로 인해 하이브리드차 및 전기자동차로의 차량 교체가 가속화되고 있으며, 이는 이동식 파쇄기 및 선별기 시장의 교체 수요를 뒷받침하고 있습니다. 남미와 중동은 각각 브라질의 광업 확대와 사우디아라비아의 메가 프로젝트에 힘입어 전 세계 매출을 보완하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.08.25According to Mordor Intelligence, the mobile crushers and screeners market size is expected to increase from USD 3.26 billion in 2025 to USD 3.44 billion in 2026 and reach USD 4.45 billion by 2031, growing at a CAGR of 5.26% over 2026-2031.
This report is Segmented by Type (New, and Refurbished), Machinery Type (Mobile Crushers, and Mobile Screeners), End-User Industry (Mining and Metallurgy, Aggregate Processing, Recycling, and More), Capacity Range (Up To 200 T/H, and More), Power Source (Diesel-Hydraulic, and Fully Electric), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Mobile Crushers And Screeners Market Trends and Insights
Growing Demand for On-Site Crushing to Cut Hauling Costs
Mobile jaw and cone crushers are increasingly stationed within meters of excavation faces, trimming diesel consumption for haul trucks and shortening project schedules by up to one quarter. Rental companies are scaling mixed fleets that can be dispatched on 30-day contracts, converting what was a USD 500,000-USD 1.5 million capital outlay into a predictable operating expense. Sunbelt Rentals generated GBP 8.98 billion (USD 11.4 billion) in the fiscal year ended April 2024, underscoring robust fleet utilization. Persistent construction-equipment operator growth projected by the U.S. Bureau of Labor Statistics further supports long-term equipment demand.
Expansion of Construction Sector Amid Urbanization
Metro rail, expressway, and brownfield redevelopment projects across India, Indonesia, and the Gulf states increasingly favour track-mounted crushers that can be relocated weekly as building phases advance. India's National Infrastructure Pipeline earmarked USD 1.4 trillion for projects through 2025. Mobile screeners also free 2,000-3,000 square meters of scarce city land otherwise occupied by stationary plants, a decisive advantage where zoning restricts heavy industrial footprints.
High Initial Capital Expenditure
Mid-capacity mobile crushers cost USD 500,000-USD 1.5 million, a hurdle for buyers in regions where equipment-finance interest rates remain elevated. Rental penetration still sits below 15% of construction-equipment spending in many African and Southeast Asian nations, hampering access to modern low-emission fleets. Although OEMs such as Metso now market modular platforms that reduce investment per application, high borrowing costs identified in International Monetary Fund outlooks continue to defer outright purchases.
Other drivers and restraints analyzed in the detailed report include:
- Rising Mineral Extraction in Emerging Economies
- Adoption of Hybrid-Electric Mobile Crushers for Emission Compliance
- Volatility in Raw Material Prices Impacting Equipment Cost
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Refurbished equipment accounted for a growing slice of the mobile crushers and screeners market in 2025 and is projected to climb at a 6.90% CAGR through 2031. The segment benefits from certified rebuild programs that deliver up to 90% of new-unit performance at 40-60% lower cost. Caterpillar's remanufacturing division processed 147 million pounds of returned material in 2023, achieving an 88% core-return rate and underscoring a closed-loop supply chain that resonates with emission-reporting mandates.
Rental fleets exploit the price gap by reserving refurbished units for short-term contracts and deploying new machines on long-duration leases, thereby optimizing asset utilization across customer segments. Although new machines still hold the majority of revenue, lifecycle economics, landfill-disposal fees, and circular-economy legislation in the European Union suggest sustained momentum for rebuilds. Overall, the mobile crushers and screeners market size tied to refurbished sales is likely to rise faster than headline demand.
Mobile screeners logged a 5.81% CAGR outlook, eclipsing crushers' 5.26% trajectory. Vibratory models dominate thanks to low power draw, but high-tonnage gyratory screeners are gaining share in iron-ore and coal circuits where deck blinding limits linear-screen throughput. EU Directive 2018/851 mandates 70% recovery of construction and demolition waste, driving onsite separation workflows that hinge on versatile screening plants.
OEMs are integrating wind sifters and magnetic separators into screen chassis, converting single-purpose machines into multi-fraction processors. Kleemann's 10.5 m2 triple-deck MOBISCREEN MSS 1102 PRO exemplifies the trend, enabling contractors to create recycled concrete aggregate that meets road-base specifications without trans-shipping material. Such innovations underpin the mobile crushers and screeners market's pivot toward value-adding separation rather than pure size reduction.
Complete Report Scope:
- By Type
- New
- Refurbished
- By Machinery Type
- Mobile Crushers
- Jaw Crushers
- Cone Crushers
- Impact Crushers
- Other Mobile Crushers
- Mobile Screeners
- Vibratory Screeners
- Gyratory Screeners
- Other Mobile Screeners
- Mobile Crushers
- By End-User Industry
- Mining and Metallurgy
- Aggregate Processing
- Recycling
- Construction and Infrastructure
- Other End-User Industries
- By Capacity Range
- Up to 200 t/h
- 200-500 t/h
- Above 500 t/h
- By Power Source
- Diesel-Hydraulic
- Hybrid-Electric
- Fully Electric
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia Pacific anchored 42.11% of 2025 revenue, with China, India, and Indonesia investing heavily in rail, road, and affordable housing. The region benefits from both large-scale quarrying and urban redevelopment, ensuring steady equipment turnover. Australia continues to procure above-500 t/h crushers for iron-ore expansions, while Southeast Asian nations prefer mid-capacity units that can navigate tighter job sites.
Middle East and Africa is expected to post the fastest 5.98% CAGR as lithium and cobalt extraction scales in the Democratic Republic of Congo, Zambia, and Zimbabwe. Mobile plants permit early cash-flow generation ahead of permanent infrastructure completion, and recent upgrades to the Lobito Atlantic Railway further enhance export economics. Funding for hydropower and logistics corridors supports sustained demand for off-grid diesel-hydraulic and hybrid machines.
North America represents the second-largest revenue pool thanks to high rental penetration and an aging interstate network currently under rehabilitation via Infrastructure Investment and Jobs Act allocations. Europe's mature construction sector shows slower aggregate growth, but stringent emission standards accelerate fleet renewal toward hybrid and electric models, underpinning replacement demand within the mobile crushers and screeners market. South America and the Middle East round out global sales, driven by Brazilian mining expansions and Saudi megaprojects respectively.
- Metso Oyj
- Sandvik AB
- Terex Corporation
- Kleemann GmbH
- Komatsu Ltd.
- Astec Industries Inc.
- Keestrack NV
- McCloskey International Limited
- Rubble Master HMH GmbH
- Epiroc AB
- CDE Global Ltd.
- SBM Mineral Processing GmbH
- thyssenkrupp AG
- IROCK Crushers LLC
- Tesab Engineering Ltd.
- Anaconda Equipment International Ltd.
- Eagle Crusher Company Inc.
- Screencore US LLC
- Portafill International Ltd.
- Maximus Crushing and Screening Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Demand for On-Site Crushing to Cut Hauling Costs
- 4.2.2 Expansion of Construction Sector amid Urbanization
- 4.2.3 Rising Mineral Extraction in Emerging Economies
- 4.2.4 Adoption of Hybrid-Electric Mobile Crushers for Emission Compliance
- 4.2.5 Rental Fleet Expansion Driven by Asset-Light Strategies
- 4.2.6 Integration of Telematics Enabling Predictive Maintenance
- 4.2.7 Increase in Micro-Mobility Construction Projects in Remote Terrains
- 4.2.8 Government Stimulus for Circular Economy-Driven Demolition Waste Recycling
- 4.3 Market Restraints
- 4.3.1 High Initial Capital Expenditure
- 4.3.2 Volatility in Raw Material Prices Impacting Equipment Cost
- 4.3.3 Permitting Hurdles for Mobile Plant Deployment in Urban Zones
- 4.3.4 Skilled Operator Shortage Limiting Utilization Rates
- 4.3.5 Battery-Raw-Material Supply Risk for Fully Electric Models
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 New
- 5.1.2 Refurbished
- 5.2 By Machinery Type
- 5.2.1 Mobile Crushers
- 5.2.1.1 Jaw Crushers
- 5.2.1.2 Cone Crushers
- 5.2.1.3 Impact Crushers
- 5.2.1.4 Other Mobile Crushers
- 5.2.2 Mobile Screeners
- 5.2.2.1 Vibratory Screeners
- 5.2.2.2 Gyratory Screeners
- 5.2.2.3 Other Mobile Screeners
- 5.2.1 Mobile Crushers
- 5.3 By End-User Industry
- 5.3.1 Mining and Metallurgy
- 5.3.2 Aggregate Processing
- 5.3.3 Recycling
- 5.3.4 Construction and Infrastructure
- 5.3.5 Other End-User Industries
- 5.4 By Capacity Range
- 5.4.1 Up to 200 t/h
- 5.4.2 200-500 t/h
- 5.4.3 Above 500 t/h
- 5.5 By Power Source
- 5.5.1 Diesel-Hydraulic
- 5.5.2 Hybrid-Electric
- 5.5.3 Fully Electric
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Australia and New Zealand
- 5.6.4.6 Rest of Asia Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Egypt
- 5.6.6.3 Nigeria
- 5.6.6.4 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Metso Oyj
- 6.4.2 Sandvik AB
- 6.4.3 Terex Corporation
- 6.4.4 Kleemann GmbH
- 6.4.5 Komatsu Ltd.
- 6.4.6 Astec Industries Inc.
- 6.4.7 Keestrack NV
- 6.4.8 McCloskey International Limited
- 6.4.9 Rubble Master HMH GmbH
- 6.4.10 Epiroc AB
- 6.4.11 CDE Global Ltd.
- 6.4.12 SBM Mineral Processing GmbH
- 6.4.13 thyssenkrupp AG
- 6.4.14 IROCK Crushers LLC
- 6.4.15 Tesab Engineering Ltd.
- 6.4.16 Anaconda Equipment International Ltd.
- 6.4.17 Eagle Crusher Company Inc.
- 6.4.18 Screencore US LLC
- 6.4.19 Portafill International Ltd.
- 6.4.20 Maximus Crushing and Screening Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


