

|
시장보고서
상품코드
2114105
육상 시추 리그 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Land Drilling Rig - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
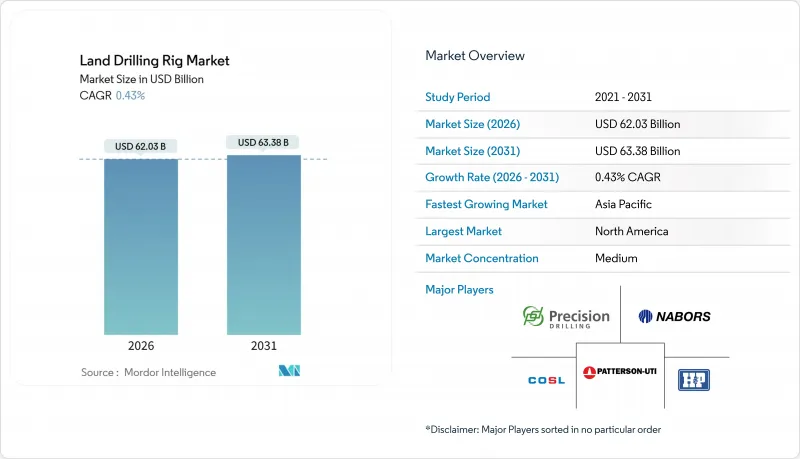
에 의하면, 육상 시추 리그 시장 규모는 2026년에 620억 3,000만 달러로 추정되고, 예측 기간(2026-2031년) CAGR 0.43%로 성장을 지속할 것으로 예측되며, 2031년에는 633억 8,000만 달러에 이를 전망입니다.
본 보고서는 시추 리그 유형별(기존, 이동식/바퀴 장착형, 워킹 슈퍼 스펙), 구동 시스템별(기계식, 전기식, 하이브리드/복합식), 정격 마력별(1,000 HP 이하, 1,000-1,499 HP, 1,500 HP 이상), 용도별(기존 석유, 지열, 신흥 천연수소 등), 지역별(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)로 분류되어 있습니다.
세계의 육상 시추 리그 시장 동향 및 인사이트
1,500 HP 이상의 ‘슈퍼 스펙’ 채택
1,500 HP를 초과하는 슈퍼 스펙 플랫폼은 현재 복잡한 비전통 유전에서 주류를 이루고 있으며, 15,000피트를 초과하는 수평 유정의 시추를 가능하게 하고, 기존 유닛에 비해 총 시추 시간을 최대 30% 단축하고 있습니다. 미국 FlexRig사가 소유한 시추 장비군은 2025년에 하루 평균 2만 8,500달러의 일당을 기록했습니다. 이는 7,500 psi 펌프와 750톤 탑 드라이브를 탑재하고 있어 3,000달러의 프리미엄이 정당화됩니다. 미국 내 도입의 약 60%는 퍼미안 분지를 대상으로 하며, 이 지역에서는 더 깊은 울프캠프층 시추에 높은 토크가 요구됩니다. ADNOC Drilling사도 이러한 추세를 따라 고압의 자프라 가스전을 위해 12기의 슈퍼 스펙 리그를 추가했습니다. 1기당 2,500만 달러를 초과하는 경우가 많은 고액의 초기 설비 투자(CAPEX)로 인해, 소유권은 자금력이 있는 운영사로 계속 제한되고 있습니다.
셰일 및 기타 비전통 매장량
비전통적 시추는 평가 단계에서 양산 모드로 전환되고 있으며, 육상 시추 리그 시장의 기초적인 수요를 뒷받침하고 있습니다. 아르헨티나의 바카 무에르타에서는 YPF와 그 파트너 기업들이 1,200-1,500 HP의 시추 장비를 사용하여 액체가 풍부한 더 깊은 층을 시추한 결과, 2025년 말까지 일일 50만 배럴의 생산량을 달성하여 2년 만에 56% 증가했습니다. 미국은 수송 능력과 시추를 뒷받침하는 인프라의 혜택을 받아 여전히 전 세계 비전통적 활동의 40%를 차지하고 있습니다. 호주는 타이트 가스 신흥 지역으로 부상하고 있으며, 산토스(Santos)사는 쿠퍼 분지에서 자동화 시추 장비를 도입하여 노동 위험을 줄이고 있습니다. 아르헨티나의 RIGI 세제 안정화 제도 등 규제상의 우대 조치가 외국 기업 시장 진입을 가속화하고 있는 반면, 미국의 연방 임대권 부여는 법적 역풍에 직면해 있습니다.
재생에너지로의 세계적 전환
2024년, 재생에너지 분야에 대한 투자액은 6,230억 달러에 달하여 3년 연속으로 업스트림 부문의 탄화수소 관련 지출을 상회했습니다. IEA의 ‘넷 제로’ 시나리오에 따르면, 석유 수요는 2025년에 정점을 찍고 2035년까지 25% 감소할 것으로 예측되며, 이는 시추 계획에 구조적인 압박을 가할 것으로 보입니다. 토탈에너지스는 현재 설비 투자의 40%를 전력 및 재생에너지에 할당하고 있으며, 북해의 미확인 유전 탐사에서 철수하고 있습니다. 2024년에는 블랙록과 뱅가드가 기후 리스크를 이유로 시추 확대안에 반대표를 던지는 등 투자자들의 활동주의가 더욱 활발해졌습니다. 중동의 국영 석유 회사(NOC)는 여전히 영향받기 어려운 상황이지만, 북미의 독립 석유 회사들은 상업적 규모를 실현하기까지 아직 몇 년이 더 걸릴 지열 발전으로 시추 장비의 용도 전환을 추진하고 있습니다.
부문 분석
보행식 슈퍼 스펙 리그의 등장으로 하이테크 플랫폼의 육상 시추 리그 시장 점유율은 연평균 성장률(CAGR) 0.8% 상승했으나, 2025년 매출의 40.8%는 여전히 이동식 및 바퀴식 유닛이 차지하고 있습니다. 보행식 시스템은 이동 시간을 3일에서 8시간으로 단축하고, 이동 1회당 최대 20만 달러의 비용 절감을 실현하는 동시에 패드 시추의 경제성을 향상시키고 있습니다. 이러한 이점은 패드당 6-12개의 유정을 시추하는 퍼미안 분지의 운영자에게 특히 매력적입니다. 1기당 2,800만 달러를 초과하는 자본 집약도로 인해, 일당 프리미엄으로 자금 조달 비용을 상쇄해야 하는 신흥 지역에서의 보급은 제한적입니다.
한편, 아르헨티나, 콜롬비아 및 아프리카 일부 지역에서는 여전히 기존 방식의 트럭 장착형 시추 장비가 사용되고 있습니다. 이러한 지역에서는 유정이 분산되어 있고, 시추 대상이 얕으며, 안전 기준이 낮은 점 등으로 인해 설비 투자를 최소화하는 것이 선호됩니다. 캘리포니아주의 새로운 Tier 4 엔진 규제로 인해 신규 프로젝트에서 디젤 전용 기계식 시추 장비의 사용이 사실상 금지되면서, 산호아킨 분지에서의 시추 장비 퇴역이 가속화되고 있습니다. 중동에서는 ‘워킹(Walking)’ 개념이 도입되고 있습니다. ADNOC은 2024년에 자후라에 4대를 반입함으로써 북미 이외 지역에서의 국제적 수요가 입증되었습니다. 슈퍼 스펙 사양공급이 부족해지는 가운데, 혼합 플릿을 보유한 계약업체들은 기존 작업에서 가격 결정력을 유지하고 있습니다.
2025년 육상 시추 리그 시장 규모에서 기계식 장비는 51.5%를 차지했으나, 규제 및 연료 절약 압박으로 인해 전기식 SCR 및 AC 구동 장비는 연평균 0.7%의 속도로 확대되고 있습니다. 전기 구동 플랫폼은 시추 1피트당 디젤 연료 사용량을 약 15% 줄여, 현재 연료 가격 기준으로 하루에 2,000-3,000달러를 절약할 수 있습니다. 또한, 트리핑 시 회생 제동도 가능하게 하여 운영 비용을 더욱 절감합니다.
도입 현황은 지역에 따라 다릅니다. 혹독한 겨울과 시추 가능 기간이 짧은 캐나다에서는 도입 속도가 완만합니다. 프레시전 드릴링(Precision Drilling)사가 보유한 181기의 시추 장비 중 전동식 비율은 55%에 불과합니다. 중국에서는 여전히 70%가 기계식 시추 장비이지만, COSL사는 중국석유천연가스집단(페트로차이나)의 메탄 배출 목표를 달성하기 위해 탈림 분지에서 실증 실험을 진행하고 있습니다. SPE의 2024년 조사에 따르면, 가동 부품이 줄어들어 유지보수 비용이 18-22% 절감되므로, 수명 주기 비용 측면에서는 완전 전기화가 유리합니다. 하이브리드형 디젤·전기식 시추 장비는 전력망이나 현장의 가스 공급이 불안정한 지역에서 그 격차를 메우는 역할을 하고 있습니다.
지역별 분석
북미는 2025년 시장 가치의 49.9%를 차지했으며, 2031년까지 연평균 성장률(CAGR)은 0.4%로 완만한 성장이 예상됩니다. 2025년 말 시추 장비 수는 588대로 감소했으나, 측면 시추 구간의 연장 및 사이클 타임 단축으로 인해 생산량은 여전히 3% 증가했습니다. 엑슨모빌이 600억 달러 규모로 파이오니어사를 인수함에 따라, 더 광활하고 연속적인 시추 패드가 확보되어 자본 효율성이 향상되었습니다. 캐나다의 계절적 시추 장비 수는 181대에 달했으나, 봄철 눈이 녹는 시기에는 여전히 매년 최대 2개월 동안 설비가 가동 중단 상태에 놓이기 때문에 가동률 변동은 억제되고 있습니다. 캔자스주와 콜로라도주에서의 천연 수소 시추, 그리고 네바다주에서의 지열정 시추는 새로운 다각화를 가져오고 있지만, 생산량은 석유에 비해 여전히 소규모로 남아 있습니다.
중동 및 아프리카는 정부의 자금 지원과 30달러 미만의 손익분기점에 힘입어 연평균 성장률(CAGR) 0.6%라는 가장 안정적인 전망을 보였습니다. ADNOC Drilling은 시추 장비 수를 118대로 확대하고, 실적 연동형 요금 제도에 기반한 다년 계약을 통해 쿠웨이트와 사우디아라비아에 진출했습니다. 사우디 아람코의 70억 달러 규모의 육상 프로그램은 자프라의 가스 200 TCF 채굴을 목표로 하고 있으며, 10,000 psi 지층에 대응할 수 있는 고토크 시추 장비가 필요합니다. 리비아는 하루 150만 배럴의 생산 회복을 목표로 육상 시추 리그 20대를 도입할 계획이지만, 그 진척 상황은 정치적 안정에 좌우될 것입니다. 알제리의 2026년을 목표로 한 120개 유정 계획은 오랜 기간의 투자 부족을 겪은 후 사하라 사막에서 가스 시추가 재개될 것임을 시사합니다.
아시아태평양은 연평균 성장률(CAGR) 1.3%로 가장 빠르게 성장하고 있는 지역이지만, 그 성장은 작은 기반에서 비롯된 것입니다. 인도는 200°C를 초과하는 온도를 가진 칸베이 분지와 고다바리 분지를 대상으로 한 13개의 지열 블록을 공고했습니다. 호주 쿠퍼 분지의 타이트 가스 프로젝트에서는 인력 부족을 완화하기 위해 자동화 시추 장비가 도입되고 있습니다. 인도네시아의 프론티어 탐사는 허가 취득 지연에 직면한 반면, 중국의 COSL은 메탄 배출 감축 목표의 일환으로 탈림 분지에서 전동 시추 장비의 시범 운영을 진행하고 있습니다. 남미의 연평균 성장률(CAGR) 0.5%는 바카 무에르타에 좌우되고 있습니다. 이 지역의 일일 50만 배럴 생산량은 브라질이 해양 개발에 주력하고 있음에도 불구하고 지역 수요를 끌어올렸습니다. 유럽은 여전히 수압 파쇄 금지 조치로 인해 제약을 받고 있지만, 튀르키예와 루마니아에서는 성숙한 육상 광구에서 소규모이긴 하지만 시추가 계속되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.08.26According to Mordor Intelligence, the land drilling rig market size is estimated at USD 62.03 billion in 2026, and is expected to reach USD 63.38 billion by 2031, at a CAGR of 0.43% during the forecast period (2026-2031).
This report is Segmented by Rig Type (Conventional, Mobile/Wheel-Mounted, and Walking Super-Spec), Drive System (Mechanical, Electric, and Hybrid/Compound), Horsepower Rating (Up To 1, 000 HP, 1, 000 To 1, 499 HP, and Above 1, 500 HP), Application (Conventional Oil, Geothermal, Emerging Natural-Hydrogen, and More), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa).
Global Land Drilling Rig Market Trends and Insights
>=1,500 HP super-spec adoption
Super-spec platforms above 1,500 HP now dominate complex unconventionals, enabling laterals beyond 15,000 feet and trimming total-depth times by up to 30% versus legacy units. FlexRig fleets in the United States logged average day rates of USD 28,500 in 2025, a USD 3,000 premium justified by 7,500-psi pumps and 750-ton top drives. About 60% of U.S. deployments went to the Permian Basin, where deeper Wolfcamp zones require higher torque. ADNOC Drilling mirrored the trend, adding 12 super-spec rigs for the high-pressure Jafurah gas play. High upfront capex, often above USD 25 million per rig, continues to limit ownership to well-capitalized operators.
Shale and other unconventional reserves
Unconventional drilling has switched from appraisal to factory mode, reinforcing baseline demand for the land drilling rigs market. Argentina's Vaca Muerta delivered 500,000 barrels per day by late 2025, up 56% in two years, as YPF and partners drilled deeper liquids-rich sections using 1,200-1,500 HP rigs. The United States still accounted for 40% of global unconventional activity, benefiting from takeaway capacity and pro-drilling infrastructure. Australia is emerging as a tight-gas frontier, where Santos is deploying automated rigs in the Cooper Basin to curb labor exposure. Regulatory incentives such as Argentina's RIGI tax-stability regime are accelerating foreign participation, whereas U.S. federal lease issuance faces legal headwinds.
Global shift to renewables
Renewables attracted USD 623 billion in investment during 2024, overtaking upstream hydrocarbon spend for a third straight year. The IEA's Net-Zero scenario sees oil demand peaking in 2025 and sliding 25% by 2035, implying structural pressure on drilling programs. TotalEnergies now directs 40% of its capex toward power and renewables, retreating from North Sea wildcats. Investor activism deepened in 2024 as BlackRock and Vanguard voted against drilling expansions, citing climate risk. Middle Eastern NOCs remain insulated, but North American independents are repurposing rigs toward geothermal, where commercial scale is still years away.
Other drivers and restraints analyzed in the detailed report include:
- Revival of MENA onshore CAPEX
- Low-emission gas/LNG-powered rig engines
- Oil-price volatility & capital discipline
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Walking super-spec rigs lifted the land drilling rigs market share for high-tech platforms by adding 0.8% CAGR, even though mobile and wheel-mounted units still generated 40.8% of 2025 revenue. Walking systems cut move times from three days to eight hours, saving up to USD 200,000 per relocation and boosting pad-drilling economics. These benefits appeal most to Permian operators completing 6-12 wells per pad. Capital intensity above USD 28 million per unit limits their spread in emerging regions, where dayrate premiums must offset financing costs.
At the other end, conventional truck-mounted fleets persist in Argentina, Colombia, and parts of Africa, where dispersed wells, shallow targets, and lower safety standards favor minimal capex. California's new Tier 4 engine rules effectively ban diesel-only mechanical rigs for new programs, accelerating retirements in the San Joaquin Basin. The Middle East is importing the walking concept; ADNOC moved four units into Jafurah in 2024, validating international demand beyond North America. As super-spec supply tightens, contractors with mixed fleets retain pricing power in conventional work.
Mechanical rigs represented 51.5% of the 2025 land drilling rigs market size, but electric SCR and AC drives are expanding at a 0.7% clip under regulatory and fuel-savings pressure. Electric platforms cut diesel usage by roughly 15% per foot drilled, translating to USD 2,000-3,000 in daily savings at current fuel prices. They also enable regenerative braking during tripping, lowering operating costs further.
Adoption patterns vary by geography. Canada, with challenging winters and shorter drilling windows, is converting slowly; only 55% of Precision Drilling's 181-rig fleet is electric. China still runs 70% mechanical rigs, though COSL has pilots underway in the Tarim Basin to meet PetroChina methane goals. Lifecycle economics favor full electrification because maintenance expenses fall 18-22% thanks to fewer moving parts, according to an SPE 2024 study. Hybrid diesel-electric setups are bridging the gap where grid or field gas is patchy.
Complete Report Scope:
- By Rig Type
- Conventional
- Mobile/Wheel-Mounted
- Walking Super-Spec
- By Drive System
- Mechanical
- Electric (SCR and AC)
- Hybrid/Compound
- By Horsepower Rating
- Up to 1,000 HP
- 1,000 to 1,499 HP
- Above 1,500 HP
- By Application
- Conventional Oil
- Unconventional/Tight and Shale
- Geothermal
- Emerging Natural-Hydrogen
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Turkey
- Romania
- Ukraine
- France
- Spain
- Rest of Europe
- Asia-Pacific
- India
- Australia
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Oman
- Kuwait
- Iraq
- Algeria
- Libya
- Nigeria
- Rest of Middle East and Africa
- North America
Geography Analysis
North America produced 49.9% of the 2025 value and is forecast at a modest 0.4% CAGR to 2031. Rig counts eased to 588 in late 2025, but output still climbed 3% thanks to longer laterals and faster cycle times. ExxonMobil's USD 60 billion Pioneer acquisition unlocked larger contiguous pads, enhancing capital efficiency. Canada's seasonal fleet reached 181 rigs, yet spring breakup still sidelines equipment for up to two months each year, tempering utilization swings. Natural-hydrogen spuds in Kansas and Colorado, plus geothermal wells in Nevada, provide emerging diversification, though volumes remain modest relative to oil.
The Middle East and Africa posted the steadiest outlook with a 0.6% CAGR, aided by state funding and sub-USD 30 breakevens. ADNOC Drilling scaled to 118 rigs, entering Kuwait and Saudi Arabia under multiyear contracts backed by performance tariffs. Saudi Aramco's USD 7 billion onshore program targets 200 TCF of Jafurah gas, requiring high-torque rigs tailored for 10,000-psi formations. Libya plans 20 land rigs to restore 1.5 million barrels per day, although progress depends on political stability. Algeria's 120-well plan for 2026 signals renewed Saharan gas drilling after years of underinvestment.
Asia-Pacific is the fastest-growing region at 1.3% CAGR, yet from a smaller base. India issued 13 geothermal blocks targeting the Cambay and Godavari basins with temperatures above 200 °C. Australia's Cooper Basin tight-gas projects employ automated rigs to mitigate labor scarcity. Indonesia's frontier exploration faces permitting delays, while China's COSL trials electric rigs in the Tarim Basin as part of methane-cutting goals. South America's 0.5% CAGR hinges on Vaca Muerta, whose 500,000 barrels per day output lifted regional demand despite Brazil focusing offshore. Europe remains constrained by fracturing bans, though Turkey and Romania sustain modest drilling in mature onshore licenses.
- Nabors Industries Ltd
- Helmerich & Payne Inc
- Patterson-UTI Energy Inc
- Precision Drilling Corp
- Schlumberger Ltd
- Weatherford International PLC
- Ensign Energy Services Inc
- KCA Deutag
- ADNOC Drilling
- China Oilfield Services Ltd (COSL)
- Sinopec Zhongyuan Petroleum Eng.
- Borr Drilling Ltd
- Saipem SpA
- Kuwait Drilling Company
- Valaris Ltd
- ADES Holding
- Independence Contract Drilling
- Cactus Drilling
- Honghua Group Ltd
- Nabors Saudi Arabia
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing use of >=1,500 HP super-spec rigs
- 4.2.2 Exploiting shale & other unconventional reserves
- 4.2.3 Revival of MENA onshore E&P CAPEX pipelines
- 4.2.4 Adoption of low-emission gas/LNG-powered rig engines
- 4.2.5 Deployment of fully automated, AI-driven "digital rigs"
- 4.2.6 Rise of geothermal & natural-hydrogen well programs
- 4.3 Market Restraints
- 4.3.1 Accelerating global shift to renewables
- 4.3.2 Oil-price volatility & capital-discipline mandates
- 4.3.3 Tightening ESG financing & insurance hurdles
- 4.3.4 Expanding no-drill buffer zones in sensitive basins
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Rig Type
- 5.1.1 Conventional
- 5.1.2 Mobile/Wheel-Mounted
- 5.1.3 Walking Super-Spec
- 5.2 By Drive System
- 5.2.1 Mechanical
- 5.2.2 Electric (SCR and AC)
- 5.2.3 Hybrid/Compound
- 5.3 By Horsepower Rating
- 5.3.1 Up to 1,000 HP
- 5.3.2 1,000 to 1,499 HP
- 5.3.3 Above 1,500 HP
- 5.4 By Application
- 5.4.1 Conventional Oil
- 5.4.2 Unconventional/Tight and Shale
- 5.4.3 Geothermal
- 5.4.4 Emerging Natural-Hydrogen
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Turkey
- 5.5.2.2 Romania
- 5.5.2.3 Ukraine
- 5.5.2.4 France
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 India
- 5.5.3.2 Australia
- 5.5.3.3 ASEAN Countries
- 5.5.3.4 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Colombia
- 5.5.4.4 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Oman
- 5.5.5.4 Kuwait
- 5.5.5.5 Iraq
- 5.5.5.6 Algeria
- 5.5.5.7 Libya
- 5.5.5.8 Nigeria
- 5.5.5.9 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Nabors Industries Ltd
- 6.4.2 Helmerich & Payne Inc
- 6.4.3 Patterson-UTI Energy Inc
- 6.4.4 Precision Drilling Corp
- 6.4.5 Schlumberger Ltd
- 6.4.6 Weatherford International PLC
- 6.4.7 Ensign Energy Services Inc
- 6.4.8 KCA Deutag
- 6.4.9 ADNOC Drilling
- 6.4.10 China Oilfield Services Ltd (COSL)
- 6.4.11 Sinopec Zhongyuan Petroleum Eng.
- 6.4.12 Borr Drilling Ltd
- 6.4.13 Saipem SpA
- 6.4.14 Kuwait Drilling Company
- 6.4.15 Valaris Ltd
- 6.4.16 ADES Holding
- 6.4.17 Independence Contract Drilling
- 6.4.18 Cactus Drilling
- 6.4.19 Honghua Group Ltd
- 6.4.20 Nabors Saudi Arabia
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


