

|
시장보고서
상품코드
2114514
소 사료 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Cattle Feed - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
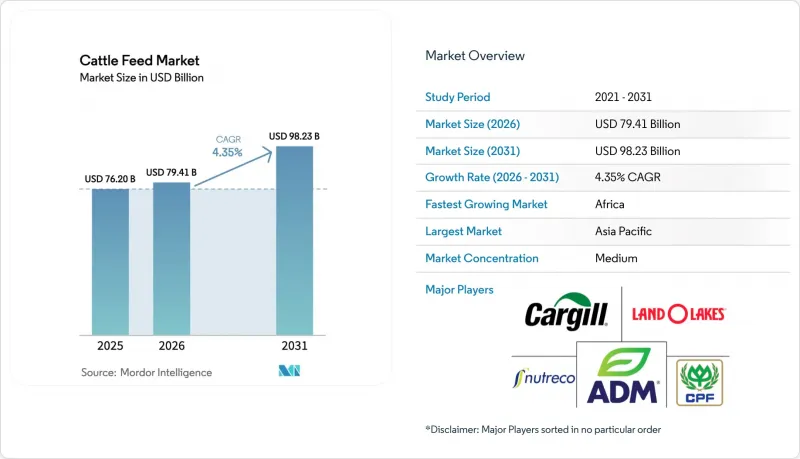
에 의하면, 2025년에 762억 달러로 추정된 소 사료 시장 규모는 2026년에는 794억 1,000만 달러로 확대되어 2031년까지 982억 3,000만 달러까지 한층 더 증가한다고 전망되고 있어 예측 기간(2026-2031년)에서 CAGR 4.35%로 성장할 전망입니다.
본 보고서는 가축 유형(젖소 및 육우), 원료(곡물, 케이크 및 혼합물, 식품 폐기물, 사료 첨가제, 기타 원료), 형태(펠렛, 매시, 크럼블, 액체),및 지역(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 및 수량(미터톤)으로 표시되어 있습니다.
전 세계 소 사료 시장 동향 및 인사이트
사료 강화 프로그램에 대한 정부의 인센티브
케냐, 에티오피아, 인도 정부는 소 사료에 미량 미네랄 및 비타민을 최소한으로 함유하도록 의무화하는 규제를 도입했습니다. 이러한 정책으로 인해 농가의 실질적인 비용이 절감되었으며, 기존의 농장 내 자가 배합 방식에서 벗어나는 전환이 가속화되고 있습니다. 2024년 케냐에서 시행된 보조금 프로그램에서는 강화 사료 비용의 30%가 지원되었으며, 이로 인해 불과 9개월 만에 배합 사료 수요가 12만 메트릭 톤 증가했습니다. 인도는 영양 강화 인프라 구축에 50억 루피(6,020만 달러)를 배정했으며, 펀자브 주와 하리야나 주에서는 조기 도입이 진행되고 있습니다. 유엔 식량농업기구(FAO)의 추정에 따르면, 사하라 이남 아프리카의 배합 사료 보급률은 2028년까지 34%에 달할 가능성이 있어, 프리믹스 공급업체들에게 큰 비즈니스 기회가 창출되고 있습니다.
고단백 유제품 및 육류 제품에 대한 수요 증가
중국과 사우디아라비아 등 국가들의 소득 증가가 우유와 쇠고기 소비 확대를 이끌고 있습니다. 이러한 추세에 따라 생산 목표를 달성하기 위해 농장에서는 단백질 함량이 높은 사료 배합을 도입하는 움직임이 확산되고 있습니다. 2024년, 중국의 1인당 우유 섭취량은 42kg에 달했으며, 조단백질 함량이 18%를 초과하는 사료의 채택이 확산되었습니다. 사우디아라비아는 식육 자급자족 달성이라는 목표를 뒷받침하기 위해 120만 미터톤의 배합 사료를 수입했습니다. 이러한 수요는 루멘 보호형 지방을 함유한 액상 보충제의 성장도 촉진하고 있으며, 이 부문 시장 규모는 현재 21억 달러에 달할 전망입니다.
곡물 가격 변동이 투입 비용에 영향
곡물 가격 변동은 사료 제조업체들에게 계속해서 과제로 남아 있습니다. 옥수수와 대두박은 사료 비용의 최대 75%를 차지하고 있어, 사료 공장은 시장 변동의 영향을 크게 받고 있습니다. 2024년, 시카고 옥수수 가격은 부셸당 4.20달러에서 5.80달러 사이에서 변동했으며, 일부 분기에는 이익률이 3% 미만으로 떨어질 정도로 압박을 받았습니다. 아르헨티나의 가뭄으로 인해 대두 수출량이 22% 감소했고, 구매자들은 브라질산 수입품에 대해 1미터톤당 40달러의 프리미엄을 지불해야만 했습니다. 헤지 수단이 없는 소규모 사료 공장은 이러한 시기에 심각한 자금 사정 압박에 직면하고 있습니다.
부문별 분석
젖소는 계속해서 소 사료 시장 규모를 주도하고 있으며, 2025년에는 53.2%라는 최대 점유율을 차지하고 있습니다. 고단백 사료는 여전히 필수적이지만, 식물성 대체재의 부상으로 인해 가공업체의 이익률에 압박이 가해지고 있습니다. 대규모 축산 경영에서는 생산량을 유지하기 위해 바이패스 단백질이나 보호 지방을 배합하고 있는 반면, ‘팜 투 포크(Farm to Fork)’ 이니셔티브에 기반한 규제적 인센티브로 인해 저배출 사료 기술의 도입이 촉진되고 있습니다. 이러한 진전에도 불구하고, 비용 및 기호성 문제는 여전히 이러한 기술의 광범위한 활용을 제한하고 있습니다. 또한, 가공업체에 의한 수직 통합은 공급망의 재편을 초래하고 있어, 독립 사료 제조업체와의 거래량은 감소하는 반면 사료 배합에 대한 지배력은 강화되고 있습니다.
육우 시장은 젖소 시장보다 빠르게 확대될 전망이며, 2031년까지 연평균 성장률(CAGR) 5.2%를 나타낼 것으로 예측됩니다. 이는 토지 가격이 크게 상승하고 있는 브라질이나 아르헨티나 등 지역에서 새로운 목초지 확장에 비해 비육장이 비용 면에서 더 경쟁력이 높다는 점을 반영한 것입니다. 수출업체들은 유럽연합(EU)의 프리미엄 할당량을 충족하기 위해 마블링 기준 준수에 점점 더 주력하고 있으며, 이로 인해 육우 비육 전망은 더욱 밝아지고 있습니다. 메탄 감축용 첨가제는 현재로서는 보급률이 아직 제한적이지만, 탄소 시장이 성숙하고 인센티브가 지속가능성 목표와 부합한다면 주류가 될 가능성이 있습니다.
지역별 분석
아시아태평양은 중국의 산업화된 낙농장과 인도의 방대한 소 사육 두수에 힘입어 2025년에는 36.6%라는 최대 점유율을 차지했습니다. 1,000두 이상을 사육하는 중국의 대규모 농장이 현재 해당국의 우유 생산 대부분을 담당하고 있으며, 배합 사료의 도입이 가속화되고 있습니다. 인도의 협동조합은 보급 지도 서비스 및 영양 강화 사료에 대한 투자를 추진하고 있어, 생산성 측면에서 큰 개선 여지가 있음을 시사합니다. 또한 소득 증가와 고단백질 섭취로 변화하는 식생활도 지역 수요를 뒷받침하고 있어, 향후 몇 년간 아시아태평양이 세계 소 사료 수요의 주축으로 남을 것으로 확실시되고 있습니다.
아프리카는 가장 빠른 속도로 성장할 것으로 예측되며, 2031년까지 연평균 성장률(CAGR) 5.5%로 성장할 전망입니다. 보조금 지원 대출 프로그램과 영양 강화 사료 의무화로 인해 낙농 협동조합 전반에서 혼합 사료 도입이 진행되고 있습니다. 유엔 식량농업기구(FAO)의 추정에 따르면, 2028년까지 혼합 사료 보급률이 크게 상승할 가능성이 있어, 프리믹스 공급업체에게 큰 비즈니스 기회가 생길 것으로 전망됩니다. 나이지리아에서는 소 사육두수 증가와 기부자 지원에 의한 사료 공장 건설로 공급망 재구성이 진행되고 있는 반면, 남아프리카공화국의 선진적인 비육 목장에서는 인프라 측면의 과제에 직면해 있습니다. 아프리카의 성장 궤적은 구조적인 수요와 정책 주도의 축산 시스템 현대화, 이 두 가지를 모두 반영하고 있습니다.
북미에서는 가뭄으로 인한 젖소 도태로 인해 사육 두수가 감소하고 있는 반면, 유럽에서는 플렉시타리언 식단이나 사육 두수 상한 규제 같은 과제에 직면해 있습니다. 남미에서는 브라질의 비육장 부문 확대와 세제상의 압박으로 인해 성장세가 둔화되고 있는 아르헨티나의 상황 사이에서 양극화가 나타나고 있습니다. 중동은 여전히 수입 의존도가 높으며, 각국은 물 부족으로 제약을 받고 있습니다. 이러한 지역 중에는 규모 확대가 가속화되고 있는 곳도 있는 반면, 구조적인 역풍에 직면한 지역도 있어 그 동향은 제각각입니다. 이를 종합해 보면, 전 세계적으로 소 사료 도입 속도에 편차가 있다는 점이 부각되고 있으며, 아시아태평양과 아프리카가 명확한 성장의 견인차로 부상하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.03According to Mordor Intelligence, the cattle feed market size, estimated at USD 76.20 billion in 2025, is set to increase to USD 79.41 billion in 2026 and further climb to USD 98.23 billion by 2031, growing at a CAGR of 4.35% during the forecast period (2026-2031).
This report is Segmented by Animal Type (Dairy Cattle and Beef Cattle), by Ingredient (Cereals, Cakes and Mixes, Food Wastages, Feed Additives, and Other Ingredients), by Form (Pellets, Mash, Crumble, and Liquid), and by Geography (North America, South America, Europe, Asia Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value in USD and Volume in Metric Tons.
Global Cattle Feed Market Trends and Insights
Government Incentives for Feed Fortification Programs
Governments in Kenya, Ethiopia, and India have introduced mandates requiring minimum inclusion of trace minerals and vitamins in cattle feed. These policies reduce effective costs for farmers and accelerate the transition away from traditional on-farm mixes. Kenya's subsidy program in 2024 covered 30% of the costs of fortified rations, which boosted compound feed demand by 120,000 metric tons in just nine months. India allocated INR 5 billion (USD 60.2 million) to build fortification infrastructure, with early adoption seen in Punjab and Haryana. The Food and Agriculture Organization's estimates suggest that compound feed penetration in Sub-Saharan Africa could reach 34% by 2028, creating strong opportunities for premix suppliers.
Escalating Demand for High Protein Dairy and Meat Products
Rising incomes in countries such as China and Saudi Arabia are driving higher consumption of milk and beef. This trend is pushing farms to adopt rations with elevated protein levels to meet production targets. In 2024, China's per-capita milk intake reached 42 kilograms, resulting in widespread adoption of diets with crude protein levels exceeding 18%. Saudi Arabia imported 1.2 million metric tons of compound feed to support its goal of achieving meat self-sufficiency. The demand has also fueled growth in liquid supplements containing rumen-protected fats, a segment now valued at USD 2.1 billion.
Volatile Grain Prices Impacting Input Costs
Grain price volatility continues to pose a challenge for feed manufacturers. Corn and soybean meal account for up to 75% of ration costs, leaving mills highly exposed to market swings. In 2024, Chicago corn prices fluctuated between USD 4.20 and USD 5.80 per bushel, compressing margins to below 3% in some quarters. Argentina's drought reduced soybean exports by 22%, forcing buyers to pay premiums of USD 40 per metric ton from Brazil. Smaller mills without hedging tools face severe liquidity pressures during such periods.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Intensification of Cattle Farming in Emerging Economies
- Commercialization of Precision Feeding Technologies
- Shift Toward Plant-Based Diets in Mature Economies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dairy cattle continue to dominate the cattle feed market size, holding the largest share in 2025 at 53.2%. High-protein rations remain essential, but the rise of plant-based alternatives is putting pressure on processor margins. Large herds integrate bypass proteins and protected fats to sustain yields, while regulatory incentives under the Farm to Fork initiative encourage the adoption of low-emission feed technologies. Despite these advances, cost and palatability challenges still limit the widespread use of these technologies. Vertical integration by processors is also reshaping supply chains, diverting volumes from independent mills and consolidating control over feed formulations.
Beef cattle are positioned to expand more rapidly than dairy, advancing at a 5.2% CAGR through 2031. This reflects the cost competitiveness of feedlots compared to new pasture expansion in regions such as Brazil and Argentina, where land prices have increased significantly. Exporters are increasingly focused on marbling compliance to meet premium European Union quotas, further strengthening the outlook for beef finishing. Methane-reducing additives, though still at limited penetration, could become mainstream if carbon markets mature and incentives align with sustainability goals.
Complete Report Scope:
- By Animal Type
- Dairy Cattle
- Beef Cattle
- By Ingredient
- Cereals
- Cakes and Mixes
- Food Wastages
- Feed Additives
- Other Ingredients
- By Form
- Pellets
- Mash
- Crumble
- Liquid
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia Pacific captured the largest 2025 share at 36.6%, driven by China's industrialized dairies and India's sizable herd. Large-scale Chinese farms housing over 1,000 head now produce the majority of the nation's milk, accelerating the adoption of compound feed. India's cooperatives are investing in extension services and fortified rations, signaling significant upside potential in productivity. Regional demand is also supported by rising incomes and dietary shifts toward higher protein consumption, ensuring that the Asia Pacific region remains the anchor of global cattle feed demand in the years ahead.
Africa is forecast to grow at the fastest pace, advancing at a 5.5% CAGR through 2031. Subsidized credit programs and fortified ration mandates are driving the adoption of compound feed across dairy cooperatives. Food and Agriculture Organization estimates indicate that compound feed penetration could increase substantially by 2028, creating significant opportunities for premix suppliers. Nigeria's herd expansion and donor-backed feed mills are reshaping supply chains, while South Africa's advanced feedlots face infrastructure challenges. Africa's growth trajectory reflects both structural demand and policy-driven modernization of livestock systems.
North America has faced herd contractions due to drought-driven cow liquidations, while Europe contends with flexitarian diets and herd caps. South America is split between Brazil's expanding feedlot sector and Argentina's slowdown under tax pressures. The Middle East remains heavily reliant on imports, with countries constrained by water scarcity. These regions exhibit mixed dynamics, with some experiencing intensification of scaling, while others face structural headwinds. Together, they highlight the uneven pace of cattle feed adoption globally, with Asia-Pacific and Africa emerging as the clear growth leaders.
- Archer Daniels Midland Company
- Cargill Incorporated
- Land O'Lakes Incorporated
- Charoen Pokphand Foods Group
- DSM-Firmenich AG
- Nutreco N.V. (SHV Holdings N.V.)
- De Heus Animal Nutrition B.V.
- ForFarmers N.V.
- DBN Group
- Kemin Industries, Inc.
- New Hope Group
- Wen's Food Group
- Godrej Agrovet Limited (Godrej Group)
- Kent Nutrition Group (Kent Corporation)
- Alltech, Inc.
- Ridley Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government incentives for feed fortification programs
- 4.2.2 Escalating demand for high-protein dairy and meat products
- 4.2.3 Rapid intensification of cattle farming in emerging economies
- 4.2.4 Commercialization of precision feeding technologies
- 4.2.5 Digital marketplaces simplifying feed procurement
- 4.2.6 Climate-resilient forage development boosting compound feed use
- 4.3 Market Restraints
- 4.3.1 Volatile grain prices impacting input costs
- 4.3.2 Shift toward plant-based diets in mature economies
- 4.3.3 Stringent anti-microbial regulations raising reformulation costs
- 4.3.4 Supply-chain disruptions from extreme weather events
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers/Consumers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Animal Type
- 5.1.1 Dairy Cattle
- 5.1.2 Beef Cattle
- 5.2 By Ingredient
- 5.2.1 Cereals
- 5.2.2 Cakes and Mixes
- 5.2.3 Food Wastages
- 5.2.4 Feed Additives
- 5.2.5 Other Ingredients
- 5.3 By Form
- 5.3.1 Pellets
- 5.3.2 Mash
- 5.3.3 Crumble
- 5.3.4 Liquid
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.1.4 Rest of North America
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Spain
- 5.4.3.5 Italy
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 Australia
- 5.4.4.5 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 Turkey
- 5.4.5.3 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Nigeria
- 5.4.6.3 Rest of Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Archer Daniels Midland Company
- 6.4.2 Cargill Incorporated
- 6.4.3 Land O'Lakes Incorporated
- 6.4.4 Charoen Pokphand Foods Group
- 6.4.5 DSM-Firmenich AG
- 6.4.6 Nutreco N.V. (SHV Holdings N.V.)
- 6.4.7 De Heus Animal Nutrition B.V.
- 6.4.8 ForFarmers N.V.
- 6.4.9 DBN Group
- 6.4.10 Kemin Industries, Inc.
- 6.4.11 New Hope Group
- 6.4.12 Wen's Food Group
- 6.4.13 Godrej Agrovet Limited (Godrej Group)
- 6.4.14 Kent Nutrition Group (Kent Corporation)
- 6.4.15 Alltech, Inc.
- 6.4.16 Ridley Corporation


