

|
시장보고서
상품코드
2114740
복강경하 회수 백 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Laparoscopic Retrieval Bags - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
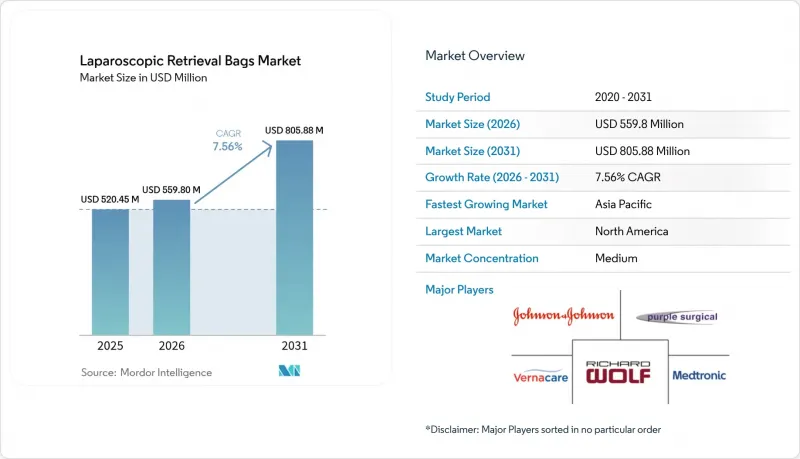
에 의하면, 2026년 복강경하 회수 백 시장 규모는 5억 5,980만 달러로 추정되고 2025년 5억 2,045만 달러에서 확대해, 2031년에는 8억 588만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 7.56%를 나타낼 것으로 전망됩니다.
본 보고서는 유형별(탈착식 회수 백, 비탈착식 회수 백), 방식별(수동 개구, 자동 개구), 용도별(소화기 외과 수술, 산부인과 수술, 비뇨기과 수술, 기타), 최종 사용자별(병원, 기타),지역별(북미, 유럽, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 복강경하 회수 백 시장 동향 및 인사이트
최소 침습 수술에 대한 수요 증가
현재 주요 의료 시스템에서 특정 수술 부문의 80% 이상이 최소 침습 수술 기술로 수행되고 있으며, 이로 인해 입원 기간이 최대 3일 단축되고 합병증 위험도 감소하고 있습니다. 2025년 FDA 승인을 받은 EVIS X1 내시경 시스템과 같은 새로운 영상 플랫폼은 화질 기준을 높여 복강경 수술에 대한 외과의사의 신뢰를 강화하고 있습니다. 교육 커리큘럼은 고도 복강경 수술 기술에 중점을 두게 되었으며, 이러한 수술법을 선호하는 경향이 있는 의료진이 양성되고 있습니다. 저침습 수술의 각 사례에서는 일반적으로 무균 회수 백이 필요하기 때문에 유닛 소비량이 직접적으로 증가합니다. 가치 기반 지불 환경에서는 회복 기간 단축과 감염 감소가 복강경 수술로의 추가적인 전환을 촉진하고 있으며, 이는 복강경하 회수 백 시장 전체 수요를 가속화하고 있습니다.
대상 복부·골반 질환의 부담 증가
선진국에서는 대장암 수술 건수가 전년 대비 15% 증가했으며, 담낭, 충수, 산부인과 수술 건수도 누적 수술 건수에 포함되고 있습니다. 일본만 보더라도 의료기기 시장은 2021년에 400억 달러에 달했으며, 2027년까지 연평균 성장률(CAGR) 5.5%로 성장을 지속하고, 있어 수술 건수의 대폭적인 증가를 시사하고 있습니다. 비만 및 당뇨병 유병률의 상승은 복강경 수술 중 검체 채취가 필요한 대사성 질환 및 비뇨기과 수술 증가에 기여하고 있습니다. 아시아태평양에서는 가장 급격한 역학적 변화가 관찰되고 있으며, 병원들은 멸균 병목 현상을 피하기 위해 수술실 수용 능력을 확대하고 일회용 회수용 소모품을 대량으로 비축할 수밖에 없는 상황에 처해 있습니다.
프리미엄 회수 백의 높은 평균 판매 가격
자동 전개 기능을 갖춘 제품은 수동식 백에 비해 40-60%의 가격 프리미엄이 책정되어 있어, 비용 절감 방안을 추진하는 조달 팀의 반발을 불러일으키고 있습니다. 가치 기반 계약에서는 공급업체가 추가 지출을 상쇄할 수 있는 치료 성과 증거를 제시할 의무가 있어, 이것이 임의적인 업그레이드를 억제하는 요인이 되고 있습니다. 아시아 제조업체들의 경쟁적인 가격 책정으로 인해 이익률은 압박을 받고 있는 반면, 병원의 처방집에서는 수량 할인을 활용하기 위해 저비용의 제한된 SKU로 표준화가 진행되고 있습니다. 이러한 환경 하에서는 임상적 이점이 비용 측면의 우려를 상회한다는 것이 입증될 때까지, 복강경하 회수 백 시장의 프리미엄 부문 성장은 둔화될 가능성이 있습니다.
부문별 분석
2025년, 탈부착식 디자인은 복강경하 회수 백 시장의 57.32% 점유율을 차지했습니다. 이는 외과의들이 검체 취급의 유연성과 로봇 보조 팔과의 호환성을 중요하게 여긴다는 점을 반영합니다. 이 부문은 2031년까지 연평균 성장률(CAGR) 8.01%를 나타낼 것으로 예측되며, 복강경하 회수 백 시장 전체를 상회하는 성장이 예상됩니다. 혁신은 적출 시 발생하는 토크를 견디면서도, 백이 제대 포트에 도달했을 때 신속하게 분리될 수 있는 확실한 고정 인터페이스에 집중되고 있습니다. 견고한 래치 구조와 X선 불투과성 마커에 투자하고 있는 기업들은 투시 검사를 통해 완전한 적출을 확인할 수 있게 하고 있으며, 이 기능은 비만 수술 및 종양 수술 분야에서 높이 평가받고 있습니다. 비탈착식 백은 모듈성보다 기구 수를 단순화하는 것이 중시되는 일반적인 담낭 절제술 등의 안정적인 틈새 시장을 차지하고 있습니다.
로봇 팔의 소형화가 진행됨에 따라, 검체 용량을 손상시키지 않으면서 5mm 트로카를 통과할 수 있는 슬림한 탈부착식 백에 대한 수요가 높아지고 있습니다. 올림푸스의 플렉서블 이너 샤프트 기술은 탈부착 가능한 하위 구성 요소에 능동적인 절개 및 소작 기능을 통합함으로써, 백의 무결성을 유지하면서 수술 효율을 향상시키는 좋은 예입니다. 병원에서 로봇 수술실이 표준화됨에 따라, 탈부착식 백이 복강경하 회수 백 시장 규모에서 차지하는 비중은 더욱 확대될 것으로 예측됩니다.
수동식 백은 익숙한 조작성과 경제적인 가격 덕분에 2025년 복강경하 회수 백 시장 규모의 61.88%를 차지했으나, 자동식은 연평균 성장률(CAGR) 8.07%로 가장 급격한 성장을 기록하고 있습니다. 수동식 장치는 단순한 구조와 고장 위험이 낮다는 장점이 있어, 담낭 절제술이나 충수 절제술을 많이 시행하는 프로그램에서는 표준적인 선택지로 자리 잡고 있습니다. 또한, 연수 커리큘럼에서도 기존 방식의 당김줄식 개구부에 익숙해지는 것을 중시하고 있어, 이것이 시장 점유율 유지로 이어지고 있습니다.
자동식 백은 특히 외과의사가 무균 영역에서 떨어진 콘솔에서 수술을 수행하는 로봇 보조 수술실에서 워크플로우의 변동성에 대한 우려를 해소해 줍니다. 스프링식 또는 SMA(형상 기억 합금) 구동 림 덕분에 부자연스러운 각도에서도 개구부가 확실하게 열리므로, 보조 집게를 이용한 조작의 필요성이 줄어듭니다. 높은 비용이 예산에 민감한 환경에서의 도입을 저해하고는 있지만, 표준화된 로봇 수술 프로토콜을 도입하고 있는 대학 병원에서는 일관성을 확보하기 위해 자동 개방형 백의 사용을 의무화하는 움직임이 강해지고 있습니다. 보스턴 사이언티픽의 신규 씰 어셈블리 관련 특허 활동은 자동 개구형 카테고리에서 신뢰성이 경쟁 측면에서 얼마나 중요한지를 보여줍니다. 저가형 자동 개구형 SKU의 입수 가능성이 확대됨에 따라, 예측 기간 동안 이 부문에 대한 수요 증가가 예상됩니다.
지역별 분석
북미는 2025년에 전 세계 매출의 40.76%를 차지했으며, 이는 로봇 보조 수술의 높은 보급률과 고가의 소모품 비용을 상쇄하는 유리한 보험 환급 제도에 힘입은 것입니다. FDA의 일회용 기기 승인 절차에 대한 명확화로 시장 출시 기간이 단축되고 있으며, 또한 검체의 무결성을 확보하기 위해 기관 심사 위원회가 멸균 상태에서의 회수를 요구하는 경우가 많아 예측 가능한 구매량이 뒷받침되고 있습니다. 광범위한 기기 포트폴리오 전반에 걸친 교차 판매를 통해, 입지를 다진 공급업체들은 그룹 구매 조직과의 계약에서 안정적인 협상력을 확보하고 있습니다.
아시아태평양은 중국, 인도, 일본의 외과 인프라에 대한 적극적인 설비 투자를 통해 2031년까지 연평균 성장률(CAGR) 8.19%로 성장을 주도할 것입니다. 일본 의료기기 시장의 2027년 연평균 성장률(CAGR) 5.5%는 고령화가 진행되고 있는 국민들 사이에서 소화기 및 비뇨기 계통 시술에 대한 인구통계학적 필연성을 반영하고 있습니다. 2025년까지 2,100억 달러 규모의 의료기기 시장으로 계속 성장할 중국에서는 현지 생산을 하는 국제 브랜드에게 시장 점유율 확보의 기회가 지속적으로 확대되고 있습니다. 인도에서는 의료기기의 윤리적 마케팅 규범이 개정되고 투명성이 증진됨에 따라 수입 승인 절차가 원활해져 고품질의 회수용 소모품 채택이 촉진되고 있습니다. 2급 도시에 위치한 민관 협력 병원은 미개척 수요원으로 부상하며, 복강경 회수백 시장의 추가적인 확대로 이어지고 있습니다.
유럽에서는 품질과 안전성을 중시하는 엄격한 MDR(의료기기 규정) 준수를 원동력으로 완만한 성장이 나타나고 있습니다. 지속가능성 목표가 생분해성 폴리머의 임상시험을 뒷받침하고 있어, 혁신 기업들에게 차별화의 길이 열리고 있습니다. 회원국마다 다른 환급 제도로 인해 공급업체들은 명확한 의료 경제 데이터를 제시해야 하는 압박을 받고 있지만, 저침습 암 수술에 관한 일관된 임상 지침 덕분에 기본적인 수요는 유지되고 있습니다. 중동 및 아프리카 및 남미에서는 신흥 민간 병원 체인과 정부의 현대화 계획이 맞물려 장기적인 성장이 예상되지만, 환율 변동과 복잡한 조달 절차로 인해 단기적인 출하가 제한될 가능성이 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, the laparoscopic retrieval bags market size in 2026 is estimated at USD 559.8 million, growing from 2025 value of USD 520.45 million with 2031 projections showing USD 805.88 million, growing at 7.56% CAGR over 2026-2031.
This report is Segmented by Type (Detachable Retrieval Bags, Non-Detachable Retrieval Bags), Technique (Manual Opening, Automatic Opening), Application (Gastrointestinal Surgeries, Gynecological Surgeries, Urological Surgeries, Other Applications), End User (Hospitals, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Laparoscopic Retrieval Bags Market Trends and Insights
Rising Demand for Minimally-Invasive Surgery
Minimally invasive techniques now represent more than 80% of select surgical categories in leading health systems, shortening length of stay by up to 3 days and lowering complication risk. New imaging platforms such as the EVIS X1 endoscopy system cleared by the FDA in 2025 have raised image quality standards, reinforcing surgeon confidence in laparoscopy . Training curricula increasingly centre on advanced laparoscopic skills, creating a workforce predisposed to prefer these methods. Each minimally invasive case typically necessitates a sterile extraction bag, which directly lifts unit consumption. In value-based payment environments, faster recovery and fewer infections underpin further procedure migration to laparoscopy, accelerating demand across the laparoscopic retrieval bags market.
Growing Burden of Target Abdominal & Pelvic Diseases
Colorectal cancer interventions have climbed by 15% year on year in developed economies, while gallbladder, appendiceal, and gynaecological cases add to the cumulative surgical volume. In Japan alone, the medical device sector reached USD 40 billion in 2021 and is tracking a 5.5% CAGR to 2027, signalling substantial procedure throughput growth . Rising obesity and diabetes rates contribute to metabolic and urological surgeries that also rely on specimen retrieval during laparoscopy. Asia-Pacific records the steepest epidemiological transition, compelling hospitals to expand theatre capacity and stock greater quantities of single-use retrieval consumables to avoid sterilisation bottlenecks.
High Average Selling Price of Premium Retrieval Bags
Automatic deployment features command 40-60% price premiums compared with manual bags, sparking push-back from procurement teams running cost-containment initiatives. Value-based contracts obligate vendors to furnish outcome evidence that offsets incremental spend, damping discretionary upgrades. Competitive pricing from Asian manufacturers tightens margins, while hospital formularies standardise on a narrow band of lower-cost SKUs to exploit volume discounts. This environment may temper the premium segment within the laparoscopic retrieval bags market until proven clinical advantages outweigh cost concerns.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Ambulatory Surgery Centres Worldwide
- Technological Advances in Self-Opening Bag Mechanisms
- Environmental Scrutiny Over Single-Use Plastics in ORs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Detachable designs captured 57.32% of laparoscopic retrieval bags market share in 2025, reflecting surgeon preference for specimen handling flexibility and compatibility with robot-assisted arms. This segment is forecast to post an 8.01% CAGR through 2031, outpacing the broader laparoscopic retrieval bags market. Innovation concentrates on secure fastening interfaces that withstand torque during extraction while enabling rapid separation once the bag reaches the umbilical port. Firms investing in robust latch geometries and radio-opaque markers facilitate fluoroscopic confirmation of complete removal, a feature valued in bariatric and oncological surgeries. Non-detachable bags occupy steady niches such as routine cholecystectomy where streamlined instrument counts matter more than modularity.
Continued miniaturisation of robotic wrists magnifies demand for slimline detachable bags that traverse 5 mm trocars without compromising specimen volume. Olympus's flexible inner shaft technology exemplifies how detachable sub-components can incorporate active cutting or cautery, enhancing procedural efficiency while keeping bag integrity intact. As hospitals standardise on robotic theatres, the detachable cohort is expected to widen its contribution to the laparoscopic retrieval bags market size.
Manual bags retained 61.88% of the laparoscopic retrieval bags market size in 2025 because of their familiar deployment and economical pricing, yet automatic formats post the sharpest growth at 8.07% CAGR. Manual devices benefit from simple mechanics and lower failure risk, making them the default in high-volume gallbladder or appendectomy programmes. Training curricula also reinforce comfort with traditional pull-string openings, sustaining share.
Automatic bags answer workflow variability concerns, particularly in robot-assisted suites where the surgeon operates from a console distant from the sterile field. Spring-triggered or SMA-driven rims guarantee mouth opening even at awkward angles, reducing need for ancillary grasper manipulation. Although higher cost deters deployment in budget-sensitive settings, university hospitals piloting standardised robotic pathways increasingly stipulate automatic bags for consistency. Patent activity from Boston Scientific on novel seal assemblies illustrates the competitive importance of reliability in auto-open categories. Broader availability of low-priced auto-open SKUs is expected to tilt incremental demand toward the segment over the forecast horizon.
Complete Report Scope:
- By Type
- Detachable Retrieval Bags
- Non-detachable Retrieval Bags
- By Technique
- Manual Opening
- Automatic Opening
- By Application
- Gastrointestinal Surgeries
- Gynecological Surgeries
- Urological Surgeries
- Other Applications
- By End User
- Hospitals
- Ambulatory Surgical Centres
- Specialty Clinics
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America posted 40.76% of global revenue in 2025, underpinned by high adoption of robotic-assisted surgery and favourable reimbursement that offsets premium consumable costs. FDA clarity on single-use device pathways accelerates time to market, and institutional review boards often require sterile retrieval for specimen integrity, supporting predictable purchasing volumes. Cross-selling across extensive device portfolios grants established vendors stable contracting leverage with group purchasing organisations.
Asia-Pacific leads growth at an 8.19% CAGR to 2031 thanks to aggressive capital expenditure on surgical infrastructure in China, India and Japan. The Japanese medical device market's 5.5% CAGR through 2027 reflects a demographic imperative for gastrointestinal and urological procedures among ageing citizens. China's climb toward a USD 210 billion device market by 2025 continues to open quota opportunities for international brands that localise production. India's updated medical device ethical marketing code encourages transparency, smoothing import approvals and catalysing adoption of high-quality retrieval consumables. Public-private partnership hospitals in tier-2 cities present untapped volume pockets, further enlarging the laparoscopic retrieval bags market.
Europe shows moderate expansion driven by stringent MDR compliance that rewards quality and safety. Sustainability goals spur trials of biodegradable polymers, creating a differentiating avenue for innovators. Fragmented reimbursement across member states pressures vendors to present clear health-economic data, but consistent clinical guidelines on minimally invasive cancer surgery preserve baseline demand. Middle East, Africa and South America combine emerging private hospital chains and government modernisation schemes to supply long-run upside, though currency volatility and procurement bureaucracy can temper near-term shipments.
- Johnson & Johnson
- Medtronic
- Applied Medical Resources
- B. Braun
- Genicon
- Richard Wolf
- Olympus
- Karl Storz SE
- Purple Surgical
- Conmed
- Teleflex
- Lagis Enterprise
- Grena
- Changzhou Wick Medical
- Unimicro Medical Systems
- Zhejiang Geyi Medical
- Vernacare
- The Cooper Companies
- LaproSurge
- Bariatric Solutions
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for minimally-invasive surgery
- 4.2.2 Growing burden of target abdominal & pelvic diseases
- 4.2.3 Expansion of ambulatory surgery centres worldwide
- 4.2.4 Technological advances in self-opening bag mechanisms
- 4.2.5 Surge in regulations favouring single-use sterile devices
- 4.2.6 Development of biodegradable polymer retrieval bags
- 4.3 Market Restraints
- 4.3.1 High average selling price of premium retrieval bags
- 4.3.2 Availability of alternative specimen-removal techniques
- 4.3.3 Environmental scrutiny over single-use plastics in ORs
- 4.3.4 Limited compatibility with next-gen robotic trocars
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Type
- 5.1.1 Detachable Retrieval Bags
- 5.1.2 Non-detachable Retrieval Bags
- 5.2 By Technique
- 5.2.1 Manual Opening
- 5.2.2 Automatic Opening
- 5.3 By Application
- 5.3.1 Gastrointestinal Surgeries
- 5.3.2 Gynecological Surgeries
- 5.3.3 Urological Surgeries
- 5.3.4 Other Applications
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Ambulatory Surgical Centres
- 5.4.3 Specialty Clinics
- 5.4.4 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Johnson & Johnson (Ethicon)
- 6.3.2 Medtronic plc
- 6.3.3 Applied Medical Resources
- 6.3.4 B. Braun SE
- 6.3.5 GENICON
- 6.3.6 Richard Wolf GmbH
- 6.3.7 Olympus Corporation
- 6.3.8 Karl Storz SE
- 6.3.9 Purple Surgical
- 6.3.10 Conmed Corporation
- 6.3.11 Teleflex Incorporated
- 6.3.12 Lagis Enterprise
- 6.3.13 Grena Ltd.
- 6.3.14 Changzhou Wick Medical
- 6.3.15 Unimicro Medical Systems
- 6.3.16 Zhejiang Geyi Medical
- 6.3.17 Vernacare
- 6.3.18 CooperSurgical
- 6.3.19 LaproSurge
- 6.3.20 Bariatric Solutions
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


