

|
시장보고서
상품코드
2114769
영상 유도 치료 시스템 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Image Guided Therapy System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 영상 유도 치료 시스템 시장 규모는 2025년 53억 9,000만 달러로 평가되었습니다. 2026년에는 56억 7,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 5.12%로 성장을 지속하여, 2031년에는 72억 7,000만 달러에 이를 것으로 예측됩니다.
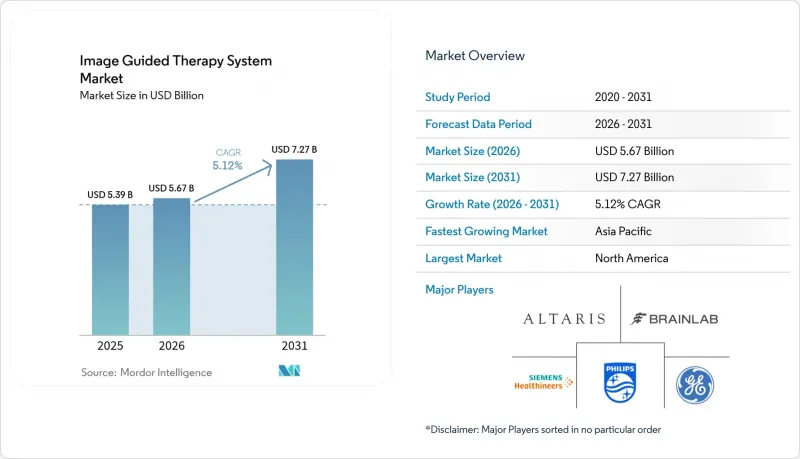
본 보고서에서는 산업을 제품 유형별(초음파 진단 장치, 기타), 기술별(전자기 내비게이션, 기타),용도별(뇌신경외과, 기타), 최종 사용자별(병원 및 클리닉, 외래수술센터(ASC), 기타), 모달리티의 이동성별(고정식 시스템, 기타), 지역별로 분류하고 있습니다. 시장 규모와 전망은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 영상 유도 치료 시스템 시장 동향 및 인사이트
고령 인구 증가
현재 65세 이상 환자는 외과 수술을 받는 환자층 중에서 가장 빠르게 증가하고 있으며, 이로 인해 조직 손상을 최소화하고 회복을 앞당기는 정밀한 전자기 내비게이션의 도입이 확산되고 있습니다. MRI 유도 집속 초음파 치료를 통해 허약한 고령자는 본태성 진전에 대한 개두술을 피할 수 있으며, 재입원을 줄이면서 질 조정 생존 연수(QALY)를 향상시킬 수 있습니다. 의료 시스템 예산 담당자들은 초기 영상 촬영 비용이 이후의 수술 후 비용을 상쇄한다는 점을 인식하고 있습니다.
만성 질환으로 인한 부담 증가
심혈관 질환, 종양 질환, 신경 질환은 합쳐서 전 세계 사망 원인의 70% 이상을 차지하고 있어, 재현성이 높은 영상 유도 하의 치료가 필수적입니다. 딥러닝을 활용한 심전도 분석은 구조적 심장 질환 감지에서 95%의 정확도를 달성하여, 실시간 3D 영상을 통한 카테터 기반 치료의 조기 시행을 촉진하고 있습니다. 만성 질환으로 인한 재정적 부담이 증가함에 따라, 평생에 걸친 치료 부담을 경감시키는 기술의 도입이 더욱 강력하게 추진되고 있습니다.
통합 시스템의 높은 자본 비용
내비게이션, 로봇 기술, AI 영상 기술을 융합한 종합적인 시스템 일체는 100만-300만 달러의 비용에 더해 연간 15-20%의 서비스 수수료가 발생하기 때문에 이익률이 낮은 중견 병원에게는 도입 장벽이 되고 있습니다. 리스나 성과 연계형 계약을 통해 이러한 장벽은 완화되지만, 대학 부속 병원이 누리는 규모의 경제를 완전히 해소할 수는 없습니다.
부문별 분석
내시경은 소화기내과, 비뇨기과, 호흡기과 등 폭넓은 부문에서 활용할 수 있는 유연성 덕분에 2025년 영상 유도 치료 시스템 시장에서 33.02%의 점유율을 유지했습니다. 병원에서는 기존 내시경 채널을 통해 전자기 추적 프로브를 통합함으로써 추가 비용을 절감하고 있습니다. MRI 시스템은 시장 규모는 작지만, 집속 초음파, 레이저 절제술, 심부 뇌 신경 조절이 실시간 MRI 스위트로 전환됨에 따라 연평균 5.60%의 성장이 예상됩니다. 각 벤더들은 현재 스캔과 절개 사이를 원활하게 전환할 수 있는 로봇 액세서리가 장착된 수술용 1.5테슬라 자석을 제공합니다.
초음파 플랫폼은 휴대용 카트의 경우, 방 차폐 요건이 낮고 고정식 CT에 비해 비용이 몇 분의 일로 충분하기 때문에 외래 진료 센터 사이에서 인기를 얻고 있습니다. X선 C-암은 방사선 피폭에 대한 우려에도 불구하고, 빈번하게 시행되는 혈관조영술에서 여전히 필수적입니다. PET-MRI와 같은 하이브리드 장치는 한 번의 세션으로 종양학 병기 분류를 수행하여 진단용 영상과 치료용 영상의 경계를 모호하게 만들고 있습니다.
전자기 내비게이션은 척추 및 두개골 수술에서 시선 의존성이 없고 서브 mm급의 정밀도를 실현함에 따라, 2025년에는 매출의 29.94%를 차지했습니다. 이 부문의 매출액은 16억 1,000만 달러에 달하여, 같은 해 영상 유도 치료 시스템 시장 규모에서 가장 큰 점유율을 차지했습니다. AI를 통한 채널 계획 및 자동 드릴링으로 수술 시간이 단축됨에 따라, 로봇 보조 영상 유도 시장은 2031년까지 연평균 성장률(CAGR) 6.13%로 성장할 전망입니다.
다기관 공동 연구에 따르면, 실시간 3D/4D AI 시각화 기술을 통해 수동 투시법에 비해 표적 오차가 절반으로 감소합니다. 증강현실(AR) 헤드셋은 CT 데이터를 수술 부위에 투영하여 임플란트의 정렬을 정교하게 합니다. 광학 트래커는 정형외과에서 사지 수술 시 여전히 경제적이지만, 심부 강내에서는 정확도가 떨어집니다.
지역별 분석
2025년에는 학술 의료 시스템, 지원적인 환급 제도, 공급업체의 집중된 존재가 도입을 가속화한 결과, 북미가 매출의 45.18%를 차지하며 1위를 차지했습니다. FDA의 2024년 사이버 보안 최종 규정에 따라 시판 전 요건이 명확해짐에 따라, 공급업체는 멀티모달리티 제품군의 인증을 더 신속하게 진행할 수 있게 되었습니다. 2024년, 미국의 외과용 로봇 부문에 대한 벤처 투자액은 20억 달러를 넘어섰으며, 국내 경쟁이 격화되고 있습니다. 보험사들은 병원에 대해 설비 투자의 정당성을 설명할 것을 압박하고 있지만, 산업 재편을 통해 네트워크 전체에 걸친 도입이 가능해졌으며, 수술 건수 증가에 따라 비용을 분산시킬 수 있게 되었습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 6.55%로 확대될 것으로 예측됩니다. 중국의 공립병원 개혁으로 인해 예산이 고성능 영상 장비에 배정되고 있으며, ‘건강 중국 2030’ 계획에서는 최소 침습 심장 카테터 검사실에 대한 보조금이 지급되고 있습니다. 일본의 초고령화 사회로 인해 저침습 치료에 대한 수요가 증가하고 있으며, 국내 제조업체들은 도시 지역의 소규모 병원에 적합한 MRI 대응 로봇을 선도적으로 개발하고 있습니다. 인도의 민간 병원 체인은 의료 관광을 유치하기 위해 휴대용 초음파 진단 장치와 내비게이션 시스템 세트를 도입하고 있는 반면, 한국은 국내 제조 역량을 연구 개발에 대한 후한 세제 혜택과 결합하고 있습니다.
유럽은 의료기기 규정(MDR) 하에서 여전히 기술 실증의 장으로 남아 있습니다. NICE와 같은 의료기술평가기관은 비용 대비 효과를 평가하며, 공급업체에 치료 성과 향상을 문서화할 것을 촉구하고 있습니다. 독일에는 전 세계에 모듈식 부품을 공급하는 중규모 영상 기기 제조업체 클러스터가 존재합니다. 2025년에 시행될 EU의 AI법에서는 수술 지원 소프트웨어에 대해 투명성이 높은 알고리즘 로그를 의무화하고 있어, 검증 주기는 장기화되겠지만 규제를 준수하는 공급업체에게는 선구자로서의 우위가 주어질 것입니다. 그 밖의 중동 및 아프리카에서는 브라질과 사우디아라비아가 카테터실과 수술실을 일체화한 복합 시설을 도입하여 외상 치료 네트워크를 강화하고 있어, 후발 국가들에게도 새로운 길이 열리고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, the image guided therapy system market size is expected to grow from USD 5.39 billion in 2025 to USD 5.67 billion in 2026 and is forecast to reach USD 7.27 billion by 2031 at 5.12% CAGR over 2026-2031.
This report Segments the Industry Into by Product Type (Ultrasound Systems, and More), by Technology (Electromagnetic Navigation, and More), by Application (Neurosurgery, and More), by End-User (Hospitals and Clinics, Ambulatory Surgery Centers, Others), by Modality Portability (Fixed Systems, and More) and Geography. The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Image Guided Therapy System Market Trends and Insights
Growing geriatric population
Patients aged 65+ now constitute the fastest-growing surgical cohort, prompting wider adoption of precise electromagnetic navigation that limits tissue trauma and speeds recovery. MRI-guided focused ultrasound lets fragile elders avoid open craniotomy for essential tremor, improving quality-adjusted life years while trimming readmissions. Health-system budget holders recognize that upfront imaging costs offset downstream postoperative expenses.
Rising burden of chronic diseases
Cardiovascular, oncologic and neurologic disorders collectively drive over 70% of deaths worldwide, making repeatable, image-guided interventions essential. Deep-learning ECG analytics reach 95% accuracy in detecting structural heart disease, fueling earlier referrals to catheter-based repair guided by real-time 3D imaging . Fiscal strain from chronic illness sharpens the case for technologies that reduce lifelong care volumes.
High capital cost of integrated systems
Comprehensive suites that blend navigation, robotics and AI imaging cost USD 1-3 million plus 15-20% annual service fees, deterring mid-tier hospitals with thin margins. Leasing and outcome-based contracts soften this barrier but cannot erase scale advantages enjoyed by academic centers.
Other drivers and restraints analyzed in the detailed report include:
- Rapid shift to minimally invasive, image-guided procedures
- Expansion of hybrid operating rooms in tertiary hospitals
- Regulatory convergence enabling multi-modality interoperability
- Radiation & electromagnetic exposure concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Endoscopes retained 33.02% of the Image Guided Therapy System market in 2025 as their flexibility spans gastroenterology, urology and pulmonology. Hospitals integrate electromagnetic tracking probes through existing endoscope channels, trimming incremental spend. MRI systems, though smaller in volume, are forecast to expand 5.60% annually as focused ultrasound, laser ablation and deep-brain neuromodulation migrate into real-time MRI suites. Vendors now offer intra-operative 1.5 T magnets with robotic accessories that pivot seamlessly between scan and incision.
Ultrasound platforms gain momentum among ambulatory centers because portable carts need lower room shielding and cost fractions of fixed CT. X-ray C-arms stay vital for high-volume angiography despite radiation scrutiny. Hybrids such as PET-MRI tackle oncology staging in single sessions, blurring lines between diagnostic and therapeutic imaging.
Electromagnetic navigation commanded 29.94% revenue in 2025 owing to line-of-sight independence and sub-millimeter accuracy in spine and cranial work. Segment revenue hit USD 1.61 billion, representing the highest slice of the Image Guided Therapy System market size that year. Robotic-assisted imaging guidance is poised to climb 6.13% CAGR through 2031 as AI route-planning and automated drilling cut operating times.
Real-time 3D/4D AI visualization halves targeting error versus manual fluoroscopy, according to multicenter trials. Augmented reality headsets project CT data onto the surgical field, refining implant alignment. Optical trackers remain economical for orthopedic extremity work yet lose precision in deep cavities.
Complete Report Scope:
- By Product Type
- Ultrasound Systems
- Endoscopes
- Magnetic Resonance Imaging (MRI)
- X-ray Fluoroscopy / C-arms
- Positron Emission Tomography (PET)
- Single-Photon Emission CT (SPECT)
- Others
- By Technology
- Electromagnetic Navigation
- Robotic-assisted Imaging Guidance
- AI-Enhanced Real-time 3D/4D Imaging
- Augmented / Mixed-Reality Visualization
- Optical & Laser-based Tracking
- By Application
- Neurosurgery
- Cardiac Surgery & Structural Heart
- Orthopedic & Spine
- Urology
- Oncology & Ablation
- Others
- By End-user
- Hospitals and Clinics
- Ambulatory Surgery Centers
- Others
- By Modality Portability
- Fixed Systems
- Mobile C-arms
- Hand-held / Portable
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led with 45.18% revenue in 2025 as academic health systems, supportive reimbursement and dense vendor presence speed adoption. The FDA's 2024 cybersecurity final rule clarified premarket requirements, letting suppliers certify multi-modality suites more quickly. U.S. venture investment in surgical robotics surpassed USD 2 billion in 2024, intensifying domestic competition. While payers pressure hospitals to justify capital spend, consolidation affords network-wide rollouts that spread cost over higher procedure volumes.
Asia-Pacific is projected to rise 6.55% CAGR through 2031. China's public-hospital reform funnels budget toward high-end imaging, and the Healthy China 2030 plan subsidizes minimally invasive cardiology labs. Japan's super-aged society raises demand for low-trauma therapy; local makers pioneer MRI-compatible robotics that fit small urban hospitals. India's private chains deploy portable ultrasound and navigation bundles to tap medical tourism, while Korea combines domestic manufacturing strength with heavy R&D tax incentives.
Europe remains a technology proving ground under the Medical Device Regulation. Health-technology assessment agencies such as NICE evaluate cost-utility, nudging suppliers to document outcome gains. Germany hosts clusters of mid-sized imaging OEMs that supply modular components worldwide. EU AI Act rules, effective 2025, require transparent algorithm logs for surgical guidance software, lengthening validation cycles yet offering first-mover advantage for compliant vendors . Elsewhere, Brazil and Saudi Arabia upgrade trauma networks with hybrid cath-lab-OR complexes, opening late-adopter avenues.
- Siemens Healthineers
- GE Healthcare
- Koninklijke Philips
- Medtronic
- Brain Lab
- Stryker
- Olympus
- Karl Storz
- Canon
- Varian (Siemens)
- Accuray
- Intuitive Surgical
- Zimmer Biomet
- Smiths Group
- Insightec
- FUJIFILM
- Esaote
- Shenzhen Mindray Bio-Medical
- Clarius Mobile Health
- Hyperfine
- Novarad (VisAR)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing geriatric population
- 4.2.2 Rising burden of chronic diseases
- 4.2.3 Rapid shift to minimally-invasive, image-guided procedures
- 4.2.4 Expansion of hybrid operating rooms in tertiary hospitals
- 4.2.5 Regulatory convergence enabling multi-modality interoperability
- 4.2.6 VC funding surge for MRI/US-guided robotics & ablation platforms
- 4.3 Market Restraints
- 4.3.1 High capital cost of integrated systems
- 4.3.2 Radiation & electromagnetic exposure concerns
- 4.3.3 Shortage of hybrid-OR-trained specialists
- 4.3.4 Cyber-security & data-integration hurdles for connected devices
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Ultrasound Systems
- 5.1.2 Endoscopes
- 5.1.3 Magnetic Resonance Imaging (MRI)
- 5.1.4 X-ray Fluoroscopy / C-arms
- 5.1.5 Positron Emission Tomography (PET)
- 5.1.6 Single-Photon Emission CT (SPECT)
- 5.1.7 Others
- 5.2 By Technology
- 5.2.1 Electromagnetic Navigation
- 5.2.2 Robotic-assisted Imaging Guidance
- 5.2.3 AI-Enhanced Real-time 3D/4D Imaging
- 5.2.4 Augmented / Mixed-Reality Visualization
- 5.2.5 Optical & Laser-based Tracking
- 5.3 By Application
- 5.3.1 Neurosurgery
- 5.3.2 Cardiac Surgery & Structural Heart
- 5.3.3 Orthopedic & Spine
- 5.3.4 Urology
- 5.3.5 Oncology & Ablation
- 5.3.6 Others
- 5.4 By End-user
- 5.4.1 Hospitals and Clinics
- 5.4.2 Ambulatory Surgery Centers
- 5.4.3 Others
- 5.5 By Modality Portability
- 5.5.1 Fixed Systems
- 5.5.2 Mobile C-arms
- 5.5.3 Hand-held / Portable
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Siemens Healthineers
- 6.3.2 GE HealthCare
- 6.3.3 Koninklijke Philips N.V.
- 6.3.4 Medtronic plc
- 6.3.5 Brainlab AG
- 6.3.6 Stryker Corporation
- 6.3.7 Olympus Corporation
- 6.3.8 KARL STORZ SE & Co. KG
- 6.3.9 Canon Medical Systems
- 6.3.10 Varian (Siemens)
- 6.3.11 Accuray Inc.
- 6.3.12 Intuitive Surgical
- 6.3.13 Zimmer Biomet
- 6.3.14 Smith & Nephew
- 6.3.15 Insightec
- 6.3.16 FUJIFILM Healthcare
- 6.3.17 Esaote SpA
- 6.3.18 Shenzhen Mindray Bio-Medical
- 6.3.19 Clarius Mobile Health
- 6.3.20 Hyperfine
- 6.3.21 Novarad (VisAR)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


