|
시장보고서
상품코드
2116140
규제 보고 및 규정 준수 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Regulatory Reporting And Compliance - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
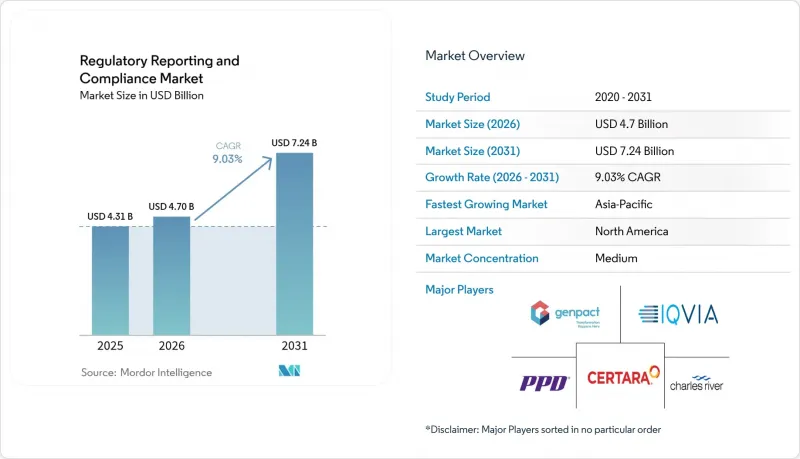
에 의하면, 2026년의 규제 보고 및 규정 준수 시장 규모는 47억 달러로 추정되고 2025년 43억 1,000만 달러에서 확대해, 2031년에는 72억 4,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 동안 연평균 성장률(CAGR) 9.03%를 기록하며 성장할 것으로 전망됩니다.
본 보고서는 서비스 유형(규제 컨설팅, 제품 등록·임상시험 신청, 기타), 서비스 제공업체 유형(사내·아웃소싱), 최종 사용자(제약 회사, 의료기기 제조업체, 생명공학 기업), 지역(북미, 유럽, 기타)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 규제 보고 및 규정 준수 시장 동향 및 인사이트
승인 절차 신속화에 대한 수요 증가
획기적인 치료법(Breakthrough Therapy) 지정에 따라 FDA 심사 기간이 절반으로 단축됨에 따라, 엄격성을 해치지 않으면서 신청 서류를 간소화하는 자문 서비스에 대한 수요가 증가하고 있습니다. 현재 전문 규제 문서 작성자는 신속 심사 대상 신청 서류 작성 시 40%의 가격 프리미엄을 받고 있습니다. 2024년에 개정된 실세계 데이터(RWE) 지침은 새로운 신속화 경로를 열어주는 한편, 대부분의 사내 팀에는 없는 고도의 분석 능력을 요구하고 있습니다. 스폰서가 RWE를 활용하는 가운데, 탄탄한 데이터 사이언스 역량을 갖춘 외부 파트너가 진화하는 증거 기준에 대응할 수 있도록 지원하고 있습니다. 이러한 속도 중시 경향으로 인해 시장 평균을 상회하는 요금 체계가 유지되고 있으며, 벤더와 고객 간의 긴밀한 협력이 공고해지고 있습니다. 시장 출시 기간을 단축해야 한다는 경쟁적 압박 또한 규제 보고 및 규정 준수 시장의 전략적 가치 제안을 더욱 공고히 하고 있습니다.
끊임없이 변화하는 규제 환경
2024년, 규제 당국은 200건 이상의 실질적인 지침 업데이트를 발표했으며, 기업들은 지속적인 모니터링이 요구되고 있습니다. 중국 국가의약품감독관리국은 15건의 새로운 기술 지침을 발표하여 신청 서류의 형식과 안전성 보고 기준을 재정의했습니다. 각국 규정과 ICH 프레임워크가 중복되는 상황에서 이를 적시에 해석하는 것은 이제 많은 사내 팀의 역량을 넘어섭니다. 하이브리드 모델에서는 핵심 전문 지식과 관할 지역별 규정 준수를 담당하는 전문 컨설턴트를 융합함으로써 유연한 자원 배분이 가능해집니다. 세계적 조화에는 장기적인 전망이 있지만, 단기적인 복잡성으로 인해 외부 자문 서비스는 여전히 필수적입니다. 향후 동향을 파악하기 위한 도구에 막대한 예산을 할당하고 있는 기업들은 규제 보고 및 규정 준수 시장의 회복력을 보여주고 있습니다.
개발도상국의 기술적으로 선진화된 인프라 부족
인도, 브라질, 아프리카 일부 지역에서는 여전히 종이 기반 프로세스가 남아 있어, 다국적 후원 기업들은 종이 및 전자 워크플로우를 병행하여 운영할 수밖에 없으며, 이로 인해 규정 준수 비용이 최대 30%까지 증가하고 있습니다. 정부 자금에 의한 인프라 업그레이드는 고르지 않게 진행되고 있어, 클라우드 기반 제출을 방해하는 도입 격차가 남아 있습니다. 각 벤더사는 저대역폭 포털과 온사이트 스캔 허브를 결합한 하이브리드 솔루션을 통해 이러한 격차를 해소하고 있습니다. 현대화 지연으로 인해 첨단 AI 기반 도구의 도입이 억제되고 있으며, 이는 규제 보고 및 규정 준수 시장 전체의 연평균 성장률(CAGR)을 둔화시키고 있습니다.
부문별 분석
컨설팅 부문은 복잡한 제출 절차를 원활하게 진행하는 전문 지식의 강점을 활용하여 2025년 규제 보고 및 규정 준수 시장 점유율의 28.10%를 차지했습니다. 규제 문서 작성 및 공개는 FDA의 eCTD 강화 및 EMA의 구조화된 데이터 요구 사항에 힘입어 연평균 성장률(CAGR) 11.10%로 가속화되고 있습니다. 자동화, AI 기반 컨텐츠 생성, 클라우드 지원 템플릿 라이브러리의 부상으로 자원 배분이 재편되면서, 컨설턴트들은 기술 파트너십 통합을 모색하고 있습니다. 스폰서가 속도를 우선시하는 가운데, 전문 작성 팀은 전 세계 규제 당국의 진화하는 기술 기준을 충족하는 기계 판독 가능한 신청 서류를 제공합니다. 한편, FDA의 경고장 발부가 증가함에 따라 법무 대리 서비스는 꾸준히 성장하고 있으며, 시판 후 안전성 요건의 확대에 따라 약물 안전성 모니터링(파마코비질런스) 컨설팅도 탄력을 받고 있습니다.
디지털화로 인해 컨설팅 기업들은 단순한 자문 기관이 아닌, 기술의 조정자 역할을 수행하게 되었습니다. 이익률을 유지하기 위해 기존 기업들은 모듈 3과 5의 구성 요소를 자동으로 입력하는 독자적인 자연어 처리 엔진을 도입하고 있습니다. 이러한 통합을 통해 전문 인력은 부가가치가 높은 전략적 컨텐츠 작성에 집중할 수 있게 됩니다. 컨설팅 산업에서 기존 기업들의 입지는 여전히 견고하지만, 기술 로드맵을 갖추지 못한 공급업체들은 상품화(commoditization) 위험에 직면해 있습니다. 예측 기간 동안 규제 보고 및 규정 준수 시장에서는 고객이 기술을 활용한 통합 서비스 제품군을 요구함에 따라 컨텐츠 제작, 데이터 엔지니어링, 전략적 자문 간의 융합이 진행될 전망입니다.
지역별 분석
북미는 2025년 기준 규제 보고 및 규정 준수 시장 규모의 41.10%를 차지했으며, 그 배경에는 FDA의 엄격한 기준과 대형 제약 스폰서의 집중이 있습니다. FDA의 AI 지원 심사 도구 도입으로 기술적 규정 준수 요건이 강화됨에 따라, 기계 판독 가능한 형식의 신청 서류에 정통한 컨설턴트에 대한 수요가 증가하고 있습니다. 캐나다가 ‘프로젝트 오비스’에 참여하여 FDA의 종양학 관련 프레임워크와 통합됨에 따라, 국경을 초월한 자문 업무가 더욱 활성화되고 있습니다. 지적 재산권 보호와 강력한 벤처 자금 덕분에 이 지역의 아웃소싱 예산이 확대되어 서비스 가격이 평균 이상의 수준을 유지하고 있습니다.
아시아태평양은 중국의 규제 개혁 의제, 일본의 PMDA에 의한 상담 체계 강화, 인도의 디지털 신청 시범 프로그램의 뒷받침을 받아 2031년까지 연평균 성장률(CAGR) 10.15%로 가장 빠르게 성장하는 지역이 될 것입니다. 규제 성숙도의 다양성이 수요 패턴의 세분화를 초래하고 있습니다. 세계 기업들은 각국 고유의 규정을 해석하기 위해 현지 파트너를 필요로 하는 반면, 현지 제조업체들은 FDA나 EMA의 수출 요건을 충족하기 위한 전문 지식을 요구하고 있습니다. 이중언어 팀과 실시간 정보 플랫폼을 갖춘 지역 센터를 설립한 공급업체들은 규제 보고 및 규정 준수 시장에서 선구자로서의 우위를 확보하고 있습니다.
유럽은 여전히 성숙한 시장이지만, 끊임없이 변화하고 있습니다. EMA가 추진하는 디지털 전환 로드맵과 영국 MHRA의 브렉시트 이후 규제 차이는 복잡성을 가중시켜 자문 수수료 상승 요인으로 작용하고 있습니다. 지속가능성 관련 공시 의무로 인해 규정 준수 범위가 확대되면서, ESG에 중점을 두는 컨설턴트들에게 기회가 생기고 있습니다. 북유럽과 서유럽이 디지털 도입을 주도하는 반면, 중부 및 동유럽 하위 지역은 뒤처지고 있어, 인프라 현대화에 활용되는 틈새 프로젝트의 기회가 발생하고 있습니다. 기타 중동 및 아프리카에서는 기술 인프라 부족으로 인해 도입 속도가 완만하지만, 다국적 기업들이 임상시험 및 제조 거점을 확대하고 있어 장기적인 기회가 기대됩니다. 전 세계 보건 기관들의 목표 지향적인 역량 강화 이니셔티브를 통해 새로운 컨설팅 수익원이 점차 개발되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.31According to Mordor Intelligence, the regulatory reporting and compliance market size in 2026 is estimated at USD 4.70 billion, growing from 2025 value of USD 4.31 billion with 2031 projections showing USD 7.24 billion, growing at 9.03% CAGR over 2026-2031.
This report is Segmented by Service Type (Regulatory Consulting, Product Registration & Clinical Trial Applications, and More), Service Provider Type (In-House and Outsourcing), End User (Pharmaceutical Companies, Medical Device Companies, and Biotechnology Companies), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Regulatory Reporting And Compliance Market Trends and Insights
Growing Demand for Faster Approval Process
Breakthrough therapy designation halves FDA review timelines, creating premium demand for advisory services that compress submissions without compromising rigor. Specialized regulatory writers now command 40% price premiums for expedited dossiers. Real-world evidence (RWE) guidelines, updated in 2024, open new acceleration avenues yet require advanced analytics unavailable in most in-house teams. As sponsors harness RWE, external partners with robust data-science capabilities help navigate evolving evidence standards. This emphasis on speed sustains above-market fee structures and cements deep vendor-client collaboration. Competitive pressure to reduce launch gaps reinforces the regulatory reporting and compliance market's strategic value proposition.
Continuously Changing Regulatory Landscape
In 2024, regulators issued more than 200 substantive guideline updates, forcing companies to maintain continuous surveillance. China's National Medical Products Administration released 15 new technical guidelines, reshaping dossier formats and safety-reporting thresholds. Timely interpretation of overlapping national and ICH frameworks now exceeds the capacity of many internal teams. Hybrid models blend core expertise with specialized consultants for jurisdiction-specific compliance, enabling flexible resource allocation. While global harmonization holds long-term promise, near-term complexity keeps external advisory services indispensable. Companies allocating higher budgets for horizon-scanning tools illustrate the regulatory reporting and compliance market's resilience.
Lack of Technologically Advanced Infrastructure in Developing Nations
Paper-based processes persist in India, Brazil, and parts of Africa, forcing multinational sponsors to run parallel paper and electronic workflows, inflating compliance costs by up to 30%. Government-funded upgrades progress unevenly, leaving implementation gaps that hamper cloud-based submissions. Vendors address the divide through hybrid solutions combining low-bandwidth portals with on-site scanning hubs. Nonetheless, slow modernization tempers adoption of advanced AI-driven tools, moderating the regulatory reporting and compliance market's broader CAGR.
Other drivers and restraints analyzed in the detailed report include:
- Digitalization of Regulatory Processes
- Increasing Complexity of Multi-Region Clinical Trials
- Shortage of Skilled Regulatory-Affairs Professionals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Consulting captured 28.10% of the regulatory reporting and compliance market share in 2025 on the strength of expertise in navigating complex submission pathways. Regulatory writing and publishing is accelerating at an 11.10% CAGR, supported by the FDA's enhanced eCTD and the EMA's structured-data mandates. This rise in automation, artificial-intelligence content generation, and cloud-enabled template libraries reshapes resource allocation, prompting consultants to integrate technology partnerships. As sponsors prioritize speed, specialized writing teams deliver machine-readable dossiers that satisfy global agencies' evolving technical standards. Meanwhile, legal-representation services grow steadily due to increased FDA warning-letter activity, and pharmacovigilance consulting gains momentum amid expanded post-market safety requirements.
Digitization casts consulting firms as technology orchestrators rather than pure advisory bodies. To protect margins, incumbents embed proprietary natural-language processing engines that auto-populate Module 3 and 5 components. This integration repositions human experts toward high-value strategic content. Consulting's incumbency remains resilient, yet providers without technology roadmaps risk commoditization. Over the forecast period, the regulatory reporting and compliance market will witness convergence between content generation, data-engineering, and strategic advisory as clients demand unified, technology-enabled service suites.
Complete Report Scope:
- By Service Type
- Regulatory Consulting
- Product Registration & Clinical Trial Applications
- Legal Representation
- Regulatory Writing & Publishing
- Other Regulatory Services
- By Service Provider Type
- In-House
- Outsourcing
- By End User
- Pharmaceutical Companies
- Medical Device Companies
- Biotechnology Companies
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America controlled 41.10% of the regulatory reporting and compliance market size in 2025, anchored by stringent FDA standards and a high concentration of large pharmaceutical sponsors. The agency's adoption of AI-assisted review tools elevates technical-compliance requirements, channeling demand toward consultants adept in machine-readable submissions. Canada's participation in Project Orbis and alignment with FDA oncology frameworks further sparks cross-border advisory engagements. Intellectual-property protection and strong venture funding amplify the region's outsourcing budgets, sustaining above-average service pricing.
Asia-Pacific is the fastest-growing region at a 10.15% CAGR through 2031, powered by China's regulatory reform agenda, Japan's PMDA consultation enhancements, and India's digital-submission pilot programs. Diversity of regulatory maturity creates fragmented demand patterns: global firms need local partners to interpret country-specific rules, while indigenous manufacturers seek expertise to meet FDA and EMA export requirements. Vendors that establish regional centers with bilingual teams and real-time intelligence platforms capture early-mover advantages in the regulatory reporting and compliance market.
Europe remains a mature but evolving arena. EMA's ongoing digital-transformation roadmap and the UK MHRA's post-Brexit divergence introduce complexity that bolsters advisory fees. Sustainability-related disclosure obligations broaden the compliance remit, creating opportunities for ESG-focused consultants. Northern and Western Europe lead digital adoption, whereas Central and Eastern sub-regions lag, opening niche engagements for infrastructure modernization. Elsewhere, Latin America, the Middle East, and Africa register slower uptake due to limited technical infrastructure but represent long-term opportunities as multinationals expand trials and manufacturing footprints. Targeted capacity-building initiatives by global health agencies gradually unlock new consulting revenue streams.
- Accenture
- AmerisourceBergen / Cencora
- Celegence
- Certara
- Charles River
- Clinilabs
- Freyr Solutions
- Genpact
- ICON
- Indegene
- IQVIA
- LabCorp
- MED-EL
- Navitas Life Sciences
- Parexel International
- PharmaLex GmbH
- PPD
- ProPharma Group
- Syneos Health
- WuXi App Tec
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Demand For Faster Approval Process
- 4.2.2 Continuously Changing Regulatory Landscape
- 4.2.3 Digitalization of Regulatory Processes
- 4.2.4 Increasing Complexity of Multi-Region Clinical Trials
- 4.2.5 AI-Enabled Regulatory-Intelligence Platforms Shorten Dossier Cycles
- 4.2.6 ESG-Driven Disclosure Mandates Expand Compliance Scope
- 4.3 Market Restraints
- 4.3.1 Lack of Technologically Advanced Infrastructure in Developing Nations
- 4.3.2 Complicated Local and Global Regulatory Norms
- 4.3.3 Shortage of Skilled Regulatory-Affairs Professionals
- 4.3.4 Cyber-Security & Data-Residency Hurdles for Cloud Compliance Tools
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Service Type
- 5.1.1 Regulatory Consulting
- 5.1.2 Product Registration & Clinical Trial Applications
- 5.1.3 Legal Representation
- 5.1.4 Regulatory Writing & Publishing
- 5.1.5 Other Regulatory Services
- 5.2 By Service Provider Type
- 5.2.1 In-House
- 5.2.2 Outsourcing
- 5.3 By End User
- 5.3.1 Pharmaceutical Companies
- 5.3.2 Medical Device Companies
- 5.3.3 Biotechnology Companies
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.5.4 Brazil
- 5.4.5.5 Argentina
- 5.4.5.6 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Accenture
- 6.3.2 AmerisourceBergen / Cencora
- 6.3.3 Celegence LLC
- 6.3.4 Certara LP
- 6.3.5 Charles River Laboratories International Inc.
- 6.3.6 Clinilabs Inc.
- 6.3.7 Freyr Solutions
- 6.3.8 Genpact Ltd
- 6.3.9 ICON PLC
- 6.3.10 Indegene
- 6.3.11 IQVIA Holdings Inc.
- 6.3.12 Labcorp Drug Development
- 6.3.13 Medelis Inc.
- 6.3.14 Navitas Life Sciences
- 6.3.15 Parexel International Corporation
- 6.3.16 PharmaLex GmbH
- 6.3.17 Pharmaceutical Product Development LLC (PPD)
- 6.3.18 ProPharma Group
- 6.3.19 Syneos Health
- 6.3.20 WuXi AppTec
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment