

|
시장보고서
상품코드
2117511
재생 미용 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Regenerative Aesthetics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
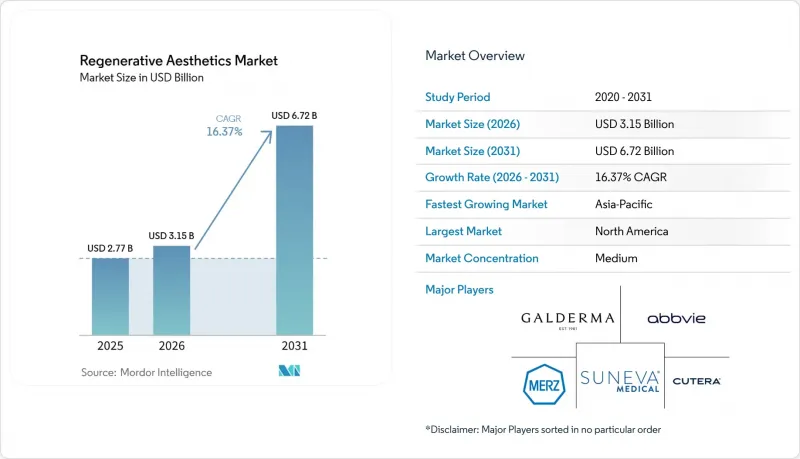
재생 미용 시장은 2025년 27억 7,000만 달러로 평가되었습니다. 2026년 31억 5,000만 달러에서 2031년까지 67억 2,000만 달러로 확대되며 2026년부터 2031년에 걸쳐 CAGR 16.37%를 나타낼 전망입니다.
본 보고서는 제품 유형(생물학적 제제 및 세포 제품, 기타), 기술(자가 유래 생물학적 제제, 기타), 용도(얼굴 회춘 및 볼륨 회복, 기타), 최종 사용자(피부과 클리닉 및 미용 의료 의사, 기타), 지역(북미, 유럽, 아시아태평양, 기타)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 재생 미용 시장 동향 및 인사이트
재시술 빈도의 감소와 지속적이며 자연스러운 결과
환자들이 과도한 주입이나 움직임이 부족한 결과에서 벗어나, 콜라겐 재생, 조직 재형성, 자연스러운 움직임을 동반한 결과를 선호하게 됨에 따라 재생 미용 시장은 탄력을 받았습니다. 이러한 변화는 상업적으로도 중요한데, 클리닉이 PRP(다혈소판 혈장)와 바이오자극제를 결합하고 체계적인 사후 관리 진료를 포함함으로써 재생 미용 프로토콜에 프리미엄 가격을 책정할 수 있기 때문입니다. 2025년 『Journal of Clinical Medicine』지의 보고에 따르면, 지방 유래 간질 혈관 분획(SVF) 겔이 눈 주위 피부 질감과 콜라겐 밀도를 개선한 것으로 나타났으며, 이는 생물학적으로 활성인 치료 계획으로의 전환을 뒷받침합니다. 또한, 갈데르마(Galderma)는 2025년에 GLP-1 요법 사용에 따른 얼굴 볼륨 감소에 대해 스컬프트라(Sculptra)와 레스틸렌 리프트(Restylane Lift)를 병용했을 때, 9개월에 걸친 SHAPE Up HIT 임상시험 데이터를 발표하며 환자 만족도가 지속됨을 보여주었습니다. 재생 미용 시장에서 이러한 지속성은 단순히 볼륨을 더하는 것뿐만 아니라 조직의 질을 회복시키는 것을 목표로 하는 병용 요법에 대해 명확한 프리미엄 가격 책정을 뒷받침하고 있습니다.
세포 유래 물질, 엑소좀 및 생체 재료를 결합한 프로토콜의 채택 확대
재생 미용 시장에서는 PRP가 여전히 중심적인 위치를 차지하고 있습니다. 그 이유는 자가 유래라는 점, 의료기기로 승인된 조제 시스템 내에서 확립된 역할, 그리고 많은 새로운 치료법보다 더 견고한 근거 기반을 갖추고 있기 때문입니다. 『Dermatology and Therapy』지에 게재된 2025년 메타분석에 따르면, PRP는 모발 밀도 향상 및 탈모 완화에 있어 안전하고 유효하며, 검토 대상이 된 모든 임상시험을 통해 심각한 이상반응은 확인되지 않았습니다. 반면, 미국 FDA는 치료용 주사를 목적으로 하는 엑소좀 제품이 미승인 생물학적 제제라는 견해를 거듭 표명해 왔으며, 이로 인해 동종 유래 접근법에는 규제상의 압박이 계속 가해지고 있어, 규정을 준수하는 자가 유래 접근법이 우선시되고 있습니다. 이러한 상황으로 인해 재생 미용 시장은 승인된 PRP 시스템, 밀폐형 조제 플랫폼, 그리고 규제 기반이 보다 명확한 생물학적 제제와 의료기기의 조합과 같은 제품 전략으로 나아가고 있습니다.
엑소좀, 줄기세포 및 복합 제품에 대한 규제상의 모호성
재생 미용 시장은 여전히 명백한 규제상의 공백에 직면해 있습니다. 이는 엑소좀 및 줄기세포 관련 제품에 대한 임상적 관심이 공식적인 제품 승인 속도를 앞지르는 속도로 진행되고 있기 때문입니다. 미국 FDA는 치료 용도를 목적으로 하는 엑소좀 제품을 미승인 생물학적 제제로 규정하고 있으며, 미국에서는 미용 목적의 주사용으로 승인된 엑소좀 제품이 단 하나도 없습니다. 이러한 상황으로 인해 시장은 양극화되고 있습니다. 즉, 인가된 자가 유래 PRP 시스템이나 승인된 생체 자극제는 표준 경로를 통해 성장할 수 있는 반면, 보다 실험적인 제품의 경우 대규모 상용화가 여전히 어려운 상황이 지속되고 있습니다. 대형 공급업체들은 소규모 사업자들이 따라올 수 없는 수준의 문서화, 규정 준수, 의사 교육에 대한 투자를 충분히 할 수 있기 때문에 이점을 누리고 있습니다. 재생 미용 시장에서는 이러한 상황으로 인해 승인 절차가 명확한 제품 카테고리에 성장이 집중되고, 여전히 법적 회색지대에 있는 제품의 보급은 주춤하고 있습니다.
부문별 분석
2025년, 재생 미용 시장 규모의 49.84%를 생물학적 제제 및 세포 제품이 차지했으며, 이는 공급업체의 수익 및 클리닉에서의 사용 측면에서 명백한 주축이 되고 있습니다. 이러한 우위는 PRP 시스템, 폴리뉴클레오티드 주사제, 그리고 지방 유래 세포 제제가 임상의들이 과학적 근거에 기반을 두고 있다고 간주하며, 환자에게 설명하기도 용이하다고 여기는 치료 계획에서 중심적인 역할을 하고 있음을 반영합니다. 재생 미용 시장이 이러한 제품으로 기울고 있는 이유는 단순한 필러에서 조직 반응, 피부 질 개선, 그리고 단계적인 리모델링으로의 전환을 촉진하기 때문입니다. 그 결과, 이 카테고리에서 제품의 주도적 지위는 수요의 강도뿐만 아니라 보다 실용적인 규제 경로도 반영하고 있습니다.
복합 제품 및 의약품 및 의료기기 복합 제품은 2031년까지 연평균 성장률(CAGR) 18.92%로 확대될 것으로 예측되며, 재생 미용 시장에서 가장 빠르게 성장하는 제품 부문이 되고 있습니다. 생체 재료 및 필터는 다단계 프로토콜에서 스캐폴드, 세포외 기질 성분 및 생체 자극성 재료의 중요성이 점점 더 커지고 있기 때문에 여전히 중요한 위치를 차지하고 있습니다. 의료기기 및 장비 시장 점유율은 여전히 작지만, 고주파 마이크로니들링 및 집속 초음파 시스템이 단독 시술로 판매될 뿐만 아니라 바이오 제제와 병용되는 경우가 늘어나면서 그 역할은 확대되고 있습니다. 이러한 추세는 재생 미용 시장에서 일회성 치료 범주가 아닌, 클리닉의 통합된 워크플로우에 직접 통합될 수 있는 제품 설계가 높이 평가받고 있음을 시사합니다.
2025년에는 자가 유래 바이오로직스가 시장 수익의 53.67%를 차지하며, 이 기술은 재생 미용 시장에서 가장 광범위한 도입 기반을 확립했습니다. 그 강점은 면역원성 위험이 낮고, 시술자가 익숙하며, 피부 및 모발 적용에 있어 PRP 유래 성장 인자 접근법을 뒷받침하는 연구가 점점 늘어나고 있다는 점에 있습니다. 따라서 자가 유래 시스템은 재생 치료 메뉴를 구축하거나 확장하고 있는 많은 클리닉에게 여전히 가장 실용적인 도입 지점이 되고 있습니다.
기기 지원형 복합 제품은 2031년까지 연평균 성장률(CAGR) 19.24%를 나타낼 것으로 예측되며, 재생 미용 시장에서 가장 빠르게 확대될 기술 분야가 될 전망입니다. 생체 재료 및 조직 스캐폴드는 흉터 관리, 상처 지원, 조직 신호 전달은 물론 물리적 지지력이 중요한 구조적 용도에서 계속해서 유용합니다. 기기와 결합된 제품이 지닌 상업적 매력은 분명합니다. 클리닉이 조직 자극과 정밀한 투여를 결합할 수 있기 때문에 치료의 서사성을 높이고 프리미엄 가격 책정이 가능하기 때문입니다. 실제로 재생 메디컬 에스테틱 시장은 생물학적 제제의 효과를 보다 가시화하고 측정하기 쉽게 하며, 대규모 치료 네트워크 전반에 걸쳐 재현성을 높이는 기술로 전환되고 있습니다.
지역별 분석
2025년, 북미는 재생 미용 시장 점유율의 43.92%를 차지하며 여전히 최대의 지역별 수익 기반을 유지했습니다. 이 지역의 위상은 시술 1회당 소비자 지출액이 높고, 의료 종사자 대상 교육 네트워크가 밀집되어 있으며, 생체 자극성 주사제 및 기기의 조합에 대한 조기 접근이 뒷받침되고 있습니다. 미국 재생 미용 시장의 경우, 클리닉의 조직화가 진행되고 있는 점도 시장 형성의 한 요인이 되고 있습니다. 구체적으로, LaserAway는 2026년 6월까지 224개 클리닉을 운영하며, Avelure Med Spa는 2026년 5월에 12곳에서 개업했습니다. 또한, FDA의 규제 집행도 중요한 요소입니다. 이로 인해 의료 제공업체의 지출은 미승인 엑소좀 주사가 아닌, 규제를 준수하는 자가 유래 생물학적 제제나 승인된 생체 자극제로 향하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 18.76%를 나타낼 것으로 예측되며, 재생 미용 시장에서 가장 빠르게 성장하는 지역입니다. 한국은 주사제를 통한 재생의학 혁신의 거점으로 자리매김하고 있는 반면, 중국과 인도에서는 시술이 보급되고 클리닉 인프라가 확충됨에 따라 지역 수요 기반이 지속적으로 확대되고 있습니다. 아시아태평양의 재생 미용 시장이 급속히 확대되고 있는 것은 이 지역의 의료 제공업체들이 단일 치료법에 의존하기보다는 주사제와 의료기기를 결합한 치료 계획을 적극적으로 채택하고 있기 때문입니다.
유럽의 경우, 독일, 프랑스, 이탈리아, 영국이 이미 바이오자극제나 특성이 충분히 규명된 재생의료 제품을 위한 성숙한 인프라를 갖추고 있어, 재생 미용 시장에서 계속해서 큰 점유율을 차지하고 있습니다. 또한, 이 지역에서는 확립된 제품의 폭넓은 임상 사용을 지원하면서, 신규 시장 진출기업에 대해서는 규정 준수 요건을 높이는 규제 체계도 효과를 거두고 있습니다. GCC 시장이 주도하는 중동 및 아프리카과 브라질이 주도하는 남미 지역은 시장 규모는 아직 작지만, 의료 관광의 확대, 클리닉 밀도의 향상, 그리고 고품질 치료에 대한 접근성 개선에 힘입어 여전히 성장을 이어가고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.02According to Mordor Intelligence, the regenerative aesthetics market is projected to expand from USD 2.77 billion in 2025 and USD 3.15 billion in 2026 to USD 6.72 billion by 2031, registering a CAGR of 16.37% between 2026 and 2031.
This report is Segmented by Product Type (Biologics and Cell Products, and Others), Technology (Autologous Biologics, and Others), Application (Facial Rejuvenation and Volume Restoration, and Others), End-User (Dermatology Clinics and Aesthetic Physicians, and Others), and Geography (North America, Europe, Asia-Pacific, and Others). The Market Forecasts are Provided in Terms of Value (USD).
Global Regenerative Aesthetics Market Trends and Insights
Durable, Natural-Looking Outcomes with Lower Retreatment Frequency
The regenerative aesthetics market gained momentum as patients moved away from overfilled and static outcomes and started favoring results tied to collagen renewal, tissue remodeling, and natural movement. This change matters commercially because clinics can price regenerative protocols at a premium when they combine PRP with biostimulators and structured follow-up visits. A 2025 Journal of Clinical Medicine publication reported that adipose-derived stromal vascular fraction gel improved periorbital skin quality and collagen density, which supports the move toward biologically active treatment plans. Galderma also reported nine-month SHAPE Up HIT trial data in 2025 showing lasting patient satisfaction when Sculptra and Restylane Lyft were combined for facial volume loss linked to GLP-1 therapy use. In the regenerative aesthetics market, that kind of durability is supporting a clear premium for combinations that aim to restore tissue quality rather than only add volume.
Rising Adoption of Cell-Based, Exosome, and Biomaterial Combination Protocols
The regenerative aesthetics market still centers on PRP because it has an autologous origin, an established role in device-cleared preparation systems, and a stronger evidence base than many newer modalities. A 2025 meta-analysis in Dermatology and Therapy found that PRP was safe and effective for improving hair density and reducing hair loss, with no serious adverse events across the reviewed trials.At the same time, the U.S. FDA has continued to state that exosome products intended for therapeutic injection are unapproved biologics, which is keeping regulatory pressure on allogeneic approaches and favoring compliant autologous routes. That is pushing the regenerative aesthetics market toward product strategies that stay closer to cleared PRP systems, closed preparation platforms, and biologic-device combinations with clearer regulatory footing.
Regulatory Ambiguity for Exosomes, Stem Cells, and Combination Products
The regenerative aesthetics market still faces a clear regulatory gap because clinical interest in exosomes and stem-cell-linked products has moved faster than formal product authorization. The U.S. FDA has stated that exosome products intended for therapeutic use are unapproved biologics, and no exosome product has been approved for aesthetic injection in the United States. This is creating a split market where cleared autologous PRP systems and approved biostimulators can grow through standard channels while more experimental offerings remain difficult to commercialize at scale. Larger suppliers benefit because they are better able to invest in documentation, compliance, and physician education that smaller operators often cannot match. For the regenerative aesthetics market, that keeps growth concentrated in product categories with clearer approval pathways and slows wider adoption of offerings that still sit in a legal gray area.
Other drivers and restraints analyzed in the detailed report include:
- Premium Clinic Chain Expansion and Medical Tourism in High-Growth Markets
- Growing Consumer Preference for Minimally Invasive and Regenerative Anti-Aging Treatments
- High Out-of-Pocket Treatment Cost
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Biologics and cell products held 49.84% of the regenerative aesthetics market size in 2025, which made this the clear anchor of supplier revenue and clinic usage. That lead reflects the central role of PRP systems, polynucleotide injectables, and adipose-derived cellular preparations in treatment plans that clinicians view as scientifically grounded and easier to position with patients. The regenerative aesthetics market is leaning toward these products because they support the move from simple filling to tissue response, skin quality improvement, and gradual remodeling. As a result, product leadership in this category reflects both demand strength and a more workable regulatory path.
Combination products and drug-device is forecasted to expand at an 18.92% CAGR through 2031, which makes it the fastest-growing product segment in the regenerative aesthetics market. Biomaterials and Filters still hold an important place because scaffolds, extracellular matrix components, and bio-stimulatory materials are becoming more relevant in multi-step protocols. Devices and Equipment remain smaller by share, but their role is widening as radiofrequency microneedling and focused ultrasound systems are used with biologics rather than sold only as standalone procedures. This pattern suggests the regenerative aesthetics market is rewarding product designs that fit directly into integrated clinic workflows rather than single-use treatment categories.
Autologous biologics commanded 53.67% of market revenue in 2025, giving this technology the broadest installed base in the regenerative aesthetics market. Its strength comes from low immunogenic risk, practitioner familiarity, and a growing set of studies that support PRP-derived growth factor approaches across skin and hair applications. Autologous systems, therefore, remain the most practical entry point for many clinics building or expanding regenerative treatment menus.
Device-assisted combination products is projected to grow at a 19.24% CAGR through 2031, making it the fastest-moving technology line in the regenerative aesthetics market. Biomaterials and Tissue Scaffolds remain useful in scar care, wound support, and structural applications where physical support matters alongside tissue signaling. The commercial appeal of device combinations is clear because they let clinics pair tissue stimulation with precise delivery, which improves treatment storytelling and supports premium pricing. In practice, the regenerative aesthetics market is moving toward technologies that make biologics more visible, more measurable, and easier to repeat across large treatment networks.
Complete Report Scope:
- By Product Type
- Biologics and Cell Products
- Biomaterials and Fillers
- Combination Products and Drug-Device Hybrids
- Devices and Equipment
- By Technology
- Autologous Biologics
- Allogeneic Cell-Based Products
- Biomaterials and Tissue Scaffolds
- Device-Assisted Combination Procedures
- By Application
- Facial Rejuvenation and Volume Restoration
- Hair Restoration
- Scar Revision and Acne Scarring
- Wound Healing and Reconstructive Adjuncts
- Body Contouring and Soft-Tissue Defect Repair
- By End-User
- Dermatology Clinics and Aesthetic Physicians
- Plastic Surgery Clinics and Ambulatory Surgical Centers
- Med Spas and Aesthetic Chains
- Hospitals and Specialty Centers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 43.92% of the regenerative aesthetics market share in 2025, which kept it as the largest regional revenue base. The region's position rests on high consumer spending per procedure, dense practitioner training networks, and early access to biostimulatory injectables and device combinations. The regenerative aesthetics market in the United States is also being shaped by a more organized clinic layer, as LaserAway reached 224 clinics by June 2026 and Avelure Med Spa launched across 12 locations in May 2026. FDA enforcement also matters because it pushes provider spending toward compliant autologous biologics and approved biostimulators rather than unapproved exosome injections.
Asia-Pacific is forecasted to grow at an 18.76% CAGR through 2031, making it the fastest-growing region in the regenerative aesthetics market. South Korea remains an innovation hub for injectable regeneration, while China and India continue to widen the regional demand base through rising procedure uptake and expanding clinic infrastructure. The regenerative aesthetics market in Asia-Pacific is moving quickly because regional providers are adopting both injectables and device-linked treatment plans rather than relying on one modality alone.
Europe continues to hold a significant share in the regenerative aesthetics market because Germany, France, Italy, and the United Kingdom already have mature infrastructure for biostimulators and well-characterized regenerative products. The region also benefits from regulatory frameworks that support broad clinical use of established products while raising compliance requirements for newer entrants. Middle East and Africa, led by GCC markets, and South America, led by Brazil, remain smaller but are still expanding as medical tourism, clinic density, and premium treatment access improve.
- Abbvie
- Anika Therapeutics
- Arthrex
- BTL Industries, Inc.
- Candela Medical
- CollPlant Biotechnologies Ltd.
- Croma-Pharma GmbH
- Cutera
- EmCyte
- Galderma
- Hologic
- Integra LifeSciences
- Lipogems International SpA
- Lumenis
- Merz Pharma GmbH and Co. KGaA
- Prollenium Medical Technologies Inc.
- RegenLab SA
- Revance Therapeutics, Inc.
- Sinclair Pharma plc
- Suneva Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Durable, Natural-Looking Outcomes with Lower Retreatment Frequency
- 4.2.2 Rising Adoption of Cell-Based, Exosome, and Biomaterial Combination Protocols
- 4.2.3 Premium Clinic Chain Expansion and Medical Tourism in High-Growth Markets
- 4.2.4 AI-Guided Imaging, Treatment Planning, and Personalized Aesthetic Protocols
- 4.2.5 Growing Consumer Preference for Minimally Invasive and Regenerative Anti-Aging Treatments
- 4.2.6 Advancements in Platelet-Rich Plasma (PRP), Platelet-Rich Fibrin (PRF), and Autologous Biologics Technologies
- 4.3 Market Restraints
- 4.3.1 Regulatory Ambiguity for Exosomes, Stem Cells, and Combination Products
- 4.3.2 Technique Sensitivity and Lack of Standardized Clinical Protocols
- 4.3.3 High Out-of-Pocket Treatment Cost
- 4.3.4 Limited Long-Term Clinical Evidence and Reimbursement Support
- 4.4 Supply/Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Biologics and Cell Products
- 5.1.2 Biomaterials and Fillers
- 5.1.3 Combination Products and Drug-Device Hybrids
- 5.1.4 Devices and Equipment
- 5.2 By Technology
- 5.2.1 Autologous Biologics
- 5.2.2 Allogeneic Cell-Based Products
- 5.2.3 Biomaterials and Tissue Scaffolds
- 5.2.4 Device-Assisted Combination Procedures
- 5.3 By Application
- 5.3.1 Facial Rejuvenation and Volume Restoration
- 5.3.2 Hair Restoration
- 5.3.3 Scar Revision and Acne Scarring
- 5.3.4 Wound Healing and Reconstructive Adjuncts
- 5.3.5 Body Contouring and Soft-Tissue Defect Repair
- 5.4 By End-User
- 5.4.1 Dermatology Clinics and Aesthetic Physicians
- 5.4.2 Plastic Surgery Clinics and Ambulatory Surgical Centers
- 5.4.3 Med Spas and Aesthetic Chains
- 5.4.4 Hospitals and Specialty Centers
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.3.1 AbbVie Inc.
- 6.3.2 Anika Therapeutics, Inc.
- 6.3.3 Arthrex, Inc.
- 6.3.4 BTL Industries, Inc.
- 6.3.5 Candela Corporation
- 6.3.6 CollPlant Biotechnologies Ltd.
- 6.3.7 Croma-Pharma GmbH
- 6.3.8 Cutera, Inc.
- 6.3.9 EmCyte Corporation
- 6.3.10 Galderma SA
- 6.3.11 Hologic, Inc.
- 6.3.12 Integra LifeSciences Holdings Corporation
- 6.3.13 Lipogems International SpA
- 6.3.14 Lumenis Be Ltd.
- 6.3.15 Merz Pharma GmbH and Co. KGaA
- 6.3.16 Prollenium Medical Technologies Inc.
- 6.3.17 RegenLab SA
- 6.3.18 Revance Therapeutics, Inc.
- 6.3.19 Sinclair Pharma plc
- 6.3.20 Suneva Medical, Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


