

|
시장보고서
상품코드
2118134
재택치료용 SaMD(Software-as-a-Medical Device) 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Home Healthcare Software As A Medical Device (SaMD) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
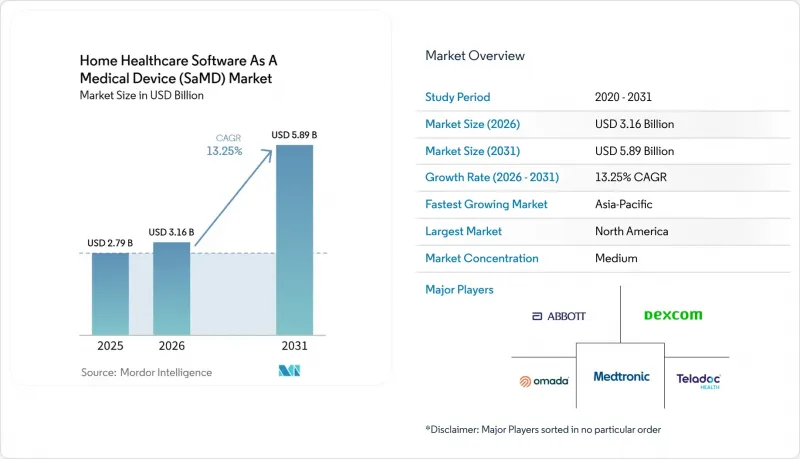
에 의하면, 재택치료용 SaMD(Software-as-a-Medical Device) 시장 규모는 2025년에 27억 9,000만 달러로 평가되었고, 2026년 31억 6,000만 달러에서 2031년까지 58억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 13.25%를 나타낼 전망입니다.
본 보고서는 제품 유형별(임상 의사결정 지원 소프트웨어, 원격 환자 모니터링 소프트웨어, 기타), SaMD의 위험 분류별(저위험 SaMD, 중위험 SaMD, 고위험 SaMD), 배포 방식별(클라우드 기반 SaMD, 온프레미스형 SaMD, 하이브리드형 SaMD), 용도별(심혈관 질환 관리, 당뇨병 관리, 호흡기 질환 관리, 기타), 최종 사용자별(재택치료 서비스 사업자, 병원·건강 시스템, 기타), 지역별(북미, 유럽, 아시아태평양, 기타)로 분류되어 있습니다. 예측치는 금액(달러)으로 표시되어 있습니다.
재택치료용 SaMD 시장 동향 및 인사이트
재택 환경에서의 만성 질환 관리 확대
심혈관 질환, 당뇨병, 호흡기 질환은 진료소에서의 치료에만 그치지 않고, 의료팀의 부담을 계속해서 가중시키고 있습니다. 재택치료용 SaMD 시장은 재택 환자에 대한 원격 측정, 임상 위험 평가, 치료 계획 조정을 지원하고 있습니다. 2026년 6월, Dexcom은 자사의 CONNECT 무작위 대조 시험에서 인슐린을 사용하지 않고 G7 기반 모니터링을 이용한 2형 당뇨병 환자에서 일반 치료에 비해 HbA1c의 통계적으로 유의미한 감소가 확인되었다고 보고했습니다. 이러한 증거를 바탕으로 보험사는 만성 질환 프로그램 내 재택 모니터링을 평가하기 위한 보다 명확한 근거를 확보할 수 있게 되었습니다.
인력 부족으로 인해 임상 업무의 자동화 수요가 증가하고 있습니다.
인력 부족으로 인해 재택 간호 분야의 일정 관리, 기록 작성, 간호 조정 도구의 가치가 높아졌습니다. 2026년 1월, Axxess의 보고서에 따르면 재택 간호 제공 기관의 60% 이상이 2026년을 앞두고 주요 과제로 인력 채용 및 유지를 꼽았습니다. 재택치료용 SaMD 시장은 반복적인 사무 업무를 줄이고 임상 담당자의 일정 관리를 개선하는 도구를 제공함으로써 이러한 과제에 대응하고 있습니다. 2026년 3월, Homecare Homebase는 ‘Curate Scribe’를 도입했습니다. 이 도구는 입원 1건당 돌봄 시작 시 문서 작성 시간을 35-45분 단축하도록 설계되었습니다.
사이버 보안, 개인정보 보호, 의료 데이터 보호 요건
사이버 보안은 커넥티드 재택 간호 시스템 구매 시 중요한 고려 사항이 되고 있습니다. 2026년 7월, AdaptHealth는 사회 공학 기법을 이용한 사고를 통해 특정 클라우드 기반 환자 관리 시스템, 문서 보관 플랫폼 및 외부 전자 의료 기록 포털에 위협 행위자가 무단 접근했음을 밝혔습니다. 이 사고에는 보호 대상인 건강 정보 및 보험 청구 인증 정보가 관련되어 있어, 재택 케어 시스템의 기밀성이 매우 높다는 점이 부각되었습니다. 재택치료용 SaMD 시장에서는 각 기관이 클라우드 제어, 제3자 접근, 네이티브 접근 제어, 이상 감지, 독립적인 보안 보증, HIPAA 보안 규정 준수, 임상적 책임, 데이터 품질 관리 등을 평가하기 때문에 벤더 심사 주기가 장기화되고 있습니다.
부문 분석
2025년, 임상 의사결정 지원 소프트웨어는 재택치료용 SaMD 시장 점유율의 34.35%를 차지했습니다. 이 소프트웨어는 재택치료 전자 건강 기록(EHR) 워크플로우에 위험 평가, 프로토콜 지침,알림을 통합함으로써 만성 질환 프로그램을 지원하며, 진료 제공 중 임상의가 용도를 전환해야 할 필요성을 줄였습니다. WellSky는 2026년 5월, AI를 활용한 워크플로우, 임상 인텔리전스, 환자 기록을 임상의의 모바일 단말기에서 통합한 ‘Point of Care’ 앱을 출시했습니다. 이 회사는 해당 앱의 ‘Scribe’ 기능을 통해 400개 이상의 재택치료 기관에서 진료 기록 작성 시간을 최대 50% 단축할 수 있다고 밝혔습니다.
원격 환자 모니터링 소프트웨어 시장은 2031년까지 연평균 성장률(CAGR) 15.93%로 확대될 것으로 예측됩니다. 이러한 성장은 재택 모니터링용 하드웨어 도입 대수 증가와 병원 및 클리닉 퇴원 후에도 지속되는 환자 데이터의 가치를 반영한 것입니다. 디지털 테라퓨틱스도 제품 구성에 기여하고 있으며, Omada Health는 2025년 실적 보고에서 회원 수가 200만 명 이상, 기업 및 건강보험 플랜 고객 수가 2,000개사 이상에 달했다고 보고했습니다. 각 공급업체는 문서 작성, 커뮤니케이션, 환자 모니터링을 단일 워크플로우 내에서 연동함으로써 중복 입력을 줄이고, 시기적절한 임상 조치를 지원하고 있습니다.
2025년, 중위험 SaMD는 재택치료용 SaMD 시장의 55.45%를 차지했습니다. 이 분류에는 510(k) 승인은 필요하지만, 더 엄격한 시판 전 승인(PMA)은 필요하지 않은 임상에서 사용되는 많은 심혈관 질환 및 당뇨병 관리 도구가 포함됩니다. 이러한 시스템은 진단 지원과 치료 조정을 결합하는 경우가 많으며, 오작동이 환자 안전에 영향을 미칠 수 있으므로 제조업체는 성능을 검증해야 합니다. 확립된 근거와 규제 관련 문서를 보유한 의료기기 제조업체는 이 부문에서 우위를 점할 수 있을 것으로 보입니다.
저위험 SaMD는 2031년까지 연평균 성장률(CAGR) 17.67%를 나타낼 것으로 예측됩니다. 이러한 성장은 직접적인 임상 위험이 낮은 웰니스 코칭, 수면 분석, 라이프스타일 데이터 활용 부문에서의 기회를 반영한 것입니다. FDA는 2026년 1월, 임상 의사결정 지원 소프트웨어에 관한 최신 지침을 발표하여 특정 비의료기기형 임상 의사결정 지원 기능을 구별하기 위한 기준을 명확히 했습니다. 고위험 SaMD는 여전히 규모는 작지만, 자율형 진단 도구나 폐쇄 루프 인슐린 투여 분야에서 전략적으로 중요하며, 메드트로닉(Medtronic)은 2025년에 SmartGuard 알고리즘과 Meal Detection 기술을 포함한 자사의 MiniMed Flex 시스템에 대해 FDA 승인을 획득했다고 발표했습니다.
지역별 분석
2025년, 북미는 재택치료용 SaMD 시장 점유율의 39.66%를 차지했습니다. 이 지역은 재택치료 기관의 기반이 넓고, 확립된 보상 체계가 있으며, 임상 기술 활용도 성숙해 있었습니다. 재택 간병 제공업체들이 모니터링, 기록 및 간병 조정을 위한 도구를 필요로 했기 때문에 미국은 계속해서 주요 수요 거점으로 자리매김했습니다. 캐나다와 멕시코는 재택 및 지역 간병 서비스에 가상 간병이 통합됨에 따라 2차 시장으로서의 지위를 유지했습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 15.56%로 확대될 것으로 예측됩니다. 만성 질환에 대한 수요 증가와 각국의 디지털 헬스 프로그램이 재택 모니터링 및 케어 관리 시스템에 대한 수요를 뒷받침하고 있습니다. 중국, 인도, 일본, 한국은 각각 서로 다른 의료비 재정 및 규제 접근 방식을 채택하고 있습니다. 이 지역에 진출하는 공급업체는 SaMD 프레임워크 전반의 일관성이 높아지는 가운데, 각국의 등록 요건을 고려해야 합니다.
유럽은 독일, 영국, 프랑스, 이탈리아, 스페인이 주도하는 형태로 지역 내 중요한 위치를 차지하고 있습니다. 공공 자금에 의한 시스템 덕분에, 동등한 설비 투자를 동반하지 않고도 서비스 제공 능력을 확대할 수 있는 도구에 대한 수요가 발생하고 있습니다. 중동 및 아프리카와 남미는 여전히 규모는 작지만 수요가 확대되고 있는 지역입니다. 이는 사우디아라비아와 아랍에미리트의 디지털 헬스 인프라 투자, 브라질의 원격의료 보상 제도에 힘입은 것입니다. 지역별 성장 경로는 제각각이므로, 장기적인 보급을 위해서는 현지 파트너십, 유연한 워크플로우, 각국에 맞춘 도입 계획이 필수적입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.03According to Mordor Intelligence, the home healthcare software as a medical device market size was valued at USD 2.79 billion in 2025 and is estimated to grow from USD 3.16 billion in 2026 to reach USD 5.89 billion by 2031, at a CAGR of 13.25% during the forecast period (2026-2031).
This report is Segmented by Product Type (Clinical Decision Support, Remote Patient Monitoring, and More), Risk Classification (Low, Moderate, High-Risk), Deployment (Cloud-Based, On-Premise, Hybrid), Application (Cardiovascular, Diabetes, Respiratory, and More), End User (Home Health Agencies, Hospitals, and More), and Geography (North America, Europe, Asia-Pacific, and More). Forecasts in Value (USD).
Global Home Healthcare Software As A Medical Device (SaMD) Market Trends and Insights
Expansion of Home-Based Chronic Disease Management
Cardiovascular disease, diabetes, and respiratory conditions continued to increase pressure on care teams beyond clinic-based care. The Home Healthcare SaMD Market supports remote measurement, clinical risk assessment, and care plan adjustments for patients at home. In June 2026, Dexcom reported that its CONNECT randomized controlled study showed a statistically significant HbA1c reduction among people with Type 2 diabetes who were not using insulin and used G7-based monitoring compared with routine care. This evidence gave payers a clearer basis for evaluating home-based monitoring in chronic disease programs.
Workforce Shortages Increasing Demand for Clinical Automation
Staffing pressure increased the value of scheduling, documentation, and care coordination tools in home care. In January 2026, Axxess reported that more than 60% of care-at-home organizations identified recruitment and retention as their main challenge entering 2026. The Home Healthcare SaMD Market is responding with tools that reduce repetitive administrative work and improve clinician schedule management. In March 2026, Homecare Homebase introduced Curate Scribe, which is designed to reduce start-of-care documentation by 35-45 minutes per admission.
Cybersecurity, Privacy, and Healthcare Data-Protection Requirements
Cybersecurity has become a key purchasing consideration for connected home care systems. In July 2026, AdaptHealth disclosed that a threat actor gained unauthorized access to certain cloud-based patient management systems, document storage platforms, and external electronic health record portals through a social-engineering incident. The incident involved protected health information and insurance billing credentials, highlighting the sensitivity of home care systems. The Home Healthcare SaMD Market faces longer vendor review cycles as agencies assess cloud controls, third-party access, native access controls, anomaly detection, independent security assurance, HIPAA Security Rule compliance, clinical liability, and data quality controls.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Remote Patient Monitoring and Virtual Care
- Reimbursement and Value-Based Care Incentives
- Home-Environment Data Quality and Algorithm Generalizability Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Clinical Decision Support Software held 34.35% of Home Healthcare SaMD Market share in 2025. It supported chronic disease programs by embedding risk assessment, protocol guidance, and alerts within the home health electronic record workflow, reducing the need for clinicians to switch between applications during care delivery. WellSky launched its Point of Care app in May 2026, combining AI-supported workflows, clinical intelligence, and patient records on a clinician's mobile device. The company stated that its Scribe feature could reduce charting time by up to 50% across more than 400 home health agencies.
Remote Patient Monitoring Software is forecast to expand at a 15.93% CAGR through 2031. Growth reflects the broader installed base of home monitoring hardware and the value of continuous patient data after hospital or clinic discharge. Digital therapeutics also contribute to the product mix, with Omada Health reporting more than 2 million members and more than 2,000 employer and health-plan clients in its 2025 results. Suppliers are linking documentation, communication, and patient monitoring within one workflow to reduce duplicate entry and support timely clinical action.
Moderate-Risk SaMD accounted for 55.45% of the Home Healthcare SaMD Market in 2025. This classification includes many clinically used cardiovascular and diabetes management tools that require 510(k) clearance but not the more demanding premarket approval route. These systems often combine diagnostic support with care coordination, and manufacturers must validate performance because malfunctions could affect patient safety. Device makers with established evidence and regulatory documentation can gain an advantage in this segment.
Low-Risk SaMD is forecast to grow at a 17.67% CAGR through 2031. Growth reflects opportunities in wellness coaching, sleep analysis, and lifestyle data applications with lower direct clinical risk. The FDA issued updated guidance for Clinical Decision Support Software in January 2026, clarifying criteria that help distinguish certain non-device clinical decision support functions. High-Risk SaMD remains smaller but strategically important for autonomous diagnostic tools and closed-loop insulin delivery, with Medtronic announcing FDA clearance of its MiniMed Flex system in 2025, including the SmartGuard algorithm and Meal Detection technology.
Complete Report Scope:
- By Product Type
- Clinical Decision Support Software
- Remote Patient Monitoring Software
- Digital Therapeutics Software
- Patient Engagement and Self-Management Software
- Clinical Documentation and Care-Planning Software
- Care Coordination and Referral Management Software
- Others
- By SaMD Risk Classification
- Low-Risk SaMD
- Moderate-Risk SaMD
- High-Risk SaMD
- By Deployment
- Cloud-Based SaMD
- On-Premise SaMD
- Hybrid Deployment
- By Application
- Cardiovascular Disease Management
- Diabetes Management
- Respiratory Disease Management
- Sleep Disorder Management
- Neurological Disorder Management
- Oncology Support and Remote Monitoring
- Medication Adherence and Safety
- Post-Acute Care Monitoring
- Others
- By End User
- Home Health Agencies
- Hospitals and Health Systems
- Hospices and Palliative Care Providers
- Skilled Nursing Facilities
- Senior Living and Life Plan Communities
- Physician Groups and Ambulatory Care Providers
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 39.66% of the Home Healthcare SaMD Market share in 2025. The region had a large base of home health agencies, established reimbursement structures, and mature clinical technology use. The United States remained the key demand center, as home-based care providers needed tools for monitoring, documentation, and care coordination. Canada and Mexico remained secondary markets as virtual care was incorporated into home and community care services.
Asia-Pacific is forecast to expand at a 15.56% CAGR through 2031. Rising chronic disease needs and national digital health programs are supporting demand for home monitoring and care-management systems. China, India, Japan, and South Korea each have different health financing and regulatory approaches. Suppliers entering the region need to account for national registration requirements as broader SaMD frameworks become more aligned.
Europe has a meaningful regional position, led by Germany, the United Kingdom, France, Italy, and Spain. Publicly funded systems create demand for tools that can expand service capacity without equivalent capital investment. The Middle East and Africa and South America remain smaller but developing areas of demand, supported by digital health infrastructure investments in Saudi Arabia and the United Arab Emirates and Brazil's telehealth reimbursement framework. Regional growth will not follow a uniform path, making local partnerships, adaptable workflows, and country-specific implementation plans critical for long-term adoption.
- Abbott Laboratories
- AlayaCare Inc.
- Axxess, Inc.
- Brightree LLC
- Cardiosense, Inc.
- Dexcom
- Garmin
- Hexoskin
- HHAeXchange Inc.
- Homecare Homebase, LLC
- MatrixCare, Inc.
- Medtronic
- Microsoft
- Netsmart Technologies, Inc.
- Omada Health
- PointClickCare Technologies Inc.
- Resmed
- Respiree Pte. Ltd.
- Teladoc Health
- WellSky Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Home-Based Chronic Disease Management
- 4.2.2 Workforce Shortages Increasing Demand for Clinical Automation
- 4.2.3 Growth of Remote Patient Monitoring and Virtual Care
- 4.2.4 Reimbursement and Value-Based Care Incentives
- 4.2.5 FDA-Accepted Predetermined Change Control Plans for AI Software
- 4.2.6 Home-Based Real-World Evidence and Decentralized Clinical Trials
- 4.3 Market Restraints
- 4.3.1 Cybersecurity, Privacy, and Healthcare Data-Protection Requirements
- 4.3.2 Fragmented Reimbursement and Regulatory Pathways
- 4.3.3 Home-Environment Data Quality and Algorithm Generalizability Risk
- 4.3.4 Clinical Liability for Automated or Semi-Automated Patient Recommendations
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Software and Cloud Suppliers
- 4.7.3 Bargaining Power of Healthcare Providers and Payers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Product Type
- 5.1.1 Clinical Decision Support Software
- 5.1.2 Remote Patient Monitoring Software
- 5.1.3 Digital Therapeutics Software
- 5.1.4 Patient Engagement and Self-Management Software
- 5.1.5 Clinical Documentation and Care-Planning Software
- 5.1.6 Care Coordination and Referral Management Software
- 5.1.7 Others
- 5.2 By SaMD Risk Classification
- 5.2.1 Low-Risk SaMD
- 5.2.2 Moderate-Risk SaMD
- 5.2.3 High-Risk SaMD
- 5.3 By Deployment
- 5.3.1 Cloud-Based SaMD
- 5.3.2 On-Premise SaMD
- 5.3.3 Hybrid Deployment
- 5.4 By Application
- 5.4.1 Cardiovascular Disease Management
- 5.4.2 Diabetes Management
- 5.4.3 Respiratory Disease Management
- 5.4.4 Sleep Disorder Management
- 5.4.5 Neurological Disorder Management
- 5.4.6 Oncology Support and Remote Monitoring
- 5.4.7 Medication Adherence and Safety
- 5.4.8 Post-Acute Care Monitoring
- 5.4.9 Others
- 5.5 By End User
- 5.5.1 Home Health Agencies
- 5.5.2 Hospitals and Health Systems
- 5.5.3 Hospices and Palliative Care Providers
- 5.5.4 Skilled Nursing Facilities
- 5.5.5 Senior Living and Life Plan Communities
- 5.5.6 Physician Groups and Ambulatory Care Providers
- 5.5.7 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 AlayaCare Inc.
- 6.3.3 Axxess, Inc.
- 6.3.4 Brightree LLC
- 6.3.5 Cardiosense, Inc.
- 6.3.6 Dexcom, Inc.
- 6.3.7 Garmin Ltd.
- 6.3.8 Hexoskin
- 6.3.9 HHAeXchange Inc.
- 6.3.10 Homecare Homebase, LLC
- 6.3.11 MatrixCare, Inc.
- 6.3.12 Medtronic plc
- 6.3.13 Microsoft Corporation
- 6.3.14 Netsmart Technologies, Inc.
- 6.3.15 Omada Health, Inc.
- 6.3.16 PointClickCare Technologies Inc.
- 6.3.17 ResMed Inc.
- 6.3.18 Respiree Pte. Ltd.
- 6.3.19 Teladoc Health, Inc.
- 6.3.20 WellSky Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


