

|
시장보고서
상품코드
2120350
저분자 의약품 Drug Discovery : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Small Molecule Drug Discovery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
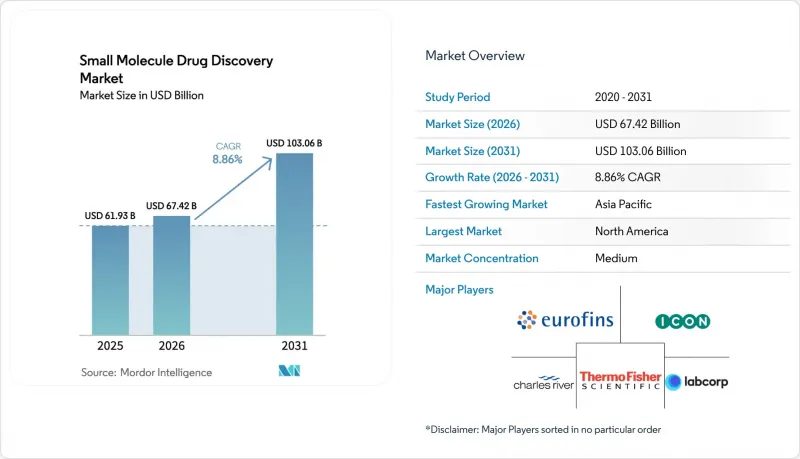
에 따르면 저분자 의약품 Drug Discovery 시장 규모는 2025년 619억 3,000만 달러에서 2026년에는 674억 2,000만 달러로 확대하며, 2026-2031년에 CAGR 8.86%로 추이하며, 2031년에는 1,030억 6,000만 달러에 달할 것으로 예측됩니다.
이 보고서는 치료 분야(종양학, 순환기계 등), 신약 개발 단계(표적 확인·검증 등),약제 유형(합성 저분자 화합물 등), 기술(고속 스크리닝(HTS) 등), 최종사용자(제약사 등) 및 지역(북미 등)별로 분류되어 있습니다. 시장 규모 및 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 저분자 의약품 신약 개발 시장의 동향과 인사이트
증가하는 만성질환 및 노화 관련 질환의 부담
암, 심혈관 질환, 대사성 질환이 신규 분자 실체 승인을 주도하고 있으며, 그 예로 FDA가 2024년에 만성 림프구성 백혈병 치료제 자누브루티닙을 승인한 것을 들 수 있습니다. 2030년까지 북미와 유럽에서는 각각 65세 이상 인구 비율이 20%를 넘어설 전망이며, 신경퇴행성 질환, 퇴행성 관절염 및 동반 질환을 치료하는 약물에 대한 지속적인 수요가 확실시됩니다. 현재 각 제약사는 고령자의 약동학 및 동반 질환 모델링을 이전보다 더 이른 단계에서 반영하고 있으며, 이로 인해 전임상 단계의 비용은 증가하는 반면, 후기 단계에서의 개발 중단률은 감소하고 있습니다. 자가면역 질환을 대상으로 한 프로그램은 JAK 억제제 및 S1P 조절제의 신속 승인 혜택을 받고 있으며, 규제 측면에서 명확한 로드맵이 제시되고 있습니다. 이러한 요인들이 결합되며, 2031년까지 자가면역 질환에 초점을 맞춘 파이프라인은 두 자릿수 성장을 유지할 전망입니다.
바이오의약품에 비해 우수한 제조성 및 비용 효율성
저분자 의약품은 콜드 체인 비용, 정맥 주입을 위한 인프라, 대용량 바이오리액터가 필요하지 않기 때문에 만성질환의 총 치료 비용을 40-60% 절감합니다. 화이자(Pfizer)는 2024년 저분자 의약품 포트폴리오의 영업이익률이 바이오의약품에 비해 15포인트 높다고 밝혔습니다. 아시아태평양의 보험 지급 기관은 경구 투여 제네릭 의약품을 우선시하는 필수 의약품 리스트을 중시하고 있으며, 이것이 판매량 확대를 지원하고 있습니다. 대형 제약사들은 자본 생산성을 최적화하기 위해 유병률이 높은 질환에 대한 경구용 제제로 연구개발의 중점을 재조정하고 있으며, 이러한 전환이 연평균 성장률(CAGR) 8.86%를 지원하고 있습니다.
후기 임상시험에서의 실패 증가와 비용 상승
3상 임상시험의 중도 탈락률은 여전히 높은 수준을 유지하고 있으며, 2024-2025년에 안전성 및 유효성 부족을 이유로 여러 항암제 후보가 완전 응답서(CRL)를 수령했습니다. 현재, 임상시험 신청(IND)에 앞서, 스폰서는 확실한 생체내 데이터나 중개 바이오마커를 요구하고 있으며, 이로 인해 전임상 단계의 지출은 증가하는 반면, 하류 공정의 위험은 감소하고 있습니다. 후기 단계에서의 실패를 감당할 수 없는 중소 바이오기술 기업은 업계 재편의 압력에 직면해 있습니다.
부문 분석
2025년 매출 중 종양학 분야가 31.56%를 차지하여, 저분자 의약품 신약 개발 시장에서 가장 큰 점유율을 차지하는 분야임을 입증하고 있습니다. 자가면역 질환은 차세대 JAK 억제제 및 S1P 수용체 조절제의 승인을 바탕으로 연평균 성장률(CAGR) 12.25%를 기록하며, 다른 모든 적응증을 능가하는 성장을 보일 것으로 전망됩니다. 조직 선택적 면역 억제를 통해 안전성 프로파일이 개선됨에 따라 자가면역 질환용 저분자 의약품 신약 개발 시장의 규모는 급속히 확대될 전망입니다. 한편, 중추신경계 파이프라인에서는 알츠하이머병 및 난치성 우울증 치료를 목적으로 NMDA 조절 및 신경염증을 표적으로 하고 있으며, 심혈관계 프로그램에서는 SGLT2 및 GLP-1의 작용 기전을 활용하여 심혈관 및 대사 측면에서 효과를 가져오고 있습니다.
호흡기 분야 연구는 증가 추세를 보이고 있으며, COPD 및 낭포성 섬유증의 기도 리모델링에 초점을 맞추고 있습니다. 또한 소화기 분야 프로젝트에서는 IBS 및 크론병을 대상으로 한 마이크로바이옴 조절 화합물의 개발이 진행되고 있습니다. 감염병 분야는 항생제 내성 문제로 인해 전략 계획에 다시 포함되었으며, 광범위 항바이러스제 개발이 더 초기 단계로 추진되고 있습니다. 전반적으로 적응증 선택은 규제상의 인센티브 및 바이오마커의 이용 가능성과 부합하며, 자가면역 질환 파이프라인이 가장 빠르게 성장하는 분야로 자리매김하고 있습니다.
2025년에는 선도 화합물 식별에 지출의 24.53%가 할당되었으나, 전임상 단계에서의 후보 화합물 선정은 2031년까지 연평균 성장률(CAGR) 13.85%로 증가할 것으로 예측됩니다. 각 스폰서사는 후기 단계의 위험을 줄이기 위해 ADMET, 독성학, 제형 개발에 더 많은 자원을 투입하고 있으며, 스테이지 게이트 방식에 따른 거버넌스에서는 IND 신청 전에 생체내 유효성이 요구되고 있습니다. 따라서 저분자 의약품 신약 개발 분야의 전임상 후보 화합물 선정 시장 규모는 더욱 가파른 성장 곡선을 그리고 있습니다. DNA 인코딩 라이브러리는 저렴한 비용으로 히트의 다양성을 높이고, AlphaFold2는 구조 기반 설계를 지원하며, CRISPR를 통한 검증은 표적의 필수성을 명확히 밝혀줍니다. 이러한 체계적인 전환을 통해 프로젝트 시작은 다소 지연될 수 있지만, 비용이 많이 드는 3상 임상시험에서의 실패는 줄어들게 됩니다.
지역별 분석
북미는 FDA의 신속 승인 절차, 보스턴과 샌프란시스코의 풍부한 AI 인재, 그리고 견실한 벤처 자금 조달에 힘입어 2025년 매출의 39.53%를 차지했습니다. 2025년에는 55개의 신약이 FDA 승인을 받았으며, 그 대부분은 저분자 화합물이었습니다. 캐나다와 멕시코는 신뢰성 프레임워크 하에서 비용 효율적인 임상 시험 거점을 추가하여 지역의 수용 능력을 확대했습니다. 따라서 북미의 저분자 의약품 신약 개발 시장 규모는 생태계가 차별화된 ‘퍼스트-인-클래스(First-in-Class)’ 자산에 초점을 맞추고 있으므로 아시아태평양만큼은 아니더라도 꾸준히 성장할 것으로 예상됩니다.
유럽은 EMA의 PRIME 지정과 긴밀한 학술 네트워크에 힘입어 여전히 의미 있는 규모를 유지하고 있습니다. 2024년에는 PRIME 대상인 12개의 소분자 프로그램이 파이프라인에 추가되었습니다. 독일, 영국, 프랑스는 구조 기반 및 단편 기반 신약 개발에 강점을 보이는 반면, 이탈리아와 스페인은 외부 위탁 화학 연구를 유치하고 있습니다. 보험 급여 제도의 분절화와 AI 도입 지연이 성장 전망을 둔화시키고 있지만, 해당 지역의 과학적 기반을 통해 지속적인 참여가 보장되고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 11.21%로 예측되며, 가장 빠르게 성장하는 지역입니다. 중국 국가약품감독관리국(NMPA)은 국내에서 개발된 항암제 및 희귀질환 치료제 분자에 대해 조건부 승인을 발급하여 국내 혁신을 촉진했습니다. 인도의 Syngene사와 Jubilant사는 히트 물질에서 리드 화합물로 이어지는 개발 서비스를 확대했으며, 일본 제약 업계는 파이프라인 활성화를 위해 AI에 투자했습니다. 한국, 호주, 싱가포르는 신약 개발 초기 단계에 공공 보조금을 투입한 반면, 동남아시아 국가들은 제조 및 임상시험 인프라를 확충했습니다. 이러한 노력들이 맞물려, 해당 지역의 저분자 의약품 신약 개발 시장은 세계 평균을 상회하는 성장을 달성하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.02According to Mordor Intelligence, the small molecule drug discovery market size is expected to grow from USD 61.93 billion in 2025 to USD 67.42 billion in 2026 and is forecast to reach USD 103.06 billion by 2031 at 8.86% CAGR over 2026-2031.
This report is Segmented by Therapeutic Area (Oncology, Cardiovascular, and More), Discovery Phase (Target Identification & Validation and More), Drug Type (Synthetic Small Molecules and More), Technology (High-Throughput Screening (HTS) and More), End User (Pharmaceutical Companies, and More) and Geography (North America and More). The Market and Forecasts are Provided in Terms of Value (USD).
Global Small Molecule Drug Discovery Market Trends and Insights
Growing Chronic & Age-Related Disease Burden
Cancer, cardiovascular, and metabolic disorders dominate new molecular-entity filings, illustrated by the FDA's 2024 approval of zanubrutinib for chronic lymphocytic leukemia. North America and Europe will each exceed 20% population aged >=65 by 2030, ensuring sustained demand for therapeutics that address neurodegeneration, osteoarthritis, and comorbid conditions. Sponsors now integrate geriatric pharmacokinetics and comorbidity modeling earlier, which raises pre-clinical spend but lowers late-stage attrition. Autoimmune programs profit from accelerated approvals of JAK inhibitors and S1P modulators, signaling a clear regulatory path. Together these factors anchor double-digit growth in autoimmune-focused pipelines through 2031.
Superior Manufacturability & Cost-Efficiency vs Biologics
Small molecules avoid cold-chain cost, infusion infrastructure, and high-volume bioreactors, lowering total cost of care by 40-60% for chronic diseases. Pfizer disclosed operating margins 15 percentage points higher for its small-molecule portfolio versus biologics in 2024. Asia-Pacific payers prioritize essential-medicine lists that favor orally dosed generics, reinforcing volume expansion. Large pharmaceutical firms are rebalancing R&D toward oral agents for high-prevalence disorders to optimize capital productivity, a shift that supports the 8.86% CAGR.
Escalating Late-Stage Failure & Cost Inflation
Phase 3 attrition remains stubbornly high, with several oncology candidates receiving complete response letters in 2024-2025 due to safety or efficacy gaps. Sponsors now demand robust in-vivo data and translational biomarkers before IND, raising pre-clinical spend yet lowering downstream risk. Smaller biotechnology firms, unable to absorb late-stage failures, face consolidation pressure.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Progress in AI-Driven Hit-to-Lead Modeling
- Regulatory Fast-Track Designations Accelerating Approvals
- Capital Diversion Toward Biologics & Advanced Therapies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Oncology commanded 31.56% of 2025 revenue, underscoring its status as the largest slice of the small-molecule drug discovery market. Autoimmune disorders are projected to outpace all other indications at a 12.25% CAGR, supported by approvals of next-generation JAK inhibitors and S1P receptor modulators. The small-molecule drug discovery market size for autoimmune disorders is set to expand quickly as tissue-selective immunosuppression improves safety profiles. Meanwhile, central nervous system pipelines target NMDA modulation and neuro-inflammation to treat Alzheimer's and resistant depression, and cardiovascular programs leverage SGLT2 and GLP-1 mechanisms to deliver cardio-metabolic benefits.
Respiratory research is rising, focusing on airway remodeling in COPD and cystic fibrosis, and gastrointestinal projects pursue microbiome-modulating compounds for IBS and Crohn's. Infectious-disease tables re-entered strategic plans because of antimicrobial resistance, pushing broad-spectrum antivirals into earlier stages. Altogether, indication choices align with regulatory incentives and biomarker availability, positioning autoimmune pipelines as the fastest-growing cohort.
Lead identification held 24.53% of spending in 2025, but pre-clinical candidate selection is forecast to rise at a 13.85% CAGR through 2031. Sponsors funnel more resources into ADMET, toxicology, and formulation to de-risk late stages, and stage-gate governance now demands in-vivo efficacy before IND. The small-molecule drug discovery market size for pre-clinical candidate selection is therefore on a steeper growth curve. DNA-encoded libraries boost hit diversity at low cost, AlphaFold2 supports structure-based design, and CRISPR validation informs target essentiality. This disciplined shift slows project starts yet trims costly phase 3 failures.
Complete Report Scope:
- By Therapeutic Area
- Oncology
- Central Nervous System
- Cardiovascular
- Respiratory
- Metabolic Disorders
- Gastrointestinal
- Infectious Diseases
- Autoimmune Disorders
- Other Therapeutic Areas
- By Discovery Phase
- Target Identification & Validation
- Hit Generation & Selection
- Lead Identification
- Lead Optimization
- Pre-clinical Candidate Selection
- By Drug Type
- Synthetic Small Molecules
- Natural-Product Derivatives
- Peptide Mimetics
- PROTACs & Molecular Glues
- Nucleoside Analogues
- By Technology
- High-Throughput Screening (HTS)
- Fragment-Based Drug Discovery (FBDD)
- Structure-Based Drug Design (SBDD)
- Computational / AI-Driven Design
- DNA-Encoded Library Screening
- CRISPR-Based Target Validation
- Bioassay Development & Cell-based Platforms
- By End User
- Pharmaceutical Companies
- Biotechnology Companies
- Academic & Research Institutes
- Contract Research Organizations (CROs)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 39.53% of 2025 revenue, buoyed by FDA expedited pathways, deep AI talent pools in Boston and San Francisco, and robust venture financing. Fifty-five novel drugs cleared the FDA in 2025, with small molecules dominating. Canada and Mexico added cost-efficient trial sites under reliance frameworks, extending regional capacity. The small-molecule drug discovery market size in North America is therefore expected to grow steadily, albeit slower than in Asia-Pacific, as the ecosystem focuses on differentiated first-in-class assets.
Europe maintained meaningful scale, enabled by EMA PRIME designations and a dense academic network. Twelve PRIME-eligible small-molecule programs entered the pipeline in 2024. Germany, the United Kingdom, and France excel in structure-based and fragment-based discovery, while Italy and Spain attract outsourced chemistry work. Reimbursement fragmentation and slower AI adoption temper the growth outlook, yet the region's scientific base secures ongoing participation.
Asia-Pacific is the fastest climber with an 11.21% CAGR projection. China's NMPA issued conditional approvals for locally developed oncology and rare-disease molecules, spurring indigenous innovation. India's Syngene and Jubilant scaled hit-to-lead services, and Japan's pharmaceutical industry invested in AI to revitalize pipelines. South Korea, Australia, and Singapore funneled public grants into early discovery, while Southeast Asian states expanded manufacturing and trial infrastructure. These initiatives collectively lift the small-molecule drug discovery market in the region above global averages.
- AstraZeneca
- Atomwise Inc.
- Benevolent AI
- Charles River
- ChemPartner
- Curia Global Inc.
- Domainex Ltd.
- Eurofins
- Evotec
- Exscientia plc
- GenScript Biotech
- ICON
- Insilico Medicine
- Jubilant Group
- LabCorp
- Pfizer
- Recursion Pharmaceuticals
- Relay Therapeutics
- Schrodinger Inc.
- Syngene International Ltd.
- Thermo Fisher Scientific
- WuXi App Tec
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing chronic & age-related disease burden
- 4.2.2 Superior manufacturability & cost-efficiency vs biologics
- 4.2.3 Rapid progress in AI-driven hit-to-lead modeling
- 4.2.4 Regulatory fast-track designations accelerating approvals
- 4.2.5 Mini-flow chemistry enabling on-demand GMP synthesis
- 4.2.6 Quantum-computing molecular simulation breakthroughs
- 4.3 Market Restraints
- 4.3.1 Escalating late-stage failure & cost inflation
- 4.3.2 Capital diversion toward biologics & advanced therapies
- 4.3.3 ESG scrutiny over solvent emissions in synthesis
- 4.3.4 Supply risk for scarce photoredox catalysts
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Therapeutic Area
- 5.1.1 Oncology
- 5.1.2 Central Nervous System
- 5.1.3 Cardiovascular
- 5.1.4 Respiratory
- 5.1.5 Metabolic Disorders
- 5.1.6 Gastrointestinal
- 5.1.7 Infectious Diseases
- 5.1.8 Autoimmune Disorders
- 5.1.9 Other Therapeutic Areas
- 5.2 By Discovery Phase
- 5.2.1 Target Identification & Validation
- 5.2.2 Hit Generation & Selection
- 5.2.3 Lead Identification
- 5.2.4 Lead Optimization
- 5.2.5 Pre-clinical Candidate Selection
- 5.3 By Drug Type
- 5.3.1 Synthetic Small Molecules
- 5.3.2 Natural-Product Derivatives
- 5.3.3 Peptide Mimetics
- 5.3.4 PROTACs & Molecular Glues
- 5.3.5 Nucleoside Analogues
- 5.4 By Technology
- 5.4.1 High-Throughput Screening (HTS)
- 5.4.2 Fragment-Based Drug Discovery (FBDD)
- 5.4.3 Structure-Based Drug Design (SBDD)
- 5.4.4 Computational / AI-Driven Design
- 5.4.5 DNA-Encoded Library Screening
- 5.4.6 CRISPR-Based Target Validation
- 5.4.7 Bioassay Development & Cell-based Platforms
- 5.5 By End User
- 5.5.1 Pharmaceutical Companies
- 5.5.2 Biotechnology Companies
- 5.5.3 Academic & Research Institutes
- 5.5.4 Contract Research Organizations (CROs)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 AstraZeneca plc
- 6.3.2 Atomwise Inc.
- 6.3.3 BenevolentAI
- 6.3.4 Charles River Laboratories
- 6.3.5 ChemPartner
- 6.3.6 Curia Global Inc.
- 6.3.7 Domainex Ltd.
- 6.3.8 Eurofins Discovery
- 6.3.9 Evotec SE
- 6.3.10 Exscientia plc
- 6.3.11 GenScript Biotech
- 6.3.12 ICON plc
- 6.3.13 Insilico Medicine
- 6.3.14 Jubilant Biosys Ltd.
- 6.3.15 Labcorp Drug Development
- 6.3.16 Pfizer Inc.
- 6.3.17 Recursion Pharmaceuticals
- 6.3.18 Relay Therapeutics
- 6.3.19 Schrodinger Inc.
- 6.3.20 Syngene International Ltd.
- 6.3.21 Thermo Fisher Scientific Inc.
- 6.3.22 WuXi AppTec
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


