

|
시장보고서
상품코드
2120522
지리공간 분석 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Geospatial Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
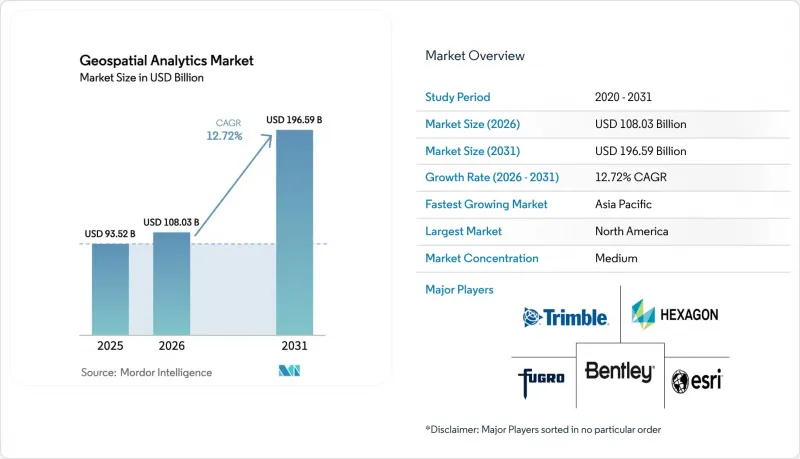
에 의하면, 지리공간 분석 시장 규모는 2025년 935억 2,000만 달러로 평가되었습니다. 2026년 1,080억 3,000만 달러에서 2031년까지 1,965억 9,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 12.72%를 나타낼 것으로 예측됩니다.
본 보고서는 구성 요소(소프트웨어, 서비스, 하드웨어), 분석 유형(지표면 분석, 네트워크 분석 등), 도입 모델(On-Premise, 클라우드), 최종 사용자 산업 분야(정부, 국방·정보 기관, 천연 자원, 유틸리티·통신, 운송 및 물류 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 지리공간 분석 시장 동향 및 인사이트
스마트 시티 프로그램 도입
지방 자치 단체는 교통 관제 센터, 에너지 그리드, 비상 지휘실에 공간 플랫폼을 통합하고 있으며, 이를 통해 지리공간 분석 시장은 도시의 회복력 전략에서 중심적인 역할을 담당하고 있습니다. 뉴욕시의 2024년 IoT 전략에 따르면, 모든 신규 인프라 프로젝트에서 공간 메타데이터를 디지털 트윈으로 스트리밍하는 것이 의무화되어 있으며, 이를 통해 도로, 교량, 수도관의 예측 유지보수가 가능해집니다. 영국은 공공시설에 대한 손상을 억제하기 위해 2025년에 ‘국가 지하 자산 등록부(National Underground Asset Register)’에 4,000만 파운드(5,100만 달러)를 배정했으며, 이는 시범 프로젝트에서 도시 전체로의 확대로의 전환을 시사합니다. 자본 집약적인 On-Premise형 하드웨어보다 구독형 소프트웨어가 선호되고 있습니다. 이는 사용량에 따른 요금 체계가 센서 밀도 증가와 부합하기 때문입니다. 그 결과, 클라우드 공급업체들은 매핑, 경로 안내, 실시간 데이터 스트림을 번들로 제공하며, 중규모 도시의 진입 장벽을 낮추고 있습니다. 따라서 지리공간 분석 시장은 장기적인 수익 전망이 확보된 예측 가능한 지자체와의 계약을 통해 혜택을 보고 있습니다.
5G 지원 위치 정보 서비스의 통합
5G 캐리어 위상 측정을 통해 얻어지는 서브미터급 위치 측위는 도시 지역의 ‘도시 협곡’에서 발생하는 위성 신호 단절을 해소합니다. 3GPP 릴리스 17 사양에서는 안전성이 극히 중요한 자율주행차 용도를 구현하기 위한 무결성 지표가 도입되었습니다. 시스코는 2027년까지 19억 대의 5G 기기가 위치 정보 서비스를 지원할 것으로 예측했습니다. 톰톰(TomTom)은 5G 데이터를 자사의 ‘HD Live Map’에 통합하여 도로변 비콘 없이도 차선 수준의 정확도를 실현했습니다. 배터리 소모 감소와 하드웨어 비용 절감으로 인해 그 적용 범위는 프리미엄 스마트폰에 그치지 않고 웨어러블 기기와 산업용 센서로 확대되고 있습니다. 그 결과, 지리공간 분석 시장에서는 5G 위치 측정과 위성 데이터 및 관성 데이터를 융합하여 어디서나 커버리지를 확보하는 API에 대한 수요가 높아지고 있습니다.
높은 비용과 운영상의 복잡성
공간 데이터 인프라 도입 비용은 컨설팅 및 데이터 수집 비용을 제외하더라도, 다중 사용자 라이선스의 경우 일반적으로 연간 5만 달러부터 시작합니다. 숙련된 지도 제작자나 원격 감지 엔지니어에게는 고액의 급여가 지급되지만, 대도시권 이외의 지역에서는 이러한 인력이 부족합니다. 원시 위성 이미지는 방사 측정 보정, 대기 보정, 오르소 보정이 필요합니다. 각 공정에서는 GPU와 스토리지를 소모하지만, 중소규모 기업에게는 그 비용을 감당하기 어렵습니다. 예산 초과로 인해 투자 회수가 지연되면서, 중견 기업을 중심으로 한 지리공간 분석 시장 플랫폼의 보급이 더뎌지고 있습니다.
부문 분석
2025년에는 소프트웨어가 지리공간 분석 시장의 41.32%를 차지했으나, 서비스 매출은 2026년부터 2031년까지 연평균 성장률(CAGR) 13.37%를 나타낼 것으로 예측됩니다. 딜로이트의 컨설팅 부문은 고객들이 턴키 방식의 기후 리스크 대시보드를 요구하는 가운데, 2025년에 전년 대비 22%의 성장을 기록했습니다. Esri의 컨테이너화된 ArcGIS Enterprise 11.4는 인프라 비용을 30% 절감하고 소프트웨어 수명을 연장했습니다. 라이선스를 취득한 알고리즘과 외부 위탁 데이터 엔지니어링을 융합한 매니지드 플랫폼은 소프트웨어 및 서비스의 경계를 모호하게 만들고 있습니다. 클라우드 GPU 인스턴스가 On-Premise 전용 워크스테이션을 대체하고 있어 하드웨어 수요는 정체되고 있습니다. 지리공간 분석 시장에서는 통합 업체들이 이미지 데이터 구독, 머신러닝 모델, 데이터 파이프라인 유지보수를 묶어 제공하고 있으며, 이로 인해 사내에 공간 분석 전문 지식이 없는 조직의 도입이 가속화되고 있습니다. 따라서 서비스는 여전히 하류 소프트웨어 수익을 창출하는 촉매 역할을 수행하며, 벤더에게 선순환을 만들어내고 있습니다.
계약 점유율이 증가하고 있는 것 중에는 수확량 향상이나 연료비 절감과 연계된 성과 기반 지불을 규정하는 것이 있습니다. 이러한 변화로 인해 벤더의 인센티브가 고객의 성공과 일치하게 되어 고객 유지율이 향상됩니다. GDAL이나 PostGIS와 같은 오픈소스 라이브러리는 진입 장벽을 낮추지만, 고객은 여전히 맞춤화 및 지원에 대해 대가를 지불하고 있습니다. 통합의 복잡성이 증가함에 따라, 자문 파트너들은 새로운 분석 워크플로가 일상 업무에 확실히 정착될 수 있도록 변경 관리 워크숍을 패키지화하고 있습니다. 그 결과, 2031년까지 지리공간 분석 시장에서는 일회성 라이선스 계약보다 더 깊은 파트너십이 주류를 이룰 것으로 전망됩니다.
2025년에는 표면 분석이 시장의 35.78%를 차지했지만, 네트워크 분석은 2031년까지 연평균 성장률(CAGR) 13.54%를 나타낼 것으로 예측됩니다. 라스트 마일 물류 분야에서는 동적 경로 계획을 활용하여 대기 시간을 단축하고 있으며, UPS는 좌회전을 최소화함으로써 연간 1,000만 갤런의 연료를 절약했습니다. 유틸리티자는 송전망의 복원력을 시뮬레이션하여 업그레이드 우선순위를 결정하고 있으며, 공공 안전 기관은 대피 시나리오를 검증하고 있습니다. 지표면 분석은 농업 및 광업 분야에서 주류를 이루고 있으며, 이러한 분야에서는 경사면과 유역이 작물 재배 계획 및 발파 계획 수립에 큰 영향을 미치고 있습니다. 증강현실(AR)의 부상은 지리공간 시각화의 꾸준한 성장을 뒷받침하고 있으며, Bentley사의 iTwin은 틈새 시장에서 몰입형 3D 검토를 주류로 만들고 있습니다. 한편, 공간 통계 및 지오코딩은 역학 및 입지 선정 업무를 뒷받침하고 있습니다. 이처럼 지리공간 분석 시장은 분석 유형에 따라 다양해지고 있지만, 실시간 데이터 스트림과 연동된 네트워크 알고리즘은 여전히 투자 수익률(ROI)을 가장 빠르게 높이는 원동력이 되고 있습니다.
다중 모드 물류에 대한 수요가 증가함에 따라 각 벤더들은 도로, 철도, 해상, 항공 네트워크를 통합된 그래프로 결합하려고 하고 있습니다. 교량 높이나 위험물 운송 규정과 같은 에지상의 제약 조건을 과거 소요 시간 데이터와 결합함으로써 도착 예정 시간(ETA)의 정확도가 향상됩니다. 개발자들은 복잡한 공간 결합을 추상화한 RESTful OGC API 인터페이스를 통해 마이크로서비스를 호출하는 사례가 늘고 있습니다. 이러한 접근 방식은 도입을 가속화하고, 계산 처리를 데이터 근처에서 수행함으로써 지연 시간을 개선합니다. 그 결과, 조직들은 네트워크 분석을 단순한 선택적 부가 기능이 아닌 비즈니스에 필수적인 기능으로 인식하게 되었으며, 이는 지리공간 분석 시장 내 점유율 확대를 더욱 촉진하고 있습니다.
지역 분석
2025년, 북미는 국방 조달과 성숙한 스마트 시티 도입을 견인력으로 지리공간 분석 시장의 35.92% 점유율을 차지했습니다. 미국의 ‘통합 전 영역 지휘통제(Joint All-Domain Command and Control)’ 프로그램은 각 군에 위치 인텔리전스를 통합한 반면, L3Harris는 2024년에 정찰기용 WESCAM MX-25 센서를 공급했습니다. 캐나다 연방 오픈 데이터 포털은 2025년에 지형 및 지적 레이어를 공개하여 상업적 재사용을 촉진했습니다. 멕시코는 재난 대응을 신속히 하기 위해 연안 주에 홍수 감시를 위한 디지털 트윈을 도입하고 있습니다. 신규 도입보다 업데이트 주기가 주류를 이루면서 성장은 둔화되고 있지만, 인공지능(AI) 애드온 기능 덕분에 지출은 서서히 계속 증가하고 있습니다.
아시아태평양은 공공 부문의 대규모 투자에 힘입어 연평균 성장률(CAGR) 13.76%를 기록하며, 지역별로는 가장 빠른 성장 속도를 보일 것으로 예측됩니다. 중국의 베이두(BeiDou) 시스템은 2025년까지 15억 대의 활성 기기를 기록하며 농업, 차량 라이드 셰어링, 긴급 서비스 분야에 확산되었습니다. 인도는 2024년에 ‘국가 지리공간 정책’을 시행하여 고해상도 이미지에 대한 접근을 자유화하고, 각 부처에서 공간 메타데이터 사용을 의무화함으로써 민간 부문의 혁신을 촉진했습니다. 일본은 재해 대책을 위한 3D 도시 모델에 500억 엔(3억 4,000만 달러)을 배정했습니다. 한국과 호주는 스마트 시티 시범 사업을 전개하고 있는 반면, 동남아시아 국가들은 토지 등기 및 산림 모니터링의 현대화를 추진하고 있습니다. 이미지 데이터 가격 하락과 스마트폰 보급 확대에 힘입어 소비자 대상 위치 정보 서비스가 확대되면서 지리공간 분석 시장의 기반이 넓어지고 있습니다.
유럽의 향후 전개는 규제 조화에 달려 있습니다. ‘INSPIRE 지침’은 국경을 초월한 데이터 공유를 촉진하고, 물류 및 환경 관련 앱의 장벽을 낮추고 있습니다. 독일에서는 기후 변화 적응을 목적으로 인프라 데이터를 통합한 전국 규모의 디지털 트윈이 구축되고 있습니다. 영국은 공공시설의 손상 사고를 줄이기 위해 지하 매핑을 확대하고 있으며, 프랑스는 군용 지구관측 위성에 자금을 지원하고 있습니다. 사우디아라비아의 ‘비전 2030’을 선도하는 중동 국가들에서는 모든 공공 서비스 포털에 지리공간 레이어가 통합되어 있습니다. 아프리카에서는 남아프리카공화국의 토지 소유권 개혁과 이집트의 관개 계획에서 진전이 나타나고 있습니다. 남미에서는 브라질이 INPE의 위성을 활용해 아마존의 산림 벌채를 감시하고 있으며, 아르헨티나에서는 정밀 농업 프로그램이 도입되고 있습니다. 이러한 노력들이 합쳐지면서 지리공간 분석 시장은 기존의 서유럽 국가들을 중심으로 한 범위를 넘어 확장되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the geospatial analytics market size is projected to expand from USD 93.52 billion in 2025 and USD 108.03 billion in 2026 to USD 196.59 billion by 2031, registering a CAGR of 12.72% between 2026 to 2031.
This report is Segmented by Component (Software, Services, and Hardware), Analysis Type (Surface Analysis, Network Analysis, and More), Deployment Model (On-Premises, and Cloud), End-User Vertical (Government, Defense and Intelligence, Natural Resources, Utility and Communication, Transportation and Logistics, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Geospatial Analytics Market Trends and Insights
Smart-City Program Adoption
Municipal agencies integrate spatial platforms into traffic control centers, energy grids, and emergency command rooms, making the geospatial analytics market central to urban resilience strategies. New York City's 2024 IoT Strategy requires every new infrastructure project to stream spatial metadata into a digital twin, enabling predictive maintenance of roads, bridges, and water pipes. The United Kingdom earmarked GBP 40 million (USD 51 million) for the National Underground Asset Register in 2025 to curb utility strikes, signaling a shift from pilot projects to city-wide rollouts. Subscription-based software is preferred over capital-intensive on-premises hardware because consumption-based pricing aligns with growth in sensor density. As a result, cloud vendors bundle mapping, routing, and real-time data streams, lowering entry barriers for mid-size cities. The geospatial analytics market, therefore, benefits from predictable municipal contracts that provide long-term revenue visibility.
Integration of 5G-Enabled Location Services
Sub-meter positioning derived from 5G carrier-phase measurements eliminates satellite dropouts in urban canyons. The 3GPP Release 17 specification introduced integrity metrics that unlock safety-critical autonomous-vehicle applications. Cisco expects 1.9 billion 5G devices to support location-based services by 2027. TomTom integrated 5G data into its HD Live Map, achieving lane-level accuracy without the need for roadside beacons. Lower battery drain and lower hardware costs are widening adoption beyond premium smartphones to wearables and industrial sensors. Consequently, the geospatial analytics market sees rising demand for APIs that fuse 5G positioning with satellite and inertial data to ensure ubiquitous coverage.
High Costs and Operational Complexity
Spatial data infrastructures often start at USD 50,000 per year for multi-user licenses, excluding consulting and data-acquisition fees. Skilled cartographers and remote-sensing engineers command premium salaries, which are scarce outside major metros. Raw satellite imagery requires radiometric calibration, atmospheric correction, and orthorectification. Each step consumes GPUs and storage that smaller firms struggle to afford. Budget overruns postpone returns on investment, slowing the diffusion of geospatial analytics market platforms among mid-tier enterprises.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of IoT-Derived Spatial Data
- Smallsat Constellations Enabling High-Revisit Imagery
- Legal and Privacy Hurdles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services revenue is projected to grow at a 13.37% CAGR between 2026 and 2031, even though software accounted for 41.32% of the geospatial analytics market share in 2025. Deloitte's consulting arm recorded 22% year-over-year growth in 2025 as clients sought turnkey climate-risk dashboards. Esri's containerized ArcGIS Enterprise 11.4 reduced infrastructure costs by 30% and extended software longevity. Managed platforms that fuse licensed algorithms with outsourced data engineering blur the boundary between software and services. Hardware lags because cloud GPU instances replace specialized on-premise workstations. The geospatial analytics market sees integrators bundling imagery subscriptions, machine-learning models, and data-pipeline maintenance, which accelerates adoption among organizations lacking in-house spatial expertise. Services, therefore, remain the catalyst that unlocks downstream software revenue, nurturing a virtuous cycle for vendors.
A growing share of contracts specifies outcome-based payments tied to yield improvement or fuel savings. This shift aligns vendor incentives with customer success, boosting retention rates. Open-source libraries such as GDAL and PostGIS lower entry barriers, yet clients still pay for customization and support. As integration complexity increases, advisory partners bundle change management workshops to ensure new analytics workflows are embedded in daily operations. Consequently, the geospatial analytics market will likely see deeper partnerships rather than one-off license deals through 2031.
In 2025, surface analysis accounted for 35.78% of the market, while network analysis is projected to grow at a CAGR of 13.54% through 2031. Last-mile logistics exploits dynamic routing to trim idle time; UPS saved 10 million gallons of fuel annually by minimizing left turns. Utilities simulate grid resilience to prioritize upgrades, while public-safety agencies test evacuation scenarios. Surface analysis dominates agriculture and mining, where slope and watersheds drive planting and blasting plans. The rise of augmented reality underpins steady growth in geovisualization, and Bentley's iTwin makes immersive 3D reviews mainstream in niche fields, while spatial statistics and geocoding power epidemiology and site-selection tasks. The geospatial analytics market thus diversifies across analysis types, but network algorithms tied to real-time data streams remain the fastest driver of return on investment.
Demand for multimodal logistics is driving vendors to merge road, rail, sea, and air networks into a unified graph. Combining edge constraints, such as bridge heights or hazardous-cargo rules, with historical travel times improves ETA accuracy. Developers increasingly call microservices over RESTful OGC API interfaces that abstract complex spatial joins. This approach accelerates deployment and keeps compute close to data, improving latency. As a result, organizations view network analysis as a business-critical capability rather than an optional add-on, propelling further share gains inside the geospatial analytics market.
Complete Report Scope:
- By Component
- Software
- Services
- Hardware
- By Analysis Type
- Surface Analysis
- Network Analysis
- Geovisualization
- Other Analysis Types
- By Deployment Model
- On-Premises
- Cloud
- By End-User Vertical
- Government
- Defense and Intelligence
- Agriculture
- Natural Resources
- Utility and Communication
- Transportation and Logistics
- Healthcare and Life Sciences
- Other End-User Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 35.92% of the geospatial analytics market share in 2025, anchored by defense procurement and mature smart-city deployments. The United States Joint All-Domain Command and Control program embeds location intelligence across services, while L3Harris supplied WESCAM MX-25 sensors for reconnaissance aircraft in 2024. Canada's federal open-data portal released topographic and cadastral layers in 2025, inviting commercial reuse. Mexico equips coastal states with digital twins for flood monitoring to accelerate disaster response. Growth slows as replacement cycles, not first-time deployments, dominate, yet artificial intelligence add-ons sustain incremental spending.
Asia-Pacific is forecast to register a 13.76% CAGR, the fastest regional pace, propelled by massive public-sector investments. China's BeiDou counted 1.5 billion active devices by 2025, permeating agriculture, ride-hailing, and emergency services. India operationalized its National Geospatial Policy in 2024, liberalizing access to high-resolution imagery and mandating spatial metadata across ministries, sparking private innovation. Japan allocated JPY 50 billion (USD 340 million) to 3D city models for disaster readiness. South Korea and Australia roll out smart-city pilots, while Southeast Asian nations modernize land registries and forestry monitoring. Cheaper imagery and wider smartphone penetration expand consumer location-based services, enlarging the geospatial analytics market base.
Europe's trajectory hinges on regulatory harmonization. The INSPIRE Directive drives cross-border data sharing, reducing friction for logistics and environmental apps. Germany's nationwide digital twin integrates infrastructure data for climate adaptation. The United Kingdom extends subsurface mapping to cut utility-strike incidents, while France funds military earth-observation satellites. Middle Eastern countries, led by Saudi Arabia's Vision 2030, embed geospatial layers across all public service portals. Africa sees progress in South Africa's land-tenure reforms and Egypt's irrigation planning. South America leverages Brazil's INPE satellites to police Amazon deforestation, and Argentina deploys precision-farming programs. These initiatives collectively expand the geospatial analytics market beyond its traditional Western core.
- Esri Inc.
- Hexagon AB
- Trimble Inc.
- Maxar Technologies Inc.
- Bentley Systems Inc.
- Fugro NV
- L3Harris Technologies Inc.
- Airbus Defence and Space GmbH
- MDA Ltd.
- Atkins PLC
- Intermap Technologies
- Oracle Corporation
- SAP SE
- Google LLC
- Amazon Web Services, Inc.
- Microsoft Corporation
- HERE Technologies
- TomTom NV
- CartoDB Inc.
- Precisely Holdings, LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Adoption of Smart-City Programs
- 4.2.2 Integration of 5G-Enabled Location Services
- 4.2.3 Proliferation of IoT-Derived Spatial Data
- 4.2.4 Smallsat Constellations Enabling High-Revisit Imagery
- 4.2.5 Hyper-Local ESG and Climate-Risk Analytics Demand
- 4.2.6 Real-Time Geofencing for Autonomous Operations
- 4.3 Market Restraints
- 4.3.1 High Costs and Operational Complexity
- 4.3.2 Legal and Privacy Hurdles
- 4.3.3 Data-Bias in AI-Driven Spatial Models
- 4.3.4 Interoperability Across Heterogeneous Standards
- 4.4 Industry Value Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.1.3 Hardware
- 5.2 By Analysis Type
- 5.2.1 Surface Analysis
- 5.2.2 Network Analysis
- 5.2.3 Geovisualization
- 5.2.4 Other Analysis Types
- 5.3 By Deployment Model
- 5.3.1 On-Premises
- 5.3.2 Cloud
- 5.4 By End-User Vertical
- 5.4.1 Government
- 5.4.2 Defense and Intelligence
- 5.4.3 Agriculture
- 5.4.4 Natural Resources
- 5.4.5 Utility and Communication
- 5.4.6 Transportation and Logistics
- 5.4.7 Healthcare and Life Sciences
- 5.4.8 Other End-User Verticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-Level Overview, Market-Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, Recent Developments)
- 6.4.1 Esri Inc.
- 6.4.2 Hexagon AB
- 6.4.3 Trimble Inc.
- 6.4.4 Maxar Technologies Inc.
- 6.4.5 Bentley Systems Inc.
- 6.4.6 Fugro NV
- 6.4.7 L3Harris Technologies Inc.
- 6.4.8 Airbus Defence and Space GmbH
- 6.4.9 MDA Ltd.
- 6.4.10 Atkins PLC
- 6.4.11 Intermap Technologies
- 6.4.12 Oracle Corporation
- 6.4.13 SAP SE
- 6.4.14 Google LLC
- 6.4.15 Amazon Web Services, Inc.
- 6.4.16 Microsoft Corporation
- 6.4.17 HERE Technologies
- 6.4.18 TomTom NV
- 6.4.19 CartoDB Inc.
- 6.4.20 Precisely Holdings, LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


