

|
시장보고서
상품코드
2120534
수산화알루미늄 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Aluminum Hydroxide - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 수산화알루미늄 시장 규모는 2026년에 201만 톤으로 추정되고 예측 기간(2026-2031년) CAGR 4.88%로 성장을 지속하여, 2031년까지 255만 톤에 이를 전망입니다.
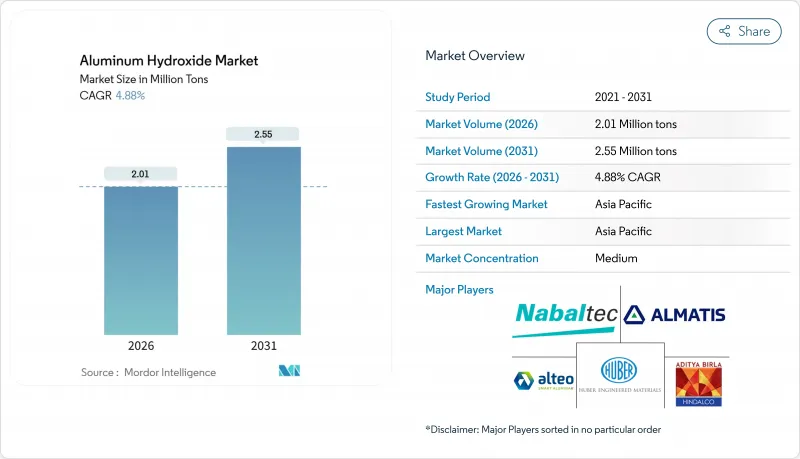
본 보고서는 제품 유형별(산업용, 의약품, 기타), 용도별(난연제·연기 억제제, 필러·안료, 제산제, 수처리용 화학물질, 촉매·기타), 최종 사용자 산업별(플라스틱 및 고무,의약품, CASE, 기타), 지역별(아시아태평양, 북미, 기타)로 분류되어 있습니다. 시장 예측은 수량(톤) 기준으로 제시되어 있습니다.
세계의 수산화알루미늄 시장 동향 및 인사이트
방화 규제로 인한 폴리올레핀계 케이블 컴파운드에서의 ATH 수요 증가
EU의 건설 제품 규정(EN 50575) 및 UL 94V-0 등 더욱 엄격해진 방화 안전 규제로 인해, 브롬계 첨가제에서 수산화알루미늄 삼수화물(ATH) 충전제로의 전환이 진행되고 있습니다. Teknor Apex의 ‘Halguard’ 저연기 케이블 컴파운드는 UL 2885에 따른 무할로겐 인증을 획득하여, 광물계 솔루션에 대한 수요가 증가하고 있음을 뒷받침하고 있습니다. 2025년 4월에 출시된 벤빅(Benvic)사의 ‘Linkflex HF’ 시리즈는 데이터센터 피복용으로 설계되어 내유성이 향상되었습니다. 운송 및 터널 설치 시, 180°C에서 수산화알루미늄이 방출하는 흡열성 물은 가연성 가스를 희석하고 기재를 냉각시키는 이점이 있습니다. 각 컴파운더 업체들은 클래스 B 난연 등급을 달성하기 위해 충전재의 배합 비율을 높이려고 하고 있지만, 그 결과 발생하는 높은 점도 때문에 이축 압출기의 도입이 필요합니다. 이는 남미의 소규모 사업자에게는 막대한 투자가 됩니다. 규제가 엄격해지는 가운데, 수산화알루미늄 시장은 전 세계 와이어 및 케이블 산업에서 꾸준한 성장이 예상됩니다.
EV용 배터리 케이스에서의 무할로겐 난연제 수요
열 폭주를 시뮬레이션하는 UNECE R-100 규격과 각 OEM의 독자적인 검사에 힘입어, 수산화알루미늄을 충전한 시트 성형 컴파운드(SMC)에 대한 수요가 급증하고 있습니다. 힌달코(Hindarko)는 마힌드라 일렉트릭(Mahindra Electric)에 알루미늄 배터리 케이스를 납품함으로써 그 생산량의 잠재력을 강조했습니다. 한편, 유럽의 고급차 모델에서는 언더바디 실드에 수산화알루미늄을 배합한 유리섬유 SMC를 우선적으로 채택하고 있습니다. 이는 순수 알루미늄에 비해 무게는 증가하지만, 150°C까지의 치수 안정성을 중시하기 때문입니다. 또한, 후버(Huber)사의 ‘마르티날(Martinal)’ 등급은 실란 처리가 되어 있어 흡습성을 저감합니다. 이러한 습기로 인한 경과 시간 후의 기계적 특성 유지는 전기차에 의무화된 8년 보증 기간과 부합합니다. 아시아에서는 중국의 셀 제조업체가 모듈 조립 공장을 자동차 공장 부지 내에 배치하여 현지 조달을 확보하고 있기 때문에 수산화알루미늄 시장은 더욱 활기를 띠고 있습니다.
보크사이트 공급 변동
2023년, 기니는 보크사이트를 수출했으며, 2025년까지 수출량이 증가했습니다. 그러나 캄사르 항구의 혼잡에 더해 몬순으로 인한 혼란까지 겹치면서 수출의 안정성이 훼손되고 있습니다. 이러한 예측 불가능성으로 인해 중국 바이어들은 비록 비용 증가를 감수해야 한다 하더라도 호주로 조달처를 전환할 수밖에 없는 상황에 처해 있습니다. 2024년, 보크사이트 현물 가격은 변동했습니다. 이러한 변동성은 연간 하류 계약에 묶여 있는 유럽의 수산화알루미늄 생산자들에게 압박을 가하고 있습니다. 한편, 리오 틴토(Rio Tinto)가 2024년에 고브(Gove) 제련소의 가동을 재개함에 따라, 유럽과 미국의 제련소에 대한 공급이 강화되었습니다. 그러나 해당 제련소는 에너지 비용과 인건비 급등으로 어려움을 겪고 있습니다. 그 결과, 수산화알루미늄 시장은 원료 가격의 급격한 변동에 취약해졌으며, 이로 인해 상당한 가격 변동이 발생하고 있습니다.
부문별 분석
2025년에는 플라스틱 및 고무 분야에서 비용 효율적인 난연 효과 덕분에 산업용 등급이 전체 수량의 65.12%를 차지했습니다. 케이블 제조업체들이 브롬계 첨가제를 광물계 충전제로 대체함에 따라, 알루미늄 수산화물 시장의 이 부문은 2031년까지 연평균 5.11%의 성장률을 보일 것으로 예측됩니다. 1-80 마이크로미터의 입자 직경을 아우르는 후버(Hoover)사의 ‘마르티날(Martinal)’ 시리즈 덕분에, 컨버터 각사는 현재 기계적 강도와 난연 성능의 균형을 맞출 수 있게 되었습니다. 입자 직경은 작지만, 의약품 등급 제품에는 가격 프리미엄이 책정되어 있습니다. 이는 USP(미국 약전)가 중금속에 대해 엄격한 제한을 두고 있어, 제산제 정제나 백신 보조제에 필수적인 순도가 확보되기 때문입니다. 200nm 이하의 특수한 나노 스케일 등급은 리튬 이온 배터리의 분리막 코팅에 활용되고 있습니다. 스미토모는 실적 향상을 목표로, NXA 시리즈를 통해 2025년도 매출 증가를 목표로 하고 있습니다. 한편, 정련소의 폐기물을 원료로 하는 재생 수산화알루미늄은 유럽의 순환형 경제 추진 노력과 부합하여 주목을 받고 있습니다.
UL 94V-0 규격 준수에 사용되는 충전재 배합을 실현하기 위해, 무할로겐 케이블 컴파운드에 대한 수요에 힘입어 산업 부문에서 수요는 증가 추세를 보이고 있습니다. 또한, 미세 등급 제품은 주조 폴리머 카운터탑의 불투명도를 높이고, 스테아르산 처리된 입자는 분체 도료의 유동성을 향상시키고 있습니다. 제약 부문에서는 고령화가 진행됨에 따라 고가의 양성자 펌프 억제제보다 OTC 의약품을 선택하는 사람이 늘어나고 있어 꾸준한 성장이 예상됩니다. 엄격한 초고순도 요건으로 인해 공급업체 수가 제한적이어서 이익률이 상승하고 있습니다. 특수 부문에는 수익성이 높은 기회가 있지만, 여전히 틈새 시장에 머물러 있습니다. 예를 들어, 나노 등급은 표준 산업용 소재에 비해 높은 가격에 거래되고 있지만, 광범위한 수산화알루미늄 시장 전체에서 그 취급량은 미미한 수준입니다.
지역별 분석
아시아태평양은 2025년 출하량의 54.22%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 5.23%를 기록할 전망입니다. 2023년, 중국은 보크사이트를 수입하여 저비용 알루미나 공장의 가동을 촉진했습니다. 이러한 전략적 조치로 인해 중국은 유럽의 경쟁사들보다 저렴한 가격에 수산화알루미늄을 수출할 수 있게 되었습니다. 한편, 인도에서는 농촌 지역에 정수 시설을 구축하는 야심 찬 ‘잘 지반 미션(Jal Jivan Mission)’이 추진되고 있으며, 이 사업은 황산알루미늄에 크게 의존하고 있어 그 전구체에 대한 안정적인 수요가 확보되고 있습니다. 일본에서는 인구의 상당 부분을 차지하는 고령층이 제산제의 안정적인 소비를 견인하고 있습니다. 동시에 한국의 주요 배터리 제조업체들은 열안정성의 이점을 이유로 분리막에 나노 등급의 수산화알루미늄을 채택하고 있습니다.
북미는 수산화알루미늄 시장에서 큰 점유율을 차지하고 있습니다. 후버(Hoover)사와 마틴 마리에타(Martin Marietta)사는 짧은 납기라는 강점을 활용하는 한편, 에너지 비용 급등으로 어려움을 겪고 있습니다. 유럽에서는 전력 비용으로 인한 제약에 직면해 있습니다. 이에 따라 나발테크(Navaltech)사는 가스가 풍부한 중동의 산업 집적지로 생산 능력을 이전하는 방안을 검토하고 있습니다. 남미와 중동 및 아프리카를 합친 시장 점유율은 전체 시장 규모에서 차지하는 비중이 비교적 작습니다. 브라질의 자동차 부품 및 사우디아라비아의 호텔·관광 관련 프로젝트가 성장을 견인하고 있지만, 두 지역 모두 알루미나 정제 능력의 한계로 인해 여전히 순수입국에 머물러 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the aluminum hydroxide market size is estimated at 2.01 million tons in 2026, and is expected to reach 2.55 million tons by 2031, at a CAGR of 4.88% during the forecast period (2026-2031).
This report is Segmented by Product Type (Industrial, Pharmaceuticals, and Others), Application (Flame-Retardant and Smoke-Suppressant, Filler and Pigment, Antacid, Water-Treatment Chemicals, and Catalyst and Others), End-User Industry (Plastics and Rubber, Pharmaceuticals, CASE, and Others), and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Aluminum Hydroxide Market Trends and Insights
Fire-Safety Regulations Driving ATH in Polyolefin Cable Compounds
Stricter fire-safety regulations, including the EU's Construction Products Regulation EN 50575 and UL 94 V-0, are driving a transition from brominated additives to aluminum trihydrate fillers. Teknor Apex's Halguard low-smoke cable formulations have secured halogen-free certification under UL 2885, underscoring the rising demand for mineral solutions. Launched in April 2025, Benvic's Linkflex HF series, designed for data-center sheathing, boasts enhanced oil resistance. In transit and tunnel installations, aluminum hydroxide's endothermic water release at 180 °C proves beneficial, diluting combustible gases and cooling substrates. While compounders are pushing filler loadings for Class B flame ratings, the resulting high viscosity necessitates twin-screw extruders - a costly investment for smaller players in South America. With tightening standards, the aluminum hydroxide market is poised for steady growth in the global wire-and-cable sector .
Halogen-Free Flame-Retardant Demand in EV Battery Enclosures
Demand for aluminum hydroxide-filled sheet-molding compounds is surging, driven by UNECE R-100 and proprietary OEM tests that simulate thermal runaway. Hindalco underscored the volume potential by delivering aluminum battery casings to Mahindra Electric. While premium European models prioritize glass-fiber SMCs infused with aluminum hydroxide for underbody shields - valuing dimensional stability up to 150 °C despite a mass penalty over bare aluminum - Huber's Martinal grades, treated with silane, mitigate moisture uptake. This preservation of mechanical properties post-humidity aging aligns with the eight-year warranties mandated for EVs. In Asia, the aluminum hydroxide market is further buoyed as Chinese cell manufacturers, by co-locating module assembly with vehicle plants, secure local supplies..
Bauxite-Supply Volatility
In 2023, Guinea exported bauxite, setting its sights on increased exports by 2025. However, port congestion at Kamsar, coupled with monsoon disruptions, has hampered export consistency. This unpredictability has nudged Chinese buyers to pivot towards Australia, even if it means shouldering higher costs. In 2024, spot bauxite prices fluctuated. This volatility has put pressure on European aluminum hydroxide producers, who are bound by annual downstream contracts. Meanwhile, Rio Tinto's 2024 revival of its Gove refinery bolsters supply for Western smelters. Yet, the refinery grapples with elevated energy and labor expenses. As a result, the aluminum hydroxide market finds itself vulnerable to raw material shocks, leading to pronounced price fluctuations.
Other drivers and restraints analyzed in the detailed report include:
- Rising OTC Antacid Consumption in Aging Economies
- Rapid Adoption of ATH in Solid-Surface Countertops
- Health Concerns on Chronic Aluminum Intake
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Industrial grade represented 65.12% of volume in 2025, owing to cost-effective flame retardancy in plastics and rubber. This slice of the aluminum hydroxide market is forecast to rise at 5.11% through 2031 as cable makers swap brominated additives for mineral fillers. Converters can now balance mechanical strength with flame performance, thanks to Huber's Martinal range, which spans from 1 to 80 µm. While smaller in size, the pharmaceutical-grade variant commands a price premium. This is due to USP's stringent limit on heavy metals, ensuring the purity essential for antacid tablets and vaccine adjuvants. Specialty nano-scale grades, measuring below 200 nm, are being utilized for lithium-ion separator coatings. In a bid to boost its financials, Sumitomo's NXA series is targeting a revenue increase in FY 2025. Meanwhile, reclaimed aluminum hydroxide, sourced from refinery waste, is making waves in Europe, aligning with the region's circular-economy aspirations.
Industrial demand is on the rise, driven by the need for halogen-free cable compounds to achieve filler loading for UL 94 V-0 compliance. Additionally, fine grades are enhancing opacity in cast-polymer countertops, and stearate-treated particles are improving flow in powder paints. The pharmaceutical sector is witnessing steady growth, as an aging population increasingly opts for OTC remedies over pricier proton-pump inhibitors. The stringent ultra-high-purity requirements are narrowing the supplier pool, thereby bolstering profit margins. While specialty segments present lucrative opportunities, they remain niche. For instance, nano grades are commanding a higher price compared to standard industrial material, yet their volumes are modest in the broader aluminum hydroxide market.
Complete Report Scope:
- By Product Type
- Industrial
- Pharmaceuticals
- Others (Specialty Nano Grade and Reclaimed / Recycled Grade)
- By Application
- Flame-Retardant and Smoke-Suppressant
- Filler and Pigment
- Antacid
- Water-Treatment Chemicals
- Catalyst and Others
- By End-User Industry
- Plastics and Rubber
- Pharmaceuticals
- Paints, Coatings, Adhesives and Sealants (CASE)
- Others (Paper and Others)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 54.22% of volume in 2025 and is set to post a 5.23% CAGR to 2031. In 2023, China imported bauxite, fueling its low-cost alumina plants. This strategic move allowed China to export aluminum hydroxide at prices lower than its European counterparts. Meanwhile, India's ambitious Jal Jeevan Mission, which is setting up rural water plants, is heavily reliant on aluminum sulfate, ensuring a steady demand for its precursor. In Japan, a significant portion of the population is seniors who drive consistent antacid consumption. At the same time, South Korea's leading battery manufacturers are opting for nano-grade aluminum hydroxide in their separators, citing its thermal stability benefits.
North America commands a significant share of the aluminum hydroxide market. While Huber and Martin Marietta capitalize on short lead times, they grapple with energy cost surges. Europe faces constraints due to power costs. This has led Nabaltec to contemplate shifting capacities to clusters in the gas-abundant Middle East. South America and the combined regions of the Middle East and Africa account for a smaller share of the market volume. While Brazil's automotive components and Saudi Arabia's hospitality projects drive growth, both regions still find themselves as net importers, hindered by limited alumina refining capabilities.
- Akrochem Corporation
- Almatis
- Alteo
- Aluminum Corporation of China Limited
- Hindalco Industries Ltd
- HONGHE CHEMICAL
- Huber Engineered Materials
- KC
- LKAB Minerals
- Martin Marietta Materials
- Nabaltec AG
- Nippon Light Metal Holdings Co., Ltd
- Resonac Holdings Corporation
- Sankyo Chemical Co. Ltd
- Sibelco
- Sumitomo Chemical Co. Ltd
- TOR Minerals
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Drivers
- 4.1.1 Fire-Safety Regulations Driving ATH in Polyolefin Cable Compounds
- 4.1.2 Halogen-Free Flame-Retardant Demand in EV Battery Enclosures
- 4.1.3 Rising OTC Antacid Consumption in Ageing Economies
- 4.1.4 Rapid Adoption of ATH in Solid-Surface Countertops
- 4.1.5 Water-Treatment Infrastructure Expansion in Emerging Nations
- 4.2 Market Restraints
- 4.2.1 Bauxite-Supply Volatility
- 4.2.2 Health Concerns on Chronic Aluminum Intake
- 4.2.3 High Energy Cost of Precipitated ATH Production
- 4.3 Value Chain Analysis
- 4.4 Porter's Five Forces
- 4.4.1 Bargaining Power of Suppliers
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Threat of New Entrants
- 4.4.4 Threat of Substitutes
- 4.4.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Industrial
- 5.1.2 Pharmaceuticals
- 5.1.3 Others (Specialty Nano Grade and Reclaimed / Recycled Grade)
- 5.2 By Application
- 5.2.1 Flame-Retardant and Smoke-Suppressant
- 5.2.2 Filler and Pigment
- 5.2.3 Antacid
- 5.2.4 Water-Treatment Chemicals
- 5.2.5 Catalyst and Others
- 5.3 By End-User Industry
- 5.3.1 Plastics and Rubber
- 5.3.2 Pharmaceuticals
- 5.3.3 Paints, Coatings, Adhesives and Sealants (CASE)
- 5.3.4 Others (Paper and Others)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global overview, Market overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Akrochem Corporation
- 6.4.2 Almatis
- 6.4.3 Alteo
- 6.4.4 Aluminum Corporation of China Limited
- 6.4.5 Hindalco Industries Ltd
- 6.4.6 HONGHE CHEMICAL
- 6.4.7 Huber Engineered Materials
- 6.4.8 KC
- 6.4.9 LKAB Minerals
- 6.4.10 Martin Marietta Materials
- 6.4.11 Nabaltec AG
- 6.4.12 Nippon Light Metal Holdings Co., Ltd
- 6.4.13 Resonac Holdings Corporation
- 6.4.14 Sankyo Chemical Co. Ltd
- 6.4.15 Sibelco
- 6.4.16 Sumitomo Chemical Co. Ltd
- 6.4.17 TOR Minerals
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


