

|
시장보고서
상품코드
2120553
북미의 혈행동태 모니터링 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America Hemodynamic Monitoring - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
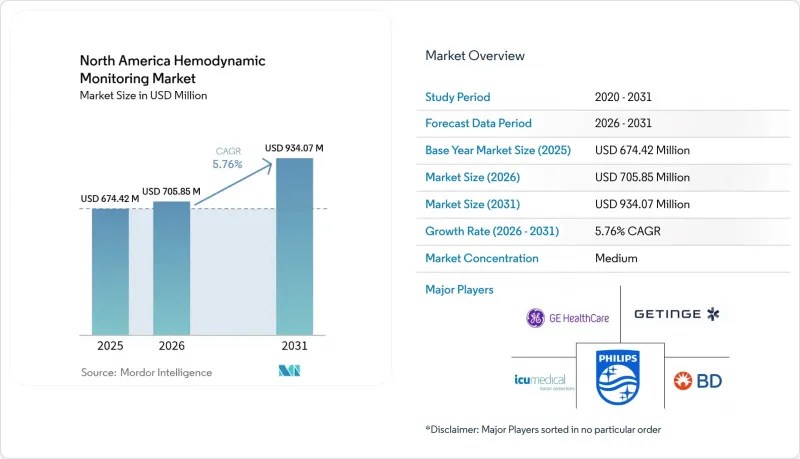
에 의하면, 북미의 혈행동태 모니터링 시장 규모는 2025년 6억 7,442만 달러로 평가되었습니다. 2026년에는 7억 585만 달러로 확대되어 2031년까지 9억 3,407만 달러에 이를 것으로 예측되며, 2026-2031년에 걸쳐 CAGR 5.76%로 성장할 전망입니다.
본 보고서는 제품 유형별(침습형, 저침습형, 비침습형 혈행동태 모니터링 시스템), 구성 요소별(모니터, 센서·트랜스듀서, 일회용 제품 및 부속품, 소프트웨어 플랫폼, 서비스), 용도별(심장 외과, 기타),모니터링 매개변수별(심박출량·파생 지표, 기타), 최종 사용자별(병원, 기타), 지역별(미국, 캐나다, 멕시코)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
북미의 혈행동태 모니터링 시장 동향 및 인사이트
심혈관 질환 및 응급 의료 사례 수 증가
2022년에는 미국에서 70만 2,880명이 심장 질환으로 사망했으며, 2024년에는 670만 명의 성인이 심부전을 앓고 있었습니다. 예측에 따르면, 2030년까지 그 수는 870만 명에 달할 것으로 보이며, 이로 인해 중환자실(ICU) 입원 기간이 장기화되면서 감염 위험 없이 며칠 동안 체내에 삽입해 둘 수 있는 센서에 대한 수요가 증가하고 있습니다. (1) 1시간 이내에 혈역학적 평가를 의무화하는 패혈증 지침으로 인해 중환자실의 부담이 더욱 가중되고 있으며, 펄스 컨투어 모니터 및 바이오리액턴스 모니터에 대한 수요가 급증하고 있습니다.
저침습 모니터링 기술의 발전
2025년에 승인된 4세대 FloTrac 알고리즘은 머신러닝을 통한 보정을 채택하여, 혈관 확장성 쇼크 시의 오차 범위를 축소합니다. 한편, 식도 도플러는 대수술 시 수액 요법의 지침으로 미국에서 승인되었습니다. 임상의들이 워크플로우 통합을 우선시하는 가운데, 센서와 클라우드 연결형 의사결정 지원 기능을 결합한 솔루션을 제공하는 벤더들이 독립형 하드웨어를 대체해 가고 있습니다.
첨단 시스템의 막대한 설비 투자 및 소모품 비용
완전 구성을 갖춘 HemoSphere 유닛의 가격은 3만 5,000-5만 달러이며, 20개 병상을 갖춘 중환자실(ICU)의 경우 소모품을 제외하더라도 최대 60만 달러의 투자가 필요할 수 있습니다. 소규모 병원에서는 이러한 지출을 정당화하기 어려운 반면, 멕시코의 IMSS는 ICU 병상 1개당 모든 모니터링 장비 예산으로 고작 1만 2,000달러만 책정하고 있습니다.
부문별 분석
2025년 매출의 44.56%를 저침습 시스템이 차지했습니다. 이는 폐동맥 카테터 삽입을 피하면서 심박마다 데이터를 제공하는 펄스 컨투어법과 식도 도플러 장치가 주를 이루고 있습니다. 그러나 텔레-중환자실(Tele-ICU) 모델에서는 동맥 라인이 필요 없는 센서가 선호되기 때문에 비침습형 플랫폼은 2031년까지 연평균 성장률(CAGR) 8.46%로 성장하고 있습니다. 이러한 추세를 바탕으로 북미의 비침습형 플랫폼을 활용한 혈행동태 모니터링 시장 규모는 꾸준히 확대될 것으로 예측됩니다. 개발 중인 웨어러블 패치는 동맥 라인을 통한 측정값과 높은 상관관계를 보이고 있으며, 향후 승인을 받게 되면 침습형 하드웨어의 병상 내 대체가 가속화될 것으로 시사됩니다.
북미의 혈행동태 모니터링 시장에서 침습성 카테터가 차지하는 점유율은 복잡한 심장 질환 사례에서 여전히 굳건하지만, 2024년 Cordella사의 폐동맥 센서가 FDA 승인을 받으면서 외래 환자 대상 혈행동태 모니터링의 유효성이 입증되었고,병상 모니터 공급업체들에 대해 재택 간호 기능에 필적하는 성능을 갖추도록 압력이 가해졌습니다. 클라우드 연결, 예측 분석, 소모품 최소화를 통합한 공급업체는 다음 조달 붐을 포착할 준비가 되어 있습니다.
2025년 구성 요소별 매출액 중 모니터가 34.72%를 차지했으나, 소프트웨어 및 데이터 관리 제품군은 연평균 성장률(CAGR) 9.25%로 확대되며 구성 요소 중 가장 빠른 성장 궤도를 그리고 있습니다. 병원 측은 저혈압 발생 15분 전에 임상의에게 경고를 발령하는 예측 알고리즘을 선택 사항이 아닌 필수 기능으로 간주하고 있으며, 이로 인해 구매 기준이 재정의되고 있습니다. 타사製の 패혈증 및 인공호흡기 분리 알고리즘을 통합할 수 있는 개방형 API는 플랫폼의 차별화를 도모하고 생태계의 정착을 촉진하고 있습니다.
센서와 일회용 제품은 여전히 경상 수익의 기반을 이루고 있지만, 병원들이 총소유비용(TCO)을 면밀히 검토함에 따라 가격에 대한 압박은 커지고 있습니다. 북미의 혈행동태 모니터링 시장에서 서비스에 기인한 시장 규모는 안정세를 유지하고 있습니다. 이는 모든 자본재 판매에 다년간의 유지보수 계약이 수반되기 때문입니다. 각 벤더사는 현재 정기적인 수익원을 확보하고 하드웨어의 상품화를 상쇄하기 위해 분석 소프트웨어 구독을 중시하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the North America hemodynamic monitoring market size is expected to increase from USD 674.42 million in 2025 to USD 705.85 million in 2026 and reach USD 934.07 million by 2031, growing at a CAGR of 5.76% over 2026-2031.
This report is Segmented by Product Type (Invasive, Minimally Invasive, Non-Invasive Systems), Component (Monitors, Sensors, Disposables, Software, Services), Application (Cardiac Surgery, and More), Monitoring Parameter (Cardiac Output, and More), End User (Hospitals, and More), and Geography (United States, Canada, Mexico). Market Forecasts are Provided in Value (USD).
North America Hemodynamic Monitoring Market Trends and Insights
Rising Cardiovascular & Critical-Care Caseload
Heart disease caused 702,880 U.S. deaths in 2022, and 6.7 million adults lived with heart failure in 2024; projections place the cohort at 8.7 million by 2030, extending ICU stays and favoring sensors that remain in-situ for days without infection risks.[1] Sepsis guidelines that mandate hemodynamic assessment within one hour further load ICUs, accelerating demand for pulse-contour and bioreactance monitors.
Advances in Minimally Invasive Monitoring Technologies
Fourth-generation FloTrac algorithms cleared in 2025 employ machine-learning corrections that narrow error margins during vasoplegic shock, while esophageal Doppler gained U.S. endorsement for guiding fluid therapy in major surgery. Vendors that bundle sensors with cloud-connected decision support are displacing standalone hardware as clinicians prioritize workflow integration.
High Capital & Consumable Costs
A fully configured HemoSphere unit costs USD 35,000-50,000, and a 20-bed ICU may invest up to USD 600,000 before disposables; smaller hospitals struggle to justify this outlay, while Mexico's IMSS budgets only USD 12,000 per ICU bed for all monitoring gear.
Other drivers and restraints analyzed in the detailed report include:
- Rapidly Growing Elderly Population
- Favorable U.S. Reimbursement Policies
- Procedure-Related Infection & Complication Risks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Minimally invasive systems held 44.56% of 2025 revenue, anchored by pulse-contour and esophageal Doppler devices that avoid pulmonary-artery catheterization while supplying beat-to-beat data. However, non-invasive platforms are growing at an 8.46% CAGR through 2031 as tele-ICU models favor sensors that work without arterial lines. The North America hemodynamic monitoring market size for non-invasive platforms is expected to expand steadily under this momentum. Wearable patches under development correlate strongly with arterial-line measurements, suggesting future clearance will accelerate bedside replacement of invasive hardware.
The North America hemodynamic monitoring market share commanded by invasive catheters persists in complex cardiac cases, yet FDA approval of the Cordella pulmonary-artery sensor in 2024 validated ambulatory hemodynamics and pressured bedside-monitor vendors to match home-care capabilities. Vendors that integrate cloud connectivity, predictive analytics, and minimal consumable requirements are positioned to capture the next wave of procurement.
Monitors delivered 34.72% of 2025 component revenue, but software and data-management suites are advancing at a 9.25% CAGR, the quickest component trajectory. Hospitals regard predictive algorithms that alert clinicians 15 minutes before hypotension as essential rather than optional, redefining purchasing criteria. Open APIs that welcome third-party sepsis or ventilator-weaning algorithms differentiate platforms and encourage ecosystem stickiness.
Sensors and disposables still underpin recurring revenue, yet price pressure mounts as hospitals scrutinize total cost of ownership. The North America hemodynamic monitoring market size attributed to services remains stable because multi-year maintenance contracts accompany every capital sale. Vendors now emphasize analytic-software subscriptions to lock in annuity streams and offset hardware commoditization.
Complete Report Scope:
- By Product Type
- Invasive Hemodynamic Monitoring Systems
- Catheters
- Pressure Transducers
- Consumables (pressure tubing, flush sets, etc.)
- Minimally-Invasive Hemodynamic Monitoring Systems
- Pulse-Contour Analysis Devices
- Esophageal Doppler Monitors
- Non-Invasive Hemodynamic Monitoring Systems
- Impedance/ Bioreactance Cardiology Systems
- Wearable Continuous-BP & CO Patch Sensors
- Invasive Hemodynamic Monitoring Systems
- By Component
- Monitors
- Sensors / Transducers
- Disposables & Accessories
- Software and Platforms
- Services
- By Application
- Cardiac Surgery
- General & Orthopedic Surgery
- Interventional Cardiology
- Trauma & Emergency Care
- Sepsis and Septic Shock Management
- By Monitoring Parameter
- Cardiac Output & Derived Indices (CI, SV, SVV, PPV)
- Continuous Blood Pressure (ART/NIBP)
- Volume Status / Fluid Responsiveness Metrics
- Tissue Oxygenation (StO2, rSO2)
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Home-Care Providers
- Specialty Cardiology & Critical-Care Clinics
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Baxter (Cheetah Medical)
- CNSystems Medizintechnik
- Deltex Medical
- Dragerwerk
- Edward Lifesciences
- GE Healthcare
- Getinge (Pulsion)
- ICU Medical
- Koninklijke Philips
- Lepu Medical
- LiDCO (Spacelabs)
- Masimo
- Mindray Bio-Medical
- Nihon Kohden
- Schwarzer Cardiotek
- Tensys Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Cardiovascular & Critical-Care Caseload
- 4.2.2 Advances in Minimally Invasive Monitoring Technologies
- 4.2.3 Rapidly Growing Elderly Population
- 4.2.4 Favorable U.S. Reimbursement for Invasive & Minimally Invasive Procedures
- 4.2.5 AI-Guided Fluid-Management Analytics Gaining Traction
- 4.2.6 Expansion of Tele-ICU Platforms Adopting Continuous Non-Invasive Monitors
- 4.3 Market Restraints
- 4.3.1 High Capital & Consumable Costs of Advanced Systems
- 4.3.2 Procedure-Related Infection & Complication Risks
- 4.3.3 Clinician Alarm-Fatigue & Waveform Data Overload
- 4.3.4 Shortage of Waveform-Interpretation-Skilled Critical-Care Nurses
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product Type
- 5.1.1 Invasive Hemodynamic Monitoring Systems
- 5.1.1.1 Catheters
- 5.1.1.2 Pressure Transducers
- 5.1.1.3 Consumables (pressure tubing, flush sets, etc.)
- 5.1.2 Minimally-Invasive Hemodynamic Monitoring Systems
- 5.1.2.1 Pulse-Contour Analysis Devices
- 5.1.2.2 Esophageal Doppler Monitors
- 5.1.3 Non-Invasive Hemodynamic Monitoring Systems
- 5.1.3.1 Impedance/ Bioreactance Cardiology Systems
- 5.1.3.2 Wearable Continuous-BP & CO Patch Sensors
- 5.1.1 Invasive Hemodynamic Monitoring Systems
- 5.2 By Component
- 5.2.1 Monitors
- 5.2.2 Sensors / Transducers
- 5.2.3 Disposables & Accessories
- 5.2.4 Software and Platforms
- 5.2.5 Services
- 5.3 By Application
- 5.3.1 Cardiac Surgery
- 5.3.2 General & Orthopedic Surgery
- 5.3.3 Interventional Cardiology
- 5.3.4 Trauma & Emergency Care
- 5.3.5 Sepsis and Septic Shock Management
- 5.4 By Monitoring Parameter
- 5.4.1 Cardiac Output & Derived Indices (CI, SV, SVV, PPV)
- 5.4.2 Continuous Blood Pressure (ART/NIBP)
- 5.4.3 Volume Status / Fluid Responsiveness Metrics
- 5.4.4 Tissue Oxygenation (StO2, rSO2)
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Ambulatory Surgical Centers
- 5.5.3 Home-Care Providers
- 5.5.4 Specialty Cardiology & Critical-Care Clinics
- 5.6 By Country
- 5.6.1 United States
- 5.6.2 Canada
- 5.6.3 Mexico
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Baxter (Cheetah Medical)
- 6.3.2 CNSystems Medizintechnik
- 6.3.3 Deltex Medical
- 6.3.4 Draegerwerk
- 6.3.5 Edwards Lifesciences
- 6.3.6 GE HealthCare
- 6.3.7 Getinge (Pulsion)
- 6.3.8 ICU Medical
- 6.3.9 Koninklijke Philips N.V.
- 6.3.10 Lepu Medical
- 6.3.11 LiDCO (Spacelabs)
- 6.3.12 Masimo Corporation
- 6.3.13 Mindray Bio-Medical
- 6.3.14 Nihon Kohden
- 6.3.15 Schwarzer Cardiotek
- 6.3.16 Tensys Medical
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


