

|
시장보고서
상품코드
2120680
튜브 포장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Tube Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
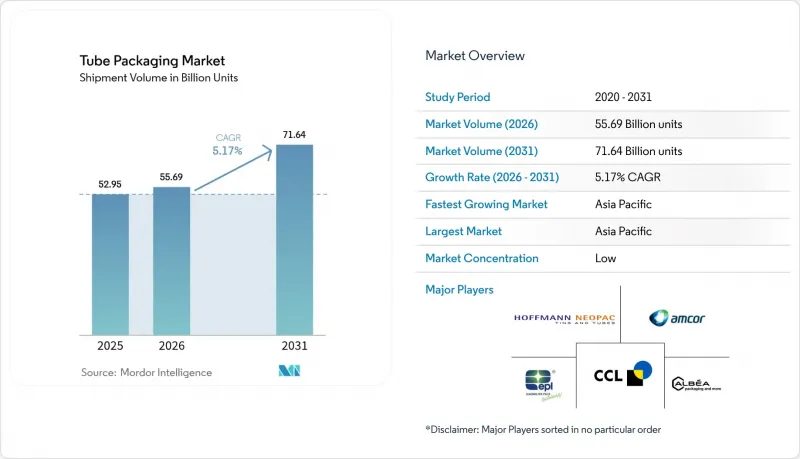
에 의하면, 2026년 튜브 포장 시장 규모는 556억 9,000만개로 추정되며, 2025년 529억 5,000만개에서 2031년에는 716억 4,000만개에 이를 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 5.17%를 기록할 전망입니다.
본 보고서는 제품 유형(플라스틱 튜브, 알루미늄 튜브, 라미네이트 튜브, 판지/바이오 튜브), 포장 유형(스퀴즈·접이식, 트위스트식), 최종 이용 산업(화장품 및 퍼스널케어,의약품, 식품, 기타 최종 이용 산업), 유통 채널(직접 판매, 간접 판매) 및 지역별로 분류되어 있습니다. 시장 예측은 수량(단위) 기준으로 제시되어 있습니다.
세계 튜브 포장 시장 동향 및 인사이트
퍼스널케어 및 화장품 분야 수요 증가
뷰티 브랜드들은 제품 라인의 프리미엄화를 지속하고 있으며, 이에 따라 민감한 배합을 보호하고 배출량을 조절할 수 있는 튜브가 선호되고 있습니다. 알베아(Albea)는 재활용 소재를 도입하는 동시에, 컨셉에서 출시까지의 주기를 단축하고, 2030년까지 탄소 배출량을 46% 감축한다는 목표를 추구하고 있습니다. 콜게이트(Colgate)의 ‘EveryDrop’ 코팅이 적용된 투명 PET 소재의 ‘엘릭서(Elixir)’ 튜브는 제품의 배출성을 향상시키고, 브랜드 충성도를 강화하는 사용자 경험의 개선을 두드러지게 보여줍니다. 원료의 출처 및 탄소 발자국에 대한 투명성도 향상되어, 환경 의식이 높은 소비자층에게 공감을 불러일으키는 마케팅 메시지를 뒷받침하고 있습니다.
지속 가능한 포장에 대한 소비자의 선호도 증가
유명한 구강 관리 브랜드는 복합 라미네이트 소재에서 영국의 일반 가정 쓰레기 수거 경로를 통해 배출 가능한, 완전히 재활용 가능한 고밀도 폴리에틸렌(HDPE) 포장재로 전환하고 있습니다. 네오팩(NeoPack)은 유럽 튜브 제조업체 중 최초로 ‘RecyClass EN 15343’ 인증을 획득하여 재활용 소재의 추적성을 입증함과 동시에 경쟁력을 강화했습니다. 이러한 획기적인 성과로 인해 지속가능성 준수가 시장 내 차별화 요인으로 자리 잡으면서, 튜브 포장 시장은 더 높은 부가가치를 지닌 혁신을 향해 나아가고 있습니다.
대체품의 보급
가볍고 개봉이 용이하며, 재료 사용량을 줄일 수 있는 스탠드업 파우치는 2029년까지 470억 달러 규모에 달할 것으로 예측되어, 소스 및 조미료 브랜드들이 튜브에서 멀어지게 하고 있습니다. MasterFoods사의 재활용 가능한 종이 일회용 팩은 대체 포장 형태가 지속가능성과 분량 관리라는 우선순위를 어떻게 충족시킬 수 있는지를 더욱 잘 보여줍니다. 이러한 혁신으로 인해 튜브 제조업체들은 판매량 감소를 막기 위해 정확한 분량 조절이나 높은 산소 차단성과 같은 기능적 강점을 강조할 수밖에 없게 되었습니다.
부문 분석
2025년, 튜브 포장 시장 점유율의 62.53%를 플라스틱 포장재가 차지했습니다. 이는 비용 효율이 뛰어난 압출 성형 라인과 브랜드에 대한 보편적인 인지도에 힘입은 결과입니다. 플라스틱 중에서도 고밀도 폴리에틸렌(HDPE)과 폴리프로필렌(PP)은 크림에서 젤에 이르기까지 다양한 점도에 대응하여 업계 전반에 걸친 범용성을 확보하고 있습니다. 폴리머 층과 알루미늄 층을 적층한 라미네이트 소재는 풍미 유지가 필수적인 구강 관리 제품을 지속적으로 보호하고 있습니다. 알루미늄 튜브는 틈새 시장이지만, 휘발성이 높은 원료의약품이나 산소에 민감한 식품을 보존하여 고가 시장에서의 입지를 공고히 하고 있습니다.
한편, PPWR(플라스틱 대체 추진)에 따라 재생 가능한 소재로의 전환이 가속화되는 가운데, 판지 및 바이오 솔루션은 연평균 성장률(CAGR) 8.58%를 기록하며 튜브 포장 시장 전체를 웃도는 성장세를 보이고 있습니다. 후타마키(Futamaki)사의 ‘OmniLock Ultra’ 배리어지는 알루미늄과 동등한 보호 성능을 발휘하면서도 가정용 쓰레기로 재활용이 가능합니다. 암콜(Amcol)의 특허를 취득한 ‘AmFiber Performance Paper’ 역시 식품 및 헬스케어 분야를 타겟으로 하고 있으며, 섬유 기반 구조로도 엄격한 수분 제한을 충족할 수 있음을 입증하고 있습니다. 채용이 확대됨에 따라 플라스틱은 규모의 우위를 유지할 것으로 보이지만, 절대적인 출하량에서의 선두 위치는 축소될 것으로 예측됩니다.
2025년 출하량 중 스퀴즈 튜브 및 접이식 튜브가 66.72%를 차지하고 있으며, 한 손으로 쉽게 짜낼 수 있다는 점에 대한 소비자의 강력한 지지를 반영하여 연평균 성장률(CAGR) 4.91%로 증가할 것으로 예측됩니다. 충격 압출 성형된 알루미늄 튜브는 피부과용 크림에서 공기 혼입을 완벽하게 방지하는 반면, 공압출 성형된 플라스틱 튜브는 경량화를 도모하고 그래픽 디자인의 매력을 높입니다. 라미네이트 가공된 스퀴즈 튜브는 향미 유지 성능이 뛰어나 구강 관리 분야의 표준으로 자리 잡고 있습니다.
트위스트 방식이나 정밀 도포기를 갖춘 디자인은 투여량의 정확성이 최우선으로 요구되는 처방용 피부과 제품이나 고급 화장품 분야에서 특별한 역할을 수행하고 있습니다. 인몰드 라벨(IML)이 적용된 폴리프로필렌 튜브와 같은 혁신 기술은 장식과 구조를 하나의 공정으로 통합하여 생산 라인의 효율성과 재활용성을 향상시키고 있습니다. 폭넓은 밀봉 및 장식 옵션을 통해 스퀴즈식 패키지의 적응성은 유지되며, 튜브 포장 시장에서 그 선도적인 입지를 공고히 하고 있습니다.
지역별 분석
아시아태평양은 2025년에 수량 점유율 35.38%로 튜브 포장 시장을 주도할 것이며, 2031년까지 연평균 성장률(CAGR) 5.74%로 확대될 것으로 예측됩니다. 중국과 인도의 일용소비재(FMCG)의 견조한 성장, 가처분 소득 증가, 도시형 라이프스타일이 여행에 편리한 개인 위생 용품 및 1회용 조미료에 대한 수요를 뒷받침하고 있습니다. 2026년까지 35억 달러의 매출을 예상하는 베트남의 종이 포장 분야는 섬유 기반 포장에 대한 지역적 성장세를 보여주고 있습니다.
북미와 유럽은 성숙한 시장이지만, 더욱 엄격한 재활용 목표를 충족해야 하므로 조달 전략과 자본 배분을 재검토해야 하는 상황에 직면해 있습니다. EU의 PPWR(플라스틱 포장 재활용 지침)에 따라 가공업체들은 단일 소재 제품을 생산할 수 있도록 생산 라인을 개조해야만 하며, 수년에 걸친 대규모 개조에 자금을 투입할 수 있는 통합형 대기업들이 유리한 입장에 있습니다. 미국과 캐나다에서는 각 브랜드사의 탄소 배출 감축 노력을 배경으로, 지역 소매점에서 재활용률이 높은 튜브를 시범적으로 도입하는 파일럿 프로그램이 진행되고 있습니다.
라틴아메리카와 중동은 중산층 인구 증가가 가공식품 시장의 성장을 뒷받침하고 있어, 새로운 기회가 창출되는 지역으로 주목받고 있습니다. 브라질의 포장 식품 시장은 2028년까지 1,686억 달러에 달할 전망이며, 이에 따라 1회분씩 소분된 소스나 향미 페이스트에 대한 수요가 증가하고 있습니다. 동시에, ALPLA가 태국, 아프리카 및 걸프협력회의(GCC) 국가들에 공장을 운영하고 있다는 점은 수입 관세와 물류 비용이 부담이 되는 시장에서 현지 공급이 전략적으로 중요함을 보여줍니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, tube packaging market size in 2026 is estimated at 55.69 billion units, growing from 2025 value of 52.95 billion units with 2031 projections showing 71.64 billion units, growing at 5.17% CAGR over 2026-2031.
This report is Segmented by Product Type (Plastics Tubes, Aluminum Tubes, Laminated Tubes, Paperboard/Bio-Based Tubes), Packaging Type (Squeeze and Collapsible, Twist), End-Use Industry (Cosmetics and Personal Care, Pharmaceutical, Food, Other End-Use Industry), Distribution Channel (Direct Sales, Indirect Sales), and Geography. The Market Forecasts are Provided in Terms of Volume (Units).
Global Tube Packaging Market Trends and Insights
Rising Demand in Personal Care and Cosmetics
Beauty brands continue to premiumize product lines, which favors tubes that protect sensitive formulations and allow controlled dispensing. Albea has trimmed concept-to-launch cycles while integrating recycled content, pursuing a 46% carbon-reduction target for 2030. Colgate's clear PET Elixir tube with EveryDrop coating improves product evacuation, underscoring user experience gains that strengthen brand loyalty. Visibility into material provenance and carbon footprint is also improving, supporting marketing narratives that resonate with eco-conscious shoppers.
Growing Consumer Preferences for Sustainable Packaging
Household-name oral care brands have shifted from composite laminates toward fully recyclable high-density polyethylene formats that can enter mainstream kerbside streams in the United Kingdom. Neopac became the first European tube maker to earn RecyClass EN 15343 certification, validating traceable recycled content and strengthening its competitive edge. Such milestones convert sustainability compliance into market differentiation, pushing the tube packaging market toward higher-value innovations.
Availability of Substitutes
Stand-up pouches, which combine light weight, easy opening, and reduced material use, are projected to hit USD 47 billion by 2029, drawing sauce and condiment brands away from tubes. MasterFoods' recyclable paper single-dose pack further illustrates how alternate formats can satisfy sustainability and portion-control priorities. These innovations pressure tube producers to highlight functional strengths, such as precise dosing and high oxygen barrier, to prevent volume erosion.
Other drivers and restraints analyzed in the detailed report include:
- Recyclability Mandates Boosting Mono-material Tubes
- Rising Demand for Convenience and Versatility
- Raw Material Shortages and Fluctuating Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastic formats accounted for 62.53% of tube packaging market share in 2025, supported by cost-efficient extrusion lines and universal brand familiarity. Within plastics, high-density polyethylene and polypropylene accommodate diverse viscosities, from creams to gels, ensuring cross-industry versatility. Laminates that stack polymer and aluminum layers continue to protect oral-care formulas where flavor retention is essential. Aluminum tubes, though niche, preserve volatile pharmaceutical actives and oxygen-sensitive foods, reinforcing a premium-priced foothold.
Paperboard and bio-based solutions, however, outpace the broader tube packaging market at an 8.58% CAGR as the PPWR accelerates the shift toward renewable substrates. Huhtamaki's OmniLock Ultra barrier paper delivers aluminum-like protection while remaining curbside-recyclable. Amcor's patented AmFiber Performance Paper similarly targets food and healthcare segments, proving that fiber-based structures can satisfy strict moisture limits. As adoption widens, plastic's volume lead is expected to narrow in absolute terms, even if it retains scale advantages.
Squeeze and collapsible tubes represented 66.72% of 2025 shipments and are projected to rise at a 4.91% CAGR, reflecting strong consumer affinity for one-handed dispensing. Impact-extruded aluminum versions ensure zero air ingress for dermatological creams, whereas co-extruded plastic variants lower weight and enhance graphic appeal. Laminated squeeze tubes remain the oral-care standard because of flavor-barrier proficiency.
Twist and precision-applicator designs fill specialized roles in prescription dermatology and luxury cosmetics where dosage accuracy is paramount. Innovations such as in-mold-label polypropylene tubes merge decoration and structure in a single step, improving line efficiency and recyclability. The breadth of sealing and decoration options keeps squeeze formats adaptable, cementing their lead in the tube packaging market.
Complete Report Scope:
- By Product Type
- Plastics Tubes
- Polyethylene (PE) Tubes
- Polypropylene (PP) Tubes
- Other Plastic Tubes
- Aluminum Tubes
- Laminated tubes
- Paperboard/Bio- Based tubes
- Plastics Tubes
- By Packaging Type
- Squeeze and Collapsible
- Twist
- By End-Use Industry
- Cosmetics and Personal Care
- Pharmaceutical
- Food
- Other End-use Industry
- By Distribution Channel
- Direct Sales
- Indirect Sales
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific led the tube packaging market in 2025 with a 35.38% volume share and is expected to advance at 5.74% CAGR through 2031. Robust FMCG expansion in China and India, higher disposable income, and urban lifestyles underpin demand for travel-friendly personal care items and single-serve condiments. Vietnam's paper segment, on course for USD 3.5 billion revenue by 2026, illustrates regional momentum toward fiber-based packaging.
North America and Europe, while mature, are navigating stricter recycling targets that reshape sourcing strategies and capital allocation. The EU PPWR compels converters to retrofit lines for mono-material output, favoring integrated giants able to fund multi-year overhauls. In the United States and Canada, brand commitments to carbon reduction drive pilot programs that test high-recycled-content tubes at regional retailers.
Latin America and the Middle East are emerging opportunity zones as rising middle-class populations fuel packaged food growth. Brazil's packaged-food market could reach USD 168.6 billion by 2028, spurring demand for portion-controlled sauces and flavored pastes. Concurrently, ALPLA's facility roll-outs in Thailand, Africa, and the Gulf Cooperation Council underline the strategic importance of local supply in markets where import duties and logistics add cost layers.
- Amcor plc
- EPL Limited
- Albea Group
- Hoffmann Neopac AG
- CCL Industries Corp.
- Tubex Aluminium Tubes
- Huhtamaki Oyj
- Montebello Packaging
- LINHARDT Group GmbH
- CTLpack Group, S.L.U.
- Plastube Inc.
- Unette Corporation
- Scandolara S.p.A.
- Alltub Deutschland GmbH
- TUBETTIFICIO PERFEKTUP S.r.l.
- AptarGroup Inc.
- Witoplast Kisielinscy Joint Stock Company
- Mpack Poland Sp. z.o.o.
- Viva Healthcare Packaging
- Gp Plast Sp. z..o.o.
- EPL Poland Sp. z.o.o.
- Elpes sp. z.o. o.
- ALPLA WERKE ALWIN LEHNER GMBH and CO KG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand in Personal Care and Cosmetics
- 4.2.2 Growing consumer preferences for sustainable Packaging
- 4.2.3 Recyclability mandates boosting mono-material tubes
- 4.2.4 Rising Demand for Convenience and Versatility
- 4.2.5 Global FMCG CAPEX push into hybrid-barrier technologies
- 4.3 Market Restraints
- 4.3.1 Availability of Substitutes
- 4.3.2 Raw Material Shortages and Fluctuating cost
- 4.3.3 Limited Product Compatibility Restricting Market Penetration
- 4.4 Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Raw Material Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Product Type
- 5.1.1 Plastics Tubes
- 5.1.1.1 Polyethylene (PE) Tubes
- 5.1.1.2 Polypropylene (PP) Tubes
- 5.1.1.3 Other Plastic Tubes
- 5.1.2 Aluminum Tubes
- 5.1.3 Laminated tubes
- 5.1.4 Paperboard/Bio- Based tubes
- 5.1.1 Plastics Tubes
- 5.2 By Packaging Type
- 5.2.1 Squeeze and Collapsible
- 5.2.2 Twist
- 5.3 By End-Use Industry
- 5.3.1 Cosmetics and Personal Care
- 5.3.2 Pharmaceutical
- 5.3.3 Food
- 5.3.4 Other End-use Industry
- 5.4 By Distribution Channel
- 5.4.1 Direct Sales
- 5.4.2 Indirect Sales
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia and New Zealand
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 United Arab Emirates
- 5.5.4.1.2 Saudi Arabia
- 5.5.4.1.3 Turkey
- 5.5.4.1.4 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Nigeria
- 5.5.4.2.3 Egypt
- 5.5.4.2.4 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 EPL Limited
- 6.4.3 Albea Group
- 6.4.4 Hoffmann Neopac AG
- 6.4.5 CCL Industries Corp.
- 6.4.6 Tubex Aluminium Tubes
- 6.4.7 Huhtamaki Oyj
- 6.4.8 Montebello Packaging
- 6.4.9 LINHARDT Group GmbH
- 6.4.10 CTLpack Group, S.L.U.
- 6.4.11 Plastube Inc.
- 6.4.12 Unette Corporation
- 6.4.13 Scandolara S.p.A.
- 6.4.14 Alltub Deutschland GmbH
- 6.4.15 TUBETTIFICIO PERFEKTUP S.r.l.
- 6.4.16 AptarGroup Inc.
- 6.4.17 Witoplast Kisielinscy Joint Stock Company
- 6.4.18 Mpack Poland Sp. z.o.o.
- 6.4.19 Viva Healthcare Packaging
- 6.4.20 Gp Plast Sp. z..o.o.
- 6.4.21 EPL Poland Sp. z.o.o.
- 6.4.22 Elpes sp. z.o. o.
- 6.4.23 ALPLA WERKE ALWIN LEHNER GMBH and CO KG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


