

|
시장보고서
상품코드
2120695
의료 클라우드 기반 분석 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Global Healthcare Cloud Based Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
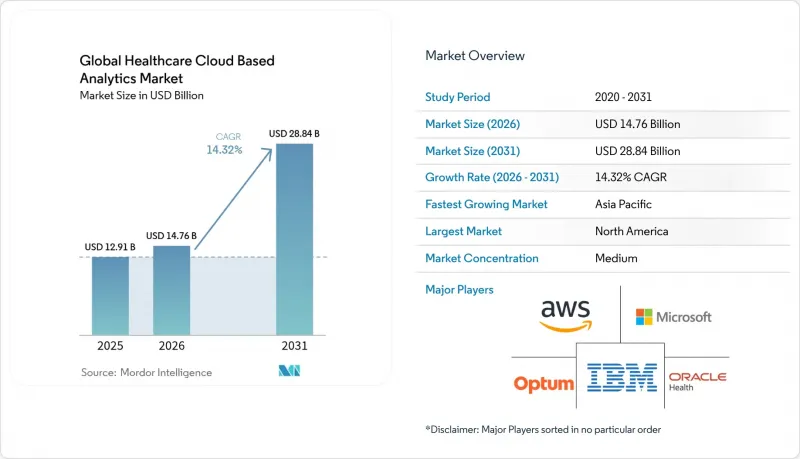
의료 클라우드 기반 분석 시장 규모는 2025년 129억 1,000만 달러로 평가되었습니다. 2026년에는 147억 6,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 14.32%로 성장을 지속하여, 2031년에는 288억 4,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 기술 유형(예측 분석, 처방 분석 등), 용도(임상 데이터, 관리 데이터 등), 구성 요소(하드웨어 등), 도입 모델(퍼블릭, 프라이빗 등), 최종 사용자(의료 제공업체, 보험사 등), 지역(북미, 유럽 등)별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 의료 클라우드 기반 분석 시장 동향 및 인사이트
디지털 의료 기록에 따른 데이터의 폭발적 증가
현재 미국의 거의 모든 병원(96%)과 외래 진료 의사의 4분의 3 이상(78%)이 인증을 받은 전자건강기록(EHR) 시스템을 도입하고 있습니다. 구조화, 반구조화, 비구조화 정보의 홍수는 기존 서버를 압도하는 한편, 텍스트,이미지, 파형, 스트리밍 원격 측정 데이터를 분석하는 클라우드 호스팅형 분석 엔진에 대한 수요를 촉진하고 있습니다. 자연어 처리를 통해 의사의 소견이 실용적인 데이터로 변환되는 한편, 머신러닝 파이프라인은 재입원 방지 및 인력 배치 최적화에 도움이 되는 패턴을 밝혀냅니다. 유전체 프로파일, 웨어러블 기기의 측정값, 사회적 결정 요인을 통합함으로써 의료 제공업체는 정밀의료 및 지역사회 전체를 대상으로 한 개입의 기반이 되는 상세한 환자 프로파일을 구축하고 있습니다.
가치 기반 의료 보상으로의 전환
메디케어·메디케이드 서비스 센터(CMS)에 따르면, 2030년까지 모든 메디케어 수혜자가 가치 기반 모델에 따른 의료 서비스를 받게 될 예정이며, 이는 양보다 질을 중시하는 전환입니다. 따라서 의료 제공업체는 비용을 절감하기 위해 실시간 코호트 시각화, 위험 점수 산정 및 예측 알림이 필요합니다. 선도적인 지불 제도에 참여하고 있는 기관들은 분석에 기반한 시기적절한 개입을 통해 이미 연간 지출을 2,800만 달러 절감하고 있으며, 클라우드의 확장성이 가져다주는 재정적 이점이 부각되고 있습니다. 유럽에서 책임 의료(Accountable Care) 참여가 확대됨에 따라, 공공 및 민간을 불문하고 지속적인 성과 추적이 필수적입니다.
뿌리 깊은 데이터 개인정보 보호 및 사이버 보안 위협
2024년, 의료 업계에서는 677건의 중대한 정보 유출 사고가 발생하여 1억 8,240만 명이 영향을 받았습니다. 여기에는 1억 건의 환자 기록이 유출된 랜섬웨어 사건도 포함됩니다. 정보 유출로 인한 평균 비용은 977만 달러에 달하며, 의료 서비스 제공업체들은 암호화, 제로 트러스트 아키텍처, 연중무휴 24시간 모니터링에 막대한 투자를 해야 하는 상황에 처해 있습니다. 많은 조직에서는 여전히 사내 전문 지식이 부족하여 조달 주기가 길어지고 있으며, 이로 인해 의료 분야의 클라우드 기반 분석 시장 성장세가 다소 둔화되고 있습니다.
부문별 분석
2025년, 의료 클라우드 기반 분석 시장에서 예측 도구가 40.35%를 차지했습니다. 이는 재입원, 패혈증 발병 및 인력 배치 수요를 사전에 파악하고자 하는 의료 제공업체들의 강력한 요구를 여실히 보여줍니다. 이러한 솔루션은 시간 경과에 따른 전자건강기록(EHR), 실시간 생체 신호, 사회경제적 지표를 통합하여 품질 점수를 향상시키고 비용을 절감하는 예방적 치료 경로를 활성화합니다. 통합 대시보드는 다학제 팀에 고위험 환자를 알리고 응급 의료 이용을 줄여줍니다.
처방형(Prescriptive) 엔진은 아직 발전 단계에 있지만, 2031년까지 연평균 성장률(CAGR) 15.62%라는 가장 빠른 속도로 확대되고 있습니다. 이러한 플랫폼은 투약 계획이나 수술실 처리 용량에 관한 ‘만약 -라면’ 시나리오를 시뮬레이션하여 최적의 개입 방안을 권장합니다. 의사결정 최적화는 가치 기반 계약 하에서 지속적인 이익률 개선을 추구하는 의료 시스템의 지지를 받고 있으며, 처방형 모듈은 차기 성장의 선구자로 자리매김하고 있습니다.
임상 분석은 2025년 의료용 클라우드 기반 분석 시장 점유율의 45.08%를 차지했습니다. 이는 병상에서의 의사결정 지원, 영상 진단 선별, 약물 상호작용 분석이 환자에게 가시적인 이점을 제공하기 때문입니다. 딥러닝 알고리즘은 방사선 진단 소요 시간을 단축하고 미세한 병변을 감지하는 한편, 항생제 적정 사용에 관한 실시간 대시보드는 약물 내성 추세를 억제합니다.
연평균 성장률(CAGR) 16.88%로 확대되고 있는 집단건강관리 플랫폼은 보험 청구 데이터, 약국 데이터, 사회적 요구 데이터를 통합하여 위험을 계층화하고 지역 사회에 대한 개입을 조정합니다. 정액제 모델이 보급됨에 따라 보험사 및 의료 제공업체는 코호트 수준의 지표를 활용하여 치료의 격차를 파악하고 있습니다. 수백만 명의 피보험자를 대상으로 수천 개의 변수를 처리할 때 클라우드의 확장성은 필수적임이 입증되었습니다.
지역별 분석
북미는 거의 모든 시설에서 전자 건강 기록(EHR)이 보급되고, 만성 질환 관리 코드에 대한 넉넉한 환급, 그리고 상호 운용성을 위한 연방 정부의 적극적인 추진에 힘입어 매출 1위를 유지하고 있습니다. 분석 워크로드 전체를 하이퍼스케일러로 이전한 의료 시스템에서는 최대 95%의 비용 절감과, 진료 기록을 자동으로 생성하는 AI 시범 프로젝트의 가속화가 보고되고 있습니다. 사이버 사고는 여전히 상존하는 위협으로, 제로 트러스트 프레임워크에 대한 광범위한 투자를 촉진하는 동시에 의료용 클라우드 기반 분석 시장의 벤더 선정 기준에도 영향을 미치고 있습니다.
유럽에서는 ‘유럽 헬스 데이터 스페이스(EHDS)’가 국경을 초월한 의료 기록의 이식성과 조사 목적의 재사용을 의무화하고 있어, 견조한 두 자릿수 성장을 기록하고 있습니다. 독일의 C5나 프랑스의 HDS와 같은 각국 고유의 규제로 인해, 데이터 레지던시를 확보하는 프라이빗 클라우드 및 하이브리드 전략이 촉진되고 있습니다. 각국의 보건부는 인력 부족 해소를 위해 디지털 전환 보조금을 배분하고 있으며, 이로 인해 클라우드 벤더와 공공 기관 간의 협력이 더욱 긴밀해지고 있습니다. 통합 의료 지역에서는 페더레이티드 러닝 모델을 활용하여 원본 이미지를 외부로 전송하지 않고 공동 암 검진 알고리즘을 실행함으로써, 개인정보 보호 감독 기관의 요건을 충족하면서 분석 능력을 확대되고 있습니다.
아시아태평양은 중국의 인터넷 의료 붐과 동남아시아의 급성장하는 원격의료 부문에 힘입어 가장 빠른 발전을 이루고 있습니다. 일본, 한국, 싱가포르의 정부 프로그램은 고령화와 의료 인력 부족에 대처하기 위해 병원의 클라우드 전환 및 임상 AI 시범 사업에 대한 보조금을 제공합니다. 전문의 수가 제한적인 국가들에서는 영상 검사 데이터를 원격지의 방사선과 전문의에게 전송하는 원격 판독 솔루션을 도입하여 진단 접근성을 개선하고 있습니다. 지역 기술 대기업들의 활발한 투자는 현지 워크플로우와 언어적 뉘앙스에 맞춘 분석 솔루션을 제공하는 역동적인 파트너십 생태계를 조성하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the healthcare cloud-based analytics market size is expected to grow from USD 12.91 billion in 2025 to USD 14.76 billion in 2026 and is forecast to reach USD 28.84 billion by 2031 at 14.32% CAGR over 2026-2031.
This report is Segmented by Technology Type (Predictive, Prescriptive and More), Application (Clinical Data, Administrative Data, and More), Component (Hardware, and More), Deployment Model (Public, Private, and More), End-User (Healthcare Providers, Payers, and More), and Geography (North America, Europe, and More). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Healthcare Cloud Based Analytics Market Trends and Insights
Data Explosion from Digital Health Records
Nearly every U.S. hospital (96%) and more than three-quarters of ambulatory physicians (78%) now run certified electronic health record (EHR) systems. The torrent of structured, semi-structured, and unstructured information overwhelms legacy servers yet fuels demand for cloud-hosted analytic engines that sift text, images, waveforms, and streaming telemetry. Natural-language processing converts physician notes into usable data, while machine-learning pipelines uncover patterns that inform readmission prevention and staffing optimization. By blending genomic profiles, wearable metrics, and social determinants, providers compose granular patient portraits that underpin precision medicine and community-wide interventions.
Transition To Value-Based Care Reimbursement
As per the Centers for Medicare & Medicaid Services, all Medicare beneficiaries are slated to receive care under value-based models by 2030, a shift that rewards quality over volume.Providers, therefore, require real-time cohort visibility, risk scoring, and predictive alerts to avoid costs. Organizations participating in advanced payment arrangements have already shaved USD 28 million from annual spending through timely analytics-driven interventions, underscoring the fiscal upside of cloud scalability. As accountable-care participation widens in Europe, continual performance tracking becomes indispensable for both public and private systems.
Persistent Data Privacy and Cyber Security Threats
Healthcare recorded 677 major breaches affecting 182.4 million people in 2024, including the ransomware incident that compromised 100 million patient records. Average breach costs reached USD 9.77 million, pressuring providers to invest heavily in encryption, zero-trust architecture, and 24/7 monitoring. Many organizations still lack in-house expertise, prolonging procurement cycles and slightly dampening the healthcare cloud-based analytics market momentum.
Other drivers and restraints analyzed in the detailed report include:
- Cost Efficiency and Elasticity of Cloud Infrastructure
- Government Mandates for Healthcare Interoperability Standards
- Legacy Infrastructure and Integration Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Predictive tools accounted for 40.35% of the healthcare cloud-based analytics market in 2025, highlighting provider appetite for foresight into readmissions, sepsis onset, and staffing needs. Solutions ingest longitudinal EHR records, real-time vitals, and socio-economic markers to trigger proactive care pathways that lift quality scores and compress costs. Integrated dashboards alert multidisciplinary teams to high-risk patients, reducing emergency utilization.
Prescriptive engines, though still nascent, are scaling fastest at a 15.62% CAGR through 2031. These platforms simulate "what-if" scenarios across medication regimens or operating-room throughput and recommend optimal interventions. Decision optimization resonates with health systems seeking continuous margin improvement under value-based contracts, positioning prescriptive modules as the next growth frontier.
Clinical analytics captured 45.08% of the 2025 healthcare cloud-based analytics market share because bedside decision support, imaging triage, and drug interactions deliver visible patient benefits. Deep-learning algorithms shorten radiology turnaround times and subtle pathologies, while real-time antimicrobial-stewardship dashboards curb resistance trends.
Population health platforms, expanding at 16.88% CAGR, aggregate claims, pharmacy, and social-needs data to stratify risk and orchestrate community interventions. As capitated payment models proliferate, payers and providers rely on cohort-level metrics to pinpoint gaps in care. Cloud scalability proves vital when crunching thousands of variables across millions of covered lives.
Complete Report Scope:
- By Technology Type
- Predictive Analytics
- Prescriptive Analytics
- Descriptive Analytics
- By Application
- Clinical Analytics
- Administrative & Financial Analytics
- Population Health & Research Analytics
- Real-World Evidence & Pharmacovigilance
- By Component
- Hardware
- Software
- Services
- By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
- By End-user
- Healthcare Providers
- Payers
- Life-Science & CROs
- Public Health Agencies
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retains the leading revenue position, supported by near-universal EHR penetration, generous reimbursement for chronic-care management codes, and aggressive federal pushes for interoperability. Health systems shifting entire analytics workloads to hyperscalers report up to 95% cost savings and accelerated AI pilots that automatically draft progress notes. Cyber incidents remain an ever-present hazard, prompting widespread investment in zero-trust frameworks and influencing vendor selection criteria for the healthcare cloud-based analytics market.
Europe records solid double-digit growth as the European Health Data Space mandates cross-border record portability and research reuse. Country-specific rules, such as Germany's C5 and France's HDS, spur private-cloud or hybrid strategies that assure data residency. Health ministries allocate digital-transformation grants to tame workforce shortages, tightening cooperation between cloud vendors and public agencies. Integrated health regions leverage federated-learning models to run joint cancer-screening algorithms without exporting raw images, satisfying privacy watchdogs while expanding analytic prowess.
Asia Pacific exhibits the fastest trajectory, propelled by China's internet-health boom and Southeast Asia's burgeoning telehealth sector. Government programs in Japan, South Korea, and Singapore subsidize hospital cloud migration and clinical AI pilots to counter aging populations and clinician scarcity. Countries with limited specialist availability deploy remote-read solutions that route imaging studies to off-site radiologists, improving diagnostic reach. Investment momentum from regional technology giants fosters vibrant partnership ecosystems that tailor analytics offerings to local workflows and language nuances.
- Oracle
- Optum
- IBM (Merative)
- Microsoft
- Amazon Web Services
- Google Cloud Platform
- Allscripts (Veradigm)
- SAS Institute
- CitiusTech
- Health Catalyst
- Koninklijke Philips
- HP Enterprise
- Snowflake Inc.
- MedeAnalytics
- Verisk Health
- Mckesson
- Inovalon
- Flatiron Health
- IQVIA Analytics
- Arcadia IO
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Data Explosion From Digital Health Records
- 4.2.2 Transition To Value Based Care Reimbursement
- 4.2.3 Cost Efficiency And Elasticity Of Cloud Infrastructure
- 4.2.4 Government Mandates For Healthcare Interoperability Standards
- 4.2.5 Telehealth Expansion Generating Continuous Patient Data Streams
- 4.2.6 Adoption Of Fhir And Open Api Ecosystems Enabling Cross Provider Analytics
- 4.3 Market Restraints
- 4.3.1 Persistent Data Privacy And Cyber Security Threats
- 4.3.2 Legacy Infrastructure And Integration Complexity
- 4.3.3 Shortage Of Cloud Native Healthcare Data Talent
- 4.3.4 Emerging Data Sovereignty And Carbon Footprint Regulations
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Technology Type
- 5.1.1 Predictive Analytics
- 5.1.2 Prescriptive Analytics
- 5.1.3 Descriptive Analytics
- 5.2 By Application
- 5.2.1 Clinical Analytics
- 5.2.2 Administrative & Financial Analytics
- 5.2.3 Population Health & Research Analytics
- 5.2.4 Real-World Evidence & Pharmacovigilance
- 5.3 By Component
- 5.3.1 Hardware
- 5.3.2 Software
- 5.3.3 Services
- 5.4 By Deployment Model
- 5.4.1 Public Cloud
- 5.4.2 Private Cloud
- 5.4.3 Hybrid Cloud
- 5.5 By End-user
- 5.5.1 Healthcare Providers
- 5.5.2 Payers
- 5.5.3 Life-Science & CROs
- 5.5.4 Public Health Agencies
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Oracle (Cerner)
- 6.3.2 Optum
- 6.3.3 IBM (Merative)
- 6.3.4 Microsoft
- 6.3.5 Amazon Web Services
- 6.3.6 Google Cloud Platform
- 6.3.7 Allscripts (Veradigm)
- 6.3.8 SAS Institute
- 6.3.9 CitiusTech
- 6.3.10 Health Catalyst
- 6.3.11 Philips Healthcare
- 6.3.12 HP Enterprise
- 6.3.13 Snowflake Inc.
- 6.3.14 MedeAnalytics
- 6.3.15 Verisk Health
- 6.3.16 McKesson
- 6.3.17 Inovalon
- 6.3.18 Flatiron Health
- 6.3.19 IQVIA Analytics
- 6.3.20 Arcadia IO
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


