

|
시장보고서
상품코드
2120813
전문 클라우드 서비스 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Professional Cloud Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 전문·클라우드 서비스 시장 규모는 2026년에 310억 7,000만 달러로 추정되며, 예측 기간(2026년-2031년)에 CAGR 8.74%로 성장을 지속하여 2031년에는 472억 3,000만 달러에 이를 전망입니다.
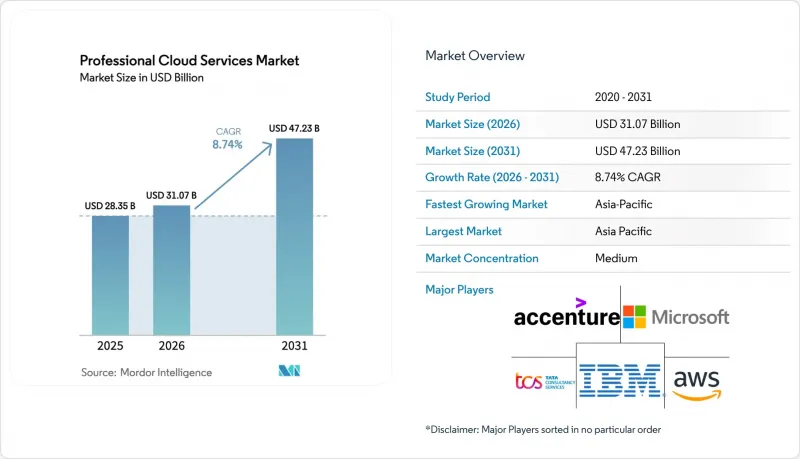
본 보고서는 도입 형태(퍼블릭, 프라이빗, 하이브리드), 서비스 모델(SaaS(Software as a Service), PaaS(Platform as a Service) 등), 최종 사용자 산업(정부·공공 부문, 은행 및 금융 서비스·보험 등), 조직 규모(대기업, 중소기업) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(미 달러) 기준으로 제시되어 있습니다.
세계 전문 클라우드 서비스 시장 동향 및 인사이트
하이퍼스케일러의 가격 대비 성능 향상으로 클라우드 전환 가속화
커스텀 실리콘을 통해 트랜잭션당 연산 비용이 약 3분의 1로 감소함에 따라, 기업들은 배치 워크로드조차도 퍼블릭 리전으로 이전하도록 유도되고 있습니다. AWS Graviton4, Azure Maia 100, Google Cloud TPU v5는 모두 2024년부터 2025년에 걸쳐 출시되어 성능을 향상시키는 동시에 월간 총 청구액을 절감하고, 마이그레이션 투자 회수 기간을 3년에서 18개월 미만으로 단축하고 있습니다. 가격 투명성과 투자 회수 기간 단축으로 인해 제조 및 물류 등 기존에 클라우드 도입이 늦어졌던 비용에 민감한 업종에서 전문적인 클라우드 서비스 시장이 확대되고 있습니다.
생성형 AI 워크로드의 급증으로 전문적인 클라우드 노하우가 필요해지고 있습니다.
대규모 언어 모델의 훈련 및 추론에는 고대역폭 네트워크, 저지연 스토리지, 그리고 탄력적인 클러스터가 필요하지만, 이는 대부분의 기업 데이터센터에서는 제공할 수 없습니다. OpenAI의 GPT-4는 2024년에 약 2만 5,000대의 GPU를 소비했으며, Anthropic의 Claude 3는 2025년에 멀티모달 입력을 추가했습니다. 이로 인해 기업들은 벡터 데이터베이스, 프롬프트 엔지니어링 도구, 관리형 모델 호스팅을 묶은 턴키 플랫폼으로의 전환을 가속화하고 있습니다. 이러한 스택을 통합하고 운영할 수 있는 통합 업체들은 고액의 컨설팅 비용을 청구하고 있으며, 이는 전문 클라우드 서비스 시장의 성장세를 더욱 부추기고 있습니다.
고급 클라우드 전문 분야의 인력 부족
2025년에는 클라우드 FinOps 엔지니어에 대한 수요가 전년 대비 85% 증가한 반면, 공급은 22% 증가에 그쳐 구조적인 기술 격차가 발생했으며, 북미에서는 멀티 클라우드 아키텍트의 연봉이 20만 달러를 넘는 수준으로 치솟았습니다. 인재 확보에 어려움을 겪는 기업들은 외부 컨설턴트에 크게 의존하고 있으며, 그 결과 전문 클라우드 서비스 시장 전체에서 비용이 증가하고 프로젝트 일정이 장기화되고 있습니다.
부문 분석
2025년 매출 중 하이브리드 구축이 43%를 차지하고 있으며, 이는 기업들이 기존 설비 투자를 유지하면서 퍼블릭 클라우드의 확장성을 활용하고자 하는 의향을 뒷받침합니다. 한편, 퍼블릭 클라우드는 비용 투명성과 변동형 요금 체계가 신규 도입 기업을 끌어들이고 있어, 전문 클라우드 서비스 시장 내에서 가장 높은 연평균 성장률(CAGR) 9.02%를 기록하며 성장할 전망입니다. 프라이빗 클라우드는 은행이나 정부 기관 등 규제가 엄격한 분야에서 여전히 지지를 받고 있지만, 하이퍼스케일러가 제공하는 분리 테넌트 옵션으로 인해 그 점유율은 점차 축소되고 있습니다.
쿠버네티스(Kubernetes)는 워크로드의 이식성을 높임으로써 도입 모델 간의 격차를 해소하고 있습니다. 2025년, 클라우드 네이티브 컴퓨팅 재단(CNCF)의 보고서에 따르면, 기업의 78%가 프로덕션 환경에서 쿠버네티스를 운영하고 있으며, 이로 인해 기업들은 비용 및 성능 측면에서 프라이빗 클라우드와 퍼블릭 클라우드 간에 용도를 마이그레이션하고 있습니다. 이러한 이식성 덕분에 인프라의 상품화가 진행되고 있으며, 경쟁은 관리형 데이터베이스나 AI 플랫폼과 같은 부가가치가 높은 서비스로 이동하고 있습니다. 이러한 서비스들은 현재 전문 클라우드 서비스 시장에서 결정적인 요소가 되고 있습니다.
2025년 기준으로 인프라스트럭처-어즈-어-서비스(IaaS)는 시장 점유율의 35%를 차지했습니다. 이는 계산 부하가 높은 워크로드에는 여전히 세밀한 제어가 필요하기 때문입니다. 소프트웨어 서비스(SaaS)는 벤더가 업계 워크플로를 사전 통합된 제품군으로 패키지화하여 도입 기간을 수개월에서 수주로 단축하고 있기 때문에 연평균 성장률(CAGR) 9.31%로 가장 빠른 성장이 예상됩니다. Salesforce, Microsoft Dynamics, Oracle Fusion은 현재 생성형 AI 기능을 통합하여, 고객이 기반 인프라를 관리할 필요 없이 성과를 제공합니다.
AI의 부상으로 서비스 모델의 경계가 재정의되고 있습니다. 훈련에는 IaaS 수준의 GPU 클러스터가 필요하지만, 배포 단계에서는 사전 훈련된 모델을 번들로 제공하는 SaaS 서비스가 선호됩니다. OpenAI의 ‘ChatGPT Enterprise’는 턴키 방식의 대화형 AI를 제공하면서도 인프라 관련 과제를 하이퍼스케일러에 맡김으로써 이러한 양면성을 여실히 보여주고 있습니다. 전문가용 클라우드 서비스 시장이 성숙해짐에 따라, 기술 스택의 깊이와 수직 통합형 기능을 겸비한 벤더가 지속 가능한 성장을 위해 가장 유리한 입지에 있다고 할 수 있습니다.
지역별 분석
아시아태평양은 2025년에 전문 클라우드 서비스 시장 점유율의 28.3%를 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 8.93%로 확대될 것으로 전망됩니다. 인도, 인도네시아, 베트남에서의 디지털 전환 추진에 더해, 중국이 국내 하이퍼스케일러의 우위를 확립하려는 움직임이 맞물리면서 해당 지역 수요가 확대되고 있습니다. 인도의 ‘디지털 인디아(Digital India)’ 이니셔티브에서는 퍼블릭 클라우드 조달에 100억 달러가 배정되어 있으며, 이는 도입의 기반이 되어 민간 기업으로도 파급되고 있습니다.
북미는 여전히 주요 시장이지만, 기업들이 새로운 워크로드를 이전하기보다는 기존 환경의 최적화에 주력하고 있어 성장은 둔화되고 있습니다. 미국에서는 FedRAMP 프로그램의 엄격한 인증 일정으로 인해 승인된 공급업체의 수가 제한되어 연방 정부 부문에서의 확장이 둔화되고 있습니다. 캐나다의 ‘개인정보 보호 및 전자문서법(PIPEDA)’은 기업들을 국내 데이터센터로 유도하고 있지만, 국경을 넘는 협업 도구에 대해서는 여전히 하이퍼스케일러의 거점 확장이 활용되고 있습니다.
Gaia-X와 각국의 데이터 현지화 정책에 힘입은 유럽의 ‘주권 클라우드’ 추진은 지역 시장의 분열을 초래하고 있습니다. AWS는 현지 규정 준수 요건을 충족하기 위해 2025년에 ‘European Sovereign Cloud’를 도입했으나, 프랑스와 독일의 전략은 국내 공급자를 우선시하고 있어 비용 상승과 서비스 범위 축소를 초래하고 있습니다. 한편, 영국은 보다 현실적인 입장을 취하며, 보안 기준을 충족하는 것을 조건으로 하이퍼스케일러 시장 진입을 허용하고 있습니다.
중동 및 아프리카에서는 공공 부문을 우선시하는 방향성이 제시되고 있습니다. 사우디아라비아의 ‘비전 2030’에서는 디지털 인프라에 64억 달러가 배정되었으며, 하이퍼스케일러의 거점이 사우디아라비아에 진출하는 파트너십이 촉진되고 있습니다. 아랍에미리트(UAE)와 남아프리카공화국은 기밀성이 높은 워크로드를 국내 데이터센터로 유도하는 데이터 보호법을 시행하고 있습니다. 아프리카 전역에서 나이지리아의 2024년 클라우드 지침은 정부가 앞장서서 모범을 보일 의지를 보여주고 있습니다.
남미의 전망은 천차만별입니다. 브라질의 통화 약세와 아르헨티나의 3자리 수에 달하는 인플레이션으로 인해 달러 표시 서비스 비용이 상승하면서 단기적인 도입이 주춤하고 있습니다. 그럼에도 불구하고, 전자상거래의 확대와 핀테크 혁신이 이 지역 내 전문 클라우드 서비스 시장 침투율을 점진적으로 높이는 데 기여하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, the professional cloud services market size is estimated at USD 31.07 billion in 2026, and is expected to reach USD 47.23 billion by 2031, at a CAGR of 8.74% during the forecast period (2026-2031).
This report is Segmented by Type of Deployment (Public, Private, and Hybrid), Service Model (Software As A Service, Platform As A Service, and More), End-User Industry (Government and Public Sector, Banking Finance Services and Insurance, and More), Organization Size (Large Enterprises, and Small and Medium Enterprises), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Professional Cloud Services Market Trends and Insights
Hyperscaler Price-Performance Gains Accelerate Cloud Migration
Custom silicon is reducing compute cost per transaction by roughly one-third, encouraging enterprises to move even batch workloads into public regions. AWS Graviton4, Azure Maia 100, and Google Cloud TPU v5 all launched in 2024-2025, improving performance while lowering total monthly bills and cutting the payback period for migrations from three years to under 18 months. Price visibility and quicker returns are expanding the professional cloud services market among cost-sensitive verticals, such as manufacturing and logistics, where cloud adoption has historically lagged.
Generative AI Workload Surge Demands Specialized Cloud Expertise
Training and inference for large language models require high-bandwidth networking, low-latency storage, and elastic clusters that most corporate data centers cannot supply. OpenAI's GPT-4 consumed about 25,000 GPUs in 2024, while Anthropic's Claude 3 added multimodal inputs in 2025, driving enterprises toward turnkey platforms that bundle vector databases, prompt-engineering tools, and managed model hosting. Integrators capable of orchestrating these stacks are commanding premium consulting rates, adding momentum to the professional cloud services market.
Talent Shortage in Advanced Cloud Specializations
While demand for cloud FinOps engineers rose 85% year-over-year in 2025, supply grew only 22%, creating a structural skills gap and inflating salaries for multi-cloud architects above USD 200,000 in North America. Enterprises struggling to recruit talent rely heavily on external consultants, adding cost and stretching project timelines across the professional cloud services market.
Other drivers and restraints analyzed in the detailed report include:
- Sovereign-Cloud Mandates Fragment Global Scale
- Edge-to-Cloud Integration Enables Low-Latency Applications
- Escalating Egress and Inter-Cloud Transfer Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hybrid deployments accounted for 43% of 2025 revenue, underscoring enterprises' wish to preserve existing capital investments while tapping public elasticity. Public cloud, however, is poised to advance at a 9.02% CAGR, the fastest within the professional cloud services market, as cost transparency and variable pricing attract new adopters. Private cloud retains traction in strictly regulated sectors such as banking and government, though its share is slowly eroding thanks to isolated tenancy options offered by hyperscalers.
Kubernetes is leveling the differences among deployment models by making workloads portable. In 2025 the Cloud Native Computing Foundation reported that 78% of enterprises ran Kubernetes in production, leading firms to shift applications between private and public clouds based on cost and performance considerations. This portability is commoditizing infrastructure and pushing competition into higher-value services like managed databases and AI platforms, elements now decisive in the professional cloud services market.
Infrastructure as a Service held 35% of the market share in 2025 because compute-intensive workloads still need granular control. Software as a Service is expected to grow the fastest, at a 9.31% CAGR, as vendors package industry workflows into pre-integrated suites, shortening deployment from months to weeks. Salesforce, Microsoft Dynamics, and Oracle Fusion now embed generative AI features, delivering outcomes without clients managing the underlying infrastructure.
The rise of AI is redrawing service-model boundaries. Training requires IaaS-level GPU clusters, whereas deployment favors SaaS offerings that bundle pre-trained models. OpenAI's ChatGPT Enterprise illustrates this duality by providing turnkey conversational AI while delegating infrastructure concerns to hyperscalers. As the professional cloud services market matures, vendors that combine stack depth with vertical functionality are best positioned for sustained growth.
Complete Report Scope:
- By Type of Deployment
- Public
- Private
- Hybrid
- By Service Model
- Software as a Service (SaaS)
- Platform as a Service (PaaS)
- Infrastructure as a Service (IaaS)
- By End-User Industry
- Government and Public Sector
- Healthcare
- Banking, Finance, Services and Insurance (BFSI)
- Retail
- IT and Telecommunications
- Media and Entertainment
- Other End-User Industries
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific held 28.3% of the professional cloud services market share in 2025 and is projected to rise at an 8.93% CAGR through 2031. Digital-transformation mandates in India, Indonesia, and Vietnam, together with China's drive for domestic hyperscaler dominance, are widening regional demand. India's Digital India initiative earmarked USD 10 billion for public cloud procurement, anchoring adoption that spills over into private enterprise.
North America remains a major market, but growth is moderating as enterprises optimize existing estates rather than migrate new workloads. In the United States, the FedRAMP program's rigorous certification timeline limits the number of authorized providers, slowing federal-sector expansion. Canada's Personal Information Protection and Electronic Documents Act steers enterprises toward local data centers, but cross-border collaboration tools still benefit from hyperscaler footprints.
Europe's sovereign-cloud ambitions, led by Gaia-X and national data-localization policies, are fragmenting the regional market. AWS introduced its European Sovereign Cloud in 2025 to address local compliance demands, while French and German strategies privilege domestic providers, raising costs and narrowing service breadth. The United Kingdom adopted a more pragmatic stance, allowing hyperscaler participation provided security standards are met.
The Middle East and Africa are following a public-sector-first trajectory. Saudi Arabia's Vision 2030 allocated USD 6.4 billion to digital infrastructure, triggering partnerships that bring hyperscaler regions into the kingdom. The United Arab Emirates and South Africa enforce data-protection laws that steer sensitive workloads to in-country data centers. Across Africa, Nigeria's 2024 cloud guidelines signal government willingness to lead by example.
South America's outlook is mixed. Currency depreciation in Brazil and triple-digit inflation in Argentina raise the cost of dollar-denominated services, slowing near-term adoption. Nonetheless, e-commerce expansion and fintech innovation underpin a gradual increase in regional professional cloud services market penetration.
- Accenture plc
- Amazon Web Services, Inc.
- Microsoft Corporation
- IBM Corporation
- Alphabet Inc. (Google Cloud)
- Deloitte Touche Tohmatsu Limited
- Tata Consultancy Services Limited
- Infosys Limited
- Capgemini SE
- Wipro Limited
- HCL Technologies Limited
- Cognizant Technology Solutions Corporation
- Rackspace Technology, Inc.
- Oracle Corporation
- Alibaba Group Holding Limited (Alibaba Cloud)
- Salesforce, Inc.
- SAP SE
- NTT DATA Corporation
- Huawei Technologies Co., Ltd.
- Google Professional Services, LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Hyperscaler Price-Performance Gains Accelerate Cloud Migration
- 4.2.2 Generative AI Workload Surge Demands Specialized Cloud Expertise
- 4.2.3 Shift to Outcome-Based Service-as-a-Software Contracts
- 4.2.4 Sovereign-Cloud Mandates in Europe and Asia-Pacific
- 4.2.5 Edge-to-Cloud Integration for Low-Latency Applications
- 4.2.6 Cloud FinOps Tools Drive Spend Transparency and Adoption
- 4.3 Market Restraints
- 4.3.1 Talent Shortage in Advanced Cloud Specializations
- 4.3.2 Escalating Egress and Inter-Cloud Transfer Costs
- 4.3.3 Fragmented Regional Compliance Frameworks
- 4.3.4 Inflation-Driven Opex Scrutiny in SME Segment
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value / Supply-Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Type of Deployment
- 5.1.1 Public
- 5.1.2 Private
- 5.1.3 Hybrid
- 5.2 By Service Model
- 5.2.1 Software as a Service (SaaS)
- 5.2.2 Platform as a Service (PaaS)
- 5.2.3 Infrastructure as a Service (IaaS)
- 5.3 By End-User Industry
- 5.3.1 Government and Public Sector
- 5.3.2 Healthcare
- 5.3.3 Banking, Finance, Services and Insurance (BFSI)
- 5.3.4 Retail
- 5.3.5 IT and Telecommunications
- 5.3.6 Media and Entertainment
- 5.3.7 Other End-User Industries
- 5.4 By Organization Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Medium Enterprises
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Egypt
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 Amazon Web Services, Inc.
- 6.4.3 Microsoft Corporation
- 6.4.4 IBM Corporation
- 6.4.5 Alphabet Inc. (Google Cloud)
- 6.4.6 Deloitte Touche Tohmatsu Limited
- 6.4.7 Tata Consultancy Services Limited
- 6.4.8 Infosys Limited
- 6.4.9 Capgemini SE
- 6.4.10 Wipro Limited
- 6.4.11 HCL Technologies Limited
- 6.4.12 Cognizant Technology Solutions Corporation
- 6.4.13 Rackspace Technology, Inc.
- 6.4.14 Oracle Corporation
- 6.4.15 Alibaba Group Holding Limited (Alibaba Cloud)
- 6.4.16 Salesforce, Inc.
- 6.4.17 SAP SE
- 6.4.18 NTT DATA Corporation
- 6.4.19 Huawei Technologies Co., Ltd.
- 6.4.20 Google Professional Services, LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


