

|
시장보고서
상품코드
2121495
특수 기능성 고분자 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Specialty Polymers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
특수 기능성 고분자 시장 규모는 2025년 1,551억 1,000만 달러에서 2026년에는 1,576억 4,000만 달러로 확대되고, 2031년까지 1,709억 1,000만 달러에 달할 것으로 예상되며, 2026년부터 2031년까지 CAGR 1.63%로 성장할 전망입니다.
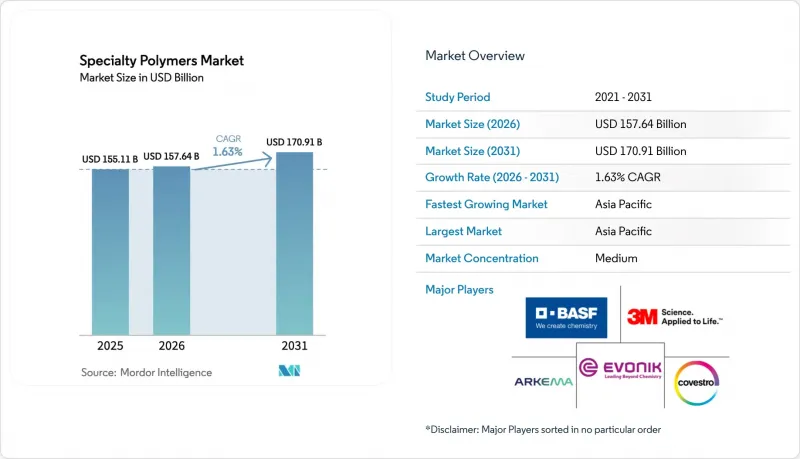
본 보고서는 종류별(특수 엘라스토머, 특수 복합재료, 특수 열가소성 수지, 특수 열경화성 수지, 기타), 최종사용자 산업별(자동차·운송, 소비재, 건축·건설 등), 및 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 특수 기능성 고분자 시장의 동향 및 인사이트
자동차 및 항공우주 분야의 경량화 수요
연비 및 배기가스 규제가 강화됨에 따라, 자동차 제조사 및 항공기 OEM 각사는 충돌 성능을 저해하지 않으면서 질량을 30-50% 절감할 수 있는 구조용 탄소섬유 복합재료나 유리섬유 강화 열가소성 플라스틱으로 강철이나 알루미늄을 대체함으로써 경량화를 추진하고 있습니다. 보잉사의 복합재료를 다용한 787 드림라이너는 알루미늄으로 제작된 이전 세대 기종에 비해 연료 소비량을 20% 절감했으며, 6만 회의 가압 사이클을 견디는 폴리머 매트릭스의 유효성이 입증되었습니다. 전기자동차의 배터리 팩에서는 UL 94V-0 규격을 충족하면서 400마일의 주행 거리를 실현하기 위해 난연성 폴리카보네이트나 폴리아미드 6,6에 대한 의존도가 높아지고 있습니다. 미국 에너지부는 2025년까지 탄소섬유 비용을 1kg당 10달러 미만으로 낮추기 위해 2억 달러를 지원했습니다. 이는 자동차 양산 시장에서의 채택에 있어 매우 중요한 기준점으로 여겨집니다.
건설 및 전자 분야에서의 용도 확대
유리 전이 온도가 400°C를 초과하는 폴리이미드 필름은 현재 5G 기지국의 회로 기판에서 에폭시 적층판을 대체하여 28 GHz 주파수 대역에서 신호의 무결성을 보장하고 있습니다. 중국에서는 2025년 말까지 360만 기 이상의 5G 기지국이 설치될 예정이며, 이는 저손실 액정 폴리머 및 불소수지에 대한 지속적인 수요를 창출하고 있습니다. 건설 분야에서는 개정된 ‘국제 에너지 절약 기준(IECC)’에 따라 1인치당 R-6.5의 단열 성능을 가진 스프레이식 폴리우레탄 폼 단열재의 사용이 의무화되어, 이를 통해 건물의 에너지 부하를 최대 40%까지 절감하고 있습니다. 독일은 2025년에 상업용 부동산의 외벽을 고성능 폴리머 단열재로 개보수하기 위해 15억 유로를 배정했습니다.
원자재 가격 변동
2024년부터 2025년까지 브렌트 원유 가격은 배럴당 70달러에서 90달러 사이에서 변동했고, 헨리 허브 가격은 1 MMBtu당 2.50달러에서 4.20달러 범위에서 움직였기 때문에에틸렌 및 프로필렌 비용은 35% 변동했습니다. 브렌트 원유 가격에 연동되는 나프타에 의존하는 유럽 생산자들은 미국의 셰일가스 생산자에 비해 톤당 400달러가 넘는 현금 비용 불이익에 직면하여 이익률이 압박받았습니다. BASF의 추산에 따르면, 가격 전가에 지연이 발생할 경우 원유 가격이 배럴당 10달러 상승할 때마다 특수 기능성 고분자의 영업이익률은 약 150베이시스포인트 축소되는 것으로 나타났습니다. 소규모 컴파운더는 헤지 거래를 수행할 만한 규모가 부족하기 때문에 현물 가격이 급등할 경우 장기 계약은 리스크를 수반하게 됩니다.
부문별 분석
특수 열가소성 수지는 2025년 매출의 38.46%를 차지하며, 자동차 엔진룸, 반도체 웨트 벤치 및 일회용 의료기기 케이스에서 확고한 입지를 반영하고 있습니다. PEEK, PPS 및 액정 폴리머는 범용 수지로는 충족할 수 없는 내열성 및 내화학성 기준을 충족하며, 가격 프리미엄과 20%를 넘는 영업이익률을 유지하고 있습니다. 특수 복합재료는 절대 규모로는 작지만, 항공우주 및 해상 풍력발전 분야에서 인장 강도가 600 MPa를 초과하고 1,000만 회의 피로 주기를 견디는 탄소섬유 강화 폴리머의 채택이 진행되고 있어, 2031년까지 연평균 성장률(CAGR) 6.28%로 성장하고 있습니다. 복합재료는 항공기의 연료 소비량을 20-25% 절감하기 때문에 A350 XWB, 787 및 향후 나로우바디 항공기 등의 프로젝트에 채택됨에 따라, 파운드당 재료 비용이 비싸더라도 그 가치 제안이 입증되고 있습니다.
열경화성 수지는 인쇄회로기판 및 구조용 접착제 분야에서 여전히 중요한 역할을 하고 있지만, 그 성장률은 시장 평균보다 낮습니다. 이는 가교 네트워크가 EU 및 미국의 자동차 규제에 따른 재활용 목표 달성에 어려움을 초래하고 있기 때문입니다. 따라서 각 OEM 업체들이 제품 수명 종료 후의 처리 경로를 면밀히 검토하고 있는 만큼, 열경화성 수지의 특수 기능성 고분자 시장 규모는 복합재료의 연평균 성장률(CAGR)보다 낮습니다. 특수 엘라스토머는 전기자동차(EV) 배터리 씰링이나 반도체 웨이퍼 취급과 같은 수익성이 높은 틈새 시장을 차지하고 있으며, 특히 불소계 엘라스토머는 전해액 및 플라즈마 에칭액에 대한 내성을 발휘하고 있습니다. 초고분자량 폴리에틸렌 및 PTFE는 정형외과용 임플란트와 화학 공정용 라이닝에서 중요한 역할을 수행하며, 제품 포트폴리오를 보완하고 있습니다. 이러한 제품들은 ISO 21304 및 ASTM D3159 인증을 바탕으로 기존 시장 참여자들을 급속히 부상하는 신규 진입자들로부터 보호하고 있습니다.
지역별 분석
아시아태평양은 2025년에 전 세계 특수 기능성 고분자 시장 점유율의 45.27%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 5.94%로 확대될 전망입니다. 2025년, 중국 내 리튬이온 배터리 생산량은 750 GWh를 넘어섰으며, 폴리프로필렌 및 폴리에틸렌으로 만들어진 분리막을 약 15만 톤 소비했습니다. 인도의 약물전달 시스템용 특수 기능성 고분자 수출은 서방성 정제에서 하이드록시프로필메틸셀룰로오스 및 PVA에 대한 수요가 증가함에 따라 2025년에 28% 증가했습니다. 베트남과 태국에서는 IPC-4101 규격을 준수하는 고순도 폴리이미드 필름이 필요한 전자기기 조립에 대한 투자가 집중되고 있습니다. 한편, 일본과 한국에서는 정부 자금이 접이식 디스플레이용 무색 폴리이미드 기판에 투입되고 있습니다.
북미에서는 셰일 가스의 경제성과 ‘인플레이션 억제법(Inflation Reduction Act)’에 따른 우대 조치가 활용되고 있습니다. 미국 에너지부(DOE)는 2025년 배터리 메가팩토리에 31억 달러를 지원하여 PVDF 바인더 및 폴리에틸렌 분리막의 수요를 끌어올렸습니다. 캐나다의 노바 케미컬스는 배관 및 라이너 용도를 목적으로 한 20억 캐나다 달러 규모의 고밀도 폴리에틸렌 생산 거점 확장 계획에 최종 승인을 내렸습니다. 2025년 멕시코에서 생산될 350만 대의 경차는 USMCA(미국·멕시코·캐나다 협정) 공급망을 위해 케레타로주 및 누에보레온주에서 배합된 강화 열가소성 수지에 의존하고 있습니다.
유럽의 특수 기능성 고분자 시장은 REACH 규정 준수 및 사용 후 제품 재활용에 관한 지침에 의해 형성되고 있습니다. 독일의 기계적 재활용 업체들은 2025년에 18만 톤의 엔지니어링 열가소성 수지를 처리하여 2023년 대비 22% 증가했습니다. 프랑스는 2025년, PET 및 PLA 단량체 회수를 위한 화학적 재활용 시범 사업에 8억 유로를 투자했습니다. 영국은 1억 5,000만 파운드를 투자해 탄소섬유 재활용에 나서고 있으며, 항공우주 분야에서의 재사용을 위해 인장 강도의 95%를 회복시키고 있습니다. 중동의 생산자들은 톤당 250달러 미만의 에틸렌 현금 비용을 활용하여 특수 폴리에틸렌 및 EVA를 아시아의 가공업체에 수출하고 있습니다. 남미에서는 브라스크엠(Braskem)의 상파울루에 위치한 폴리프로필렌 컴파운딩 거점이 공급하는 브라질 자동차 및 포장 시장에 계속해서 주력하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.07According to Mordor Intelligence, the specialty polymers market size is expected to increase from USD 155.11 billion in 2025 to USD 157.64 billion in 2026 and reach USD 170.91 billion by 2031, growing at a CAGR of 1.63% over 2026-2031.
This report is Segmented by Type (Specialty Elastomers, Specialty Composites, Specialty Thermoplastics, Specialty Thermosets, and Other Types), End-User Industry (Automotive and Transportation, Consumer Goods, Building and Construction, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Specialty Polymers Market Trends and Insights
Lightweighting Demand in Automotive and Aerospace
More stringent fuel-economy and emissions regulations are urging automakers and aircraft OEMs to trim weight by swapping steel and aluminum with structural carbon-fiber composites and glass-fiber-reinforced thermoplastics that pare mass by 30-50% without sacrificing crash performance. Boeing's composite-rich 787 Dreamliner cuts fuel burn 20% versus aluminum predecessors, validating polymer matrices that withstand 60,000 pressurization cycles. Electric-vehicle battery packs increasingly rely on flame-retardant polycarbonate and polyamide 6,6 to reach 400-mile ranges while meeting UL 94 V-0 standards. The U.S. Department of Energy directed USD 200 million in 2025 toward lowering carbon-fiber costs below USD 10 per kg, a threshold seen as critical for mass-market vehicle adoption.
Expanding Construction and Electronics Uses
Polyimide films rated above 400 °C glass-transition temperature now replace epoxy laminates in 5G base-station circuit boards, safeguarding signal integrity at 28 GHz frequencies. China installed more than 3.6 million 5G base stations by end-2025, generating sustained demand for low-loss liquid-crystal polymers and fluoropolymers. In construction, spray polyurethane foam insulation delivering R-6.5 per inch is mandated in updated International Energy Conservation Code revisions, cutting building energy loads by up to 40%. Germany earmarked EUR 1.5 billion in 2025 to retrofit commercial property envelopes with high-performance polymer insulation.
Feedstock Price Volatility
Brent prices oscillated between USD 70 and USD 90 per barrel during 2024-2025, and Henry Hub ranged from USD 2.50 to USD 4.20 per MMBtu, driving a 35% swing in ethylene and propylene costs. European producers reliant on Brent-indexed naphtha faced cash-cost disadvantages above USD 400 per t versus U.S. shale-gas peers, squeezing margins. BASF calculated a USD 10 per barrel oil uptick trims specialty-polymer operating margins by roughly 150 basis points when price pass-through lags. Smaller compounders lack hedging scale, making long-term contracts risky when spot spikes surface.
Other drivers and restraints analyzed in the detailed report include:
- Abundant Gas-Based Feedstocks
- 3-D Printable Specialty Polymer Filaments Uptake
- Rapid Technology Replacement Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Specialty thermoplastics delivered 38.46% of 2025 revenue, reflecting entrenched positions in automotive under-hood, semiconductor wet benches, and single-use medical device housings. PEEK, PPS, and liquid-crystal polymers satisfy thermal and chemical resistance benchmarks unmet by commodity resins, sustaining price premiums and operating margins above 20%. Specialty composites, while smaller in absolute size, climb at a 6.28% CAGR through 2031 as aerospace and offshore wind adopt carbon-fiber-reinforced polymers that reach tensile strengths above 600 MPa and endure 10 million fatigue cycles. Because composites reduce aircraft fuel burn 20-25%, program adoption (A350 XWB, 787, future narrow-body designs) validates the value proposition even at high dollar-per-pound material costs.
Thermosets remain important in printed-circuit boards and structural adhesives yet grow below the market average because cross-linked networks challenge recyclability targets in EU and U.S. automotive regulations. The specialty polymers market size for thermosets therefore trails the composites CAGR as OEMs scrutinize end-of-life pathways. Specialty elastomers occupy lucrative niches in EV battery seals and semiconductor wafer-handling where fluoroelastomers resist electrolytes and plasma etchants. Ultra-high-molecular-weight polyethylene and PTFE round out the portfolio with critical roles in orthopedic implants and chemical process linings, aided by ISO 21304 and ASTM D3159 certifications that protect incumbents from fast-moving entrants.
Complete Report Scope:
- By Type
- Specialty Elastomers
- Specialty Composites
- Specialty Thermoplastics
- Specialty Thermosets
- Other Types
- By End-user Industry
- Automotive and Transportation
- Consumer Goods
- Building and Construction
- Coatings, Adhesives and Sealants
- Electrical and Electronics
- Healthcare
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi-Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 45.27% of the global specialty polymers market share in 2025 and is set to expand at a 5.94% CAGR to 2031. Domestic Chinese lithium-ion battery output topped 750 GWh in 2025, consuming roughly 150,000 t of polypropylene and polyethylene separators. India's specialty polymer exports for drug-delivery systems jumped 28% in 2025 as hydroxypropyl methylcellulose and PVA gained traction in controlled-release tablets. Vietnam and Thailand collect electronics-assembly investment that requires high-purity polyimide films meeting IPC-4101 specifications, while Japan and South Korea channel government funds into colorless polyimide substrates for foldable displays.
North America leverages shale-gas economics and Inflation Reduction Act incentives. DOE awarded USD 3.1 billion in 2025 to battery mega-factories, boosting demand for PVDF binders and polyethylene separators. Canada's Nova Chemicals green-lit a CAD 2 billion high-density polyethylene build-out aimed at pipe and liner applications. Mexico's 3.5 million-unit light-vehicle output in 2025 relies on reinforced thermoplastics compounded in Queretaro and Nuevo Leon for USMCA supply chains.
Europe's specialty polymers market is shaped by REACH compliance and end-of-life recycling directives. German mechanical recyclers processed 180,000 t of engineering thermoplastics in 2025, up 22% from 2023. France devoted EUR 800 million in 2025 to chemical recycling pilots for PET and PLA monomer recovery. The UK's GBP 150 million investment targets carbon-fiber recycling, recovering 95% of tensile strength for aerospace reuse. Middle Eastern producers capitalize on sub-USD 250 per t ethylene cash costs, exporting specialty polyethylene and EVA to Asian converters. South America remains focused on Brazilian automotive and packaging outlets serviced by Braskem's Sao Paulo polypropylene compounding hub.
- 3M
- Arkema Group
- Ashland Inc.
- Associated Industries Inc.
- BASF SE
- Braskem
- Chemtura Corporation
- Covestro
- Croda International PLC
- Elantas GmbH
- Endurance Technologies Limited
- Evonik Industries AG
- Hexion Inc.
- Huntsman Corp.
- Koninklijke DSM NV
- PolyOne
- S&E Specialty Polymers LLC
- Solvay
- Speciality Polymers Pvt. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Lightweighting demand in automotive and aerospace
- 4.2.2 Expanding construction and electronics uses
- 4.2.3 Abundant gas-based feedstocks
- 4.2.4 3-D printable specialty polymer filaments uptake
- 4.2.5 Perovskite-solar encapsulation film boom
- 4.3 Market Restraints
- 4.3.1 Feedstock price volatility
- 4.3.2 Rapid technology replacement cycles
- 4.3.3 Biodegradable-mandate drag on conventional grades
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Specialty Elastomers
- 5.1.2 Specialty Composites
- 5.1.3 Specialty Thermoplastics
- 5.1.4 Specialty Thermosets
- 5.1.5 Other Types
- 5.2 By End-user Industry
- 5.2.1 Automotive and Transportation
- 5.2.2 Consumer Goods
- 5.2.3 Building and Construction
- 5.2.4 Coatings, Adhesives and Sealants
- 5.2.5 Electrical and Electronics
- 5.2.6 Healthcare
- 5.2.7 Other End-user Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Russia
- 5.3.3.6 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi-Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 3M
- 6.4.2 Arkema Group
- 6.4.3 Ashland Inc.
- 6.4.4 Associated Industries Inc.
- 6.4.5 BASF SE
- 6.4.6 Braskem
- 6.4.7 Chemtura Corporation
- 6.4.8 Covestro
- 6.4.9 Croda International PLC
- 6.4.10 Elantas GmbH
- 6.4.11 Endurance Technologies Limited
- 6.4.12 Evonik Industries AG
- 6.4.13 Hexion Inc.
- 6.4.14 Huntsman Corp.
- 6.4.15 Koninklijke DSM NV
- 6.4.16 PolyOne
- 6.4.17 S&E Specialty Polymers LLC
- 6.4.18 Solvay
- 6.4.19 Speciality Polymers Pvt. Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


