

|
시장보고서
상품코드
2121561
무선 라우터 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Wireless Router - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 따르면 무선 라우터 시장 규모는 2026년에 181억 3,000만 달러로 추정되며, 2025년 166억 2,000만 달러에서 성장하여 2031년에는 280억 2,000만 달러에 달할 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 9.08%로 성장할 것으로 전망됩니다.
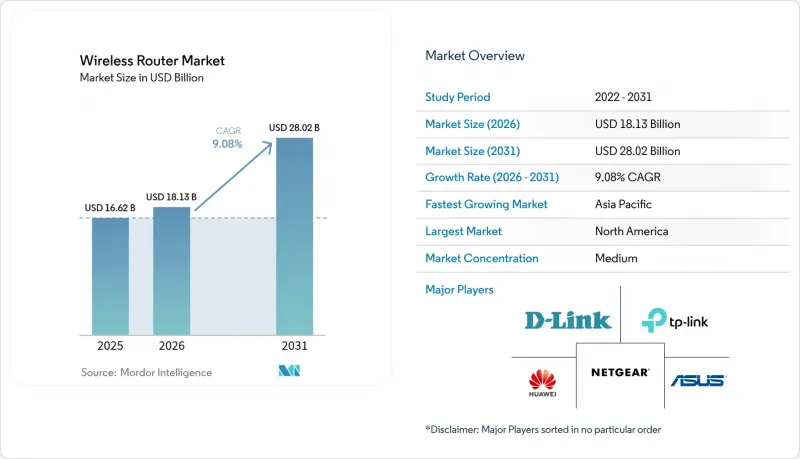
본 보고서는 제품 유형(독립형 라우터, 메시 Wi-Fi 시스템 등), Wi-Fi 표준(802.11n, 802.11ac, 802.11ax, 802.11be), 주파수 대역(싱글 밴드, 듀얼 밴드, 트라이/쿼드 밴드), 최종사용자 산업(가정용, 기업용), 유통 채널(온라인 소매업체, 오프라인), 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 단위로 제시되어 있습니다.
세계 무선 라우터 시장의 동향 및 인사이트
증가하는 인터넷 트래픽과 연결 기기
전 세계적으로 211억 대 이상의 Wi-Fi 기기가 가동 중이며, 2024년에는 41억 대가 추가로 출하될 것으로 예상됩니다. 이로 인해 기존 네트워크는 포화 상태에 이르러 멀티 기가비트 라우터로의 업그레이드가 촉진되고 있습니다. 현재 가정용 광대역 사용자의 약 5분의 1이 월간 데이터 사용량 1TB를 초과하고 있어, 서비스 품질(QoS)의 한계치에 부담이 가해지고 있습니다. 스마트 팩토리, 스마트 시티, 자율주행차 분야의 IoT 성장에 따라 Wi-Fi 7의 320 MHz 채널이 실현 가능한 저지연·고처리량에 대한 수요가 더욱 높아지고 있습니다. Wi-Fi 6 액세스 포인트가 실용상의 한계에 도달하면, 기업들은 기기 밀도 문제에 직면하게 되어 차세대 무선 장비에 대한 투자를 피할 수 없게 됩니다. 그 결과, 업데이트 주기가 가속화되어 Wi-Fi 7 제품군을 보유한 벤더에게 유리한 상황이 조성되고 있습니다.
대역폭 수요를 주도하는 기업의 디지털화
기업의 45%는 이미 Wi-Fi 6과 프라이빗 5G를 병행하여 시범 도입하고 있으며, 통합된 무선 패브릭에 대한 선호도가 두드러지고 있습니다. 제조 공장에서는 AI 탑재 로봇, 1밀리초 미만의 감시 제어, 그리고 머신비전 분석을 수행하기 위해 Wi-Fi 7이 채택되고 있습니다. 2025년에는 주요 공급업체의 AI 인프라 관련 분기별 라우터 수주액이 3억 5,000만 달러를 넘어섰습니다. 구독형 ‘NaaS(Network as a service)’ 모델은 자본 지출(CAPEX)의 장벽을 낮추고 더 신속한 배포를 가능하게 합니다. 요컨대, 대역폭을 대량으로 소비하는 애플리케이션과 유연한 자금 조달이 결합되어 무선 라우터 시장을 견인하고 있는 것입니다.
네트워크 보안의 복잡화와 기술 인력 부족
ASUS 라우터의 CVE-2024-3080 취약점을 악용한 3.8 Tbps 규모의 DDoS 공격은 이 업계가 펌웨어 취약점에 노출되어 있다는 현실을 여실히 드러냈습니다. 한편, 통신 사업자 측에서는 특히 새로운 Wi-Fi 7의 보안 및 WPA3 설정과 관련하여 자격을 갖춘 네트워크 엔지니어가 33% 부족하다고 보고하고 있습니다. 기업들은 전문적인 컨설팅이 필요하기 때문에 도입 비용이 높아지고, 프로젝트 리드타임이 길어지고 있습니다. 중소기업의 경우 설정이 허술한 채로 방치되는 경우가 많아, 이로 인해 보안 침해 위험이 높아지고, 고도의 위협 탐지 기능을 갖춘 고성능 라우터의 도입이 제한되고 있습니다.
부문 분석
2025년 시점에서 독립형 라우터는 43.62%의 점유율을 유지했으나, 사용자가 구석구석까지 커버하는 통신 범위와 자동 최적화되는 성능을 요구하는 가운데, 메시형 카테고리는 2031년까지 연평균 성장률(CAGR) 11.74%로 확대될 전망입니다. 메시 구축과 관련된 무선 라우터 시장 규모는 멀티 기가비트 광섬유 구축에 따라 확대될 것으로 예측됩니다. ISP가 ‘Aginet’이나 ‘eero for Service Providers’와 같은 클라우드 관리형 플랫폼을 채택하고 있는 점도 성장세를 뒷받침하고 있습니다. 대조적으로, 모바일 핫스팟 라우터는 5G 무선 기능을 탑재함으로써 다시 주목받고 있으며, 산업용 모델은 가혹한 환경 요구 사항을 충족하고 있습니다.
각 메시 벤더들은 현재 AI 알고리즘, Wi-Fi 7의 멀티링크 작동, 그리고 320 MHz 백홀 채널을 통합하여 프리미엄 가격을 유지하고 있습니다. 독립형 모델은 트라이밴드 무선 기능과 지연 시간 제어 엔진을 탑재하여 게이머층을 점점 더 타겟으로 삼고 있습니다. 산업용 라우터는 SD-WAN 오버레이를 활용하여 원격지의 자산을 안전하게 연결합니다. 이러한 하위 부문 전체를 살펴보면, 엔트리 레벨 하드웨어가 상품화되어 가는 상황 속에서도 혁신 분야가 어떻게 수익률을 지키고 있는지 알 수 있습니다.
Wi-Fi 5는 대중 시장을 겨냥한 합리적인 가격 덕분에 여전히 41.55%의 점유율을 차지하고 있지만, Wi-Fi 7의 출하량은 연평균 성장률(CAGR) 24.74%를 기록하며 무선 라우터 시장을 재편할 전망입니다. 6-15 Gbps의 실효 처리량에 대한 기업의 수요가 조기 도입을 촉진하고 있으며, Wi-Fi 7 관련 무선 라우터 시장 규모는 향후 10년 말까지 Wi-Fi 6을 추월할 가능성이 있습니다. 인증 획득으로 인해 멀티 벤더 간의 상호 운용성에 대한 우려는 완화되었지만, 전력 소비 증가에 따라 PoE 스위치의 업그레이드가 필요하게 될 것입니다.
Wi-Fi 6은 여전히 과도기적인 기술로, 예산이 제한된 구매자에게 OFDMA의 효율성을 제공하고 있습니다. 기존의 Wi-Fi 4 기기는 속도보다 비용이나 전력 소비가 우선시되는 틈새 IoT 환경에서 여전히 사용되고 있습니다. 선진 지역에서는 조달 로드맵에 엣지 컴퓨팅 투자와 결합된 단계적인 Wi-Fi 7 도입이 포함되어 있어, 대규모 시스템 개편 없이도 미래를 대비한 용량을 확보할 수 있게 되었습니다.
지역별 분석
아시아태평양은 5G 구축, 스마트 시티 계획, 그리고 진행 중인 제조업의 디지털화를 바탕으로 2025년에는 전 세계 매출의 33.55%를 차지했습니다. 싱가포르와 한국의 국가적 노력이 Wi-Fi 7 백본 연결에 대한 수요를 뒷받침하는 한편, 중국 벤더들은 보안 심사와 관련된 해외 규제상의 역풍을 극복하기 위해 노력하고 있습니다. 이 지역 전체에 걸친 하이퍼스케일 데이터센터의 확장은 고처리량 라우터에 대한 기업 수주를 더욱 촉진하고 있습니다.
북미는 적극적인 광섬유망 구축과 서비스가 미치지 않는 농촌 지역에 장비를 도입하기 위한 대규모 BEAD 자금 덕분에 여전히 중요한 시장으로 남아 있습니다. 2024년에는 고정 무선 접속 가입자 수가 1,200만 명을 돌파하여, 하이브리드형(셀룰러·Wi-Fi) 게이트웨이를 통해 라우터 판매에 압박을 가하는 한편, 이를 보완하는 역할도 하고 있습니다. 기업용 시장은 이미 Wi-Fi 7 AP 출하대수의 2%를 차지하고 있으며, 이 수치는 2025년까지 5배로 증가할 것으로 예상됩니다.
유럽에서는 멀티 기가비트 광섬유와 6GHz 대역의 단계적 개방에 힘입어 꾸준한 성장을 보이고 있습니다. 프랑스는 Wi-Fi 7 도입을 주도하고 있으며, 프리미엄 CPE가 광대역 서비스 계층을 어떻게 차별화하고 있는지 보여주고 있습니다. 독일과 영국은 인더스트리 4.0과 보안 네트워크를 우선시하며, WPA3 및 AI 기반 위협 분석 기능을 갖춘 트라이밴드 라우터에 대한 수요를 주도하고 있습니다. 브렉시트 이후의 미묘한 규제 차이는 여전히 인증 일정을 복잡하게 만들고 있으며, 공급업체들은 지역에 맞춘 물류 전략을 모색해야 하는 상황에 처해 있습니다.
남미는 FTTH(Fiber-to-the-Home)의 확대와 농촌 지역 연결 지원책을 배경으로 연평균 성장률(CAGR) 10.47%라는 가장 빠른 성장 궤적을 기록하고 있습니다. 브라질이 확장을 주도하는 한편, 지역 통화의 변동성으로 인해 독창적인 가격 책정 모델이 요구되고 있습니다. 중동 및 아프리카의 신흥 시장에서는 스마트 시티 구상을 활용하여 호텔·관광, 교육, 공공 부문 환경에서 Wi-Fi 7의 시범 도입을 추진하고 있으며, 장기적인 수요 기반을 구축하고 있습니다.
기타 혜택:
- Excel 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모·성장률 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 동향
KSM 26.09.07According to Mordor Intelligence, wireless router market size in 2026 is estimated at USD 18.13 billion, growing from 2025 value of USD 16.62 billion with 2031 projections showing USD 28.02 billion, growing at 9.08% CAGR over 2026-2031.
This report is Segmented by Product Type (Standalone Routers, Mesh Wi-Fi Systems, and More), Wi-Fi Standard (802. 11n, 802. 11ac, 802. 11ax, 802. 11be), Frequency Band (Single-Band, Dual-Band, Tri-/Quad-Band), End-User Industry (Residential, Enterprise), Distribution Channel (Online Retailers, Offline), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Wireless Router Market Trends and Insights
Growing Internet Traffic and Connected Devices
More than 21.1 billion Wi-Fi devices are active worldwide, and another 4.1 billion are expected to ship in 2024, saturating legacy networks and prompting upgrades to multi-gigabit routers. Roughly one-fifth of residential broadband users now exceed 1 TB of monthly data, stressing quality-of-service thresholds. IoT growth in smart factories, smart cities, and autonomous mobility deepens the need for low-latency throughput that Wi-Fi 7's 320 MHz channels can deliver. Enterprises face device-density headaches when Wi-Fi 6 access points hit practical limits, forcing investment in next-generation radios. The result is an accelerated refresh cycle favoring vendors with Wi-Fi 7 portfolios.
Enterprise Digitalization Driving Bandwidth Demand
Forty-five percent of enterprises already trial both Wi-Fi 6 and private 5G in parallel, highlighting a preference for converged wireless fabrics. Manufacturing plants adopt Wi-Fi 7 to run AI-enabled robotics, sub-millisecond supervisory control, and machine-vision analytics. Quarterly router orders tied to AI infrastructure surpassed USD 350 million among leading suppliers in 2025. Subscription-based network-as-a-service models lower capex barriers, allowing faster rollouts. In short, bandwidth-hungry applications and flexible financing coalesce to push the wireless router market forward.
Network-Security Complexity and Skill Shortages
A 3.8 Tbps DDoS attack exploiting the ASUS router CVE-2024-3080 illustrated the sector's exposure to firmware vulnerabilities. Meanwhile, telecom operators report a 33% shortfall in qualified network engineers, particularly for emerging Wi-Fi 7 security and WPA3 configurations. Enterprises face higher deployment costs due to specialist consulting needs, stretching project lead times. Small firms often default to lax settings, heightening breach risks and limiting the adoption of premium routers with advanced threat detection.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Adoption of Wi-Fi 6/6E and Wi-Fi 7
- Mesh Wi-Fi as a Managed Service by ISPs
- Mobile/5G Broadband Substitution Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Standalone routers retained a 43.62% share in 2025, yet the mesh category is on track for an 11.74% CAGR through 2031 as users seek wall-to-wall coverage and self-optimizing performance. The wireless router market size tied to mesh deployments is forecast to expand in tandem with multi-gigabit fiber rollouts. ISP adoption of cloud-managed platforms such as Aginet and eero for Service Providers reinforces growth momentum. In contrast, mobile hotspot routers gain renewed relevance by embedding 5G radios, while industrial models address harsh-environment requirements.
Mesh vendors now bake in AI algorithms, Wi-Fi 7 multi-link operation, and 320 MHz backhaul channels to sustain premium pricing. Standalone designs increasingly target gamers, featuring tri-band radios and latency-shaping engines. Industrial routers leverage SD-WAN overlays to connect remote assets securely. Collectively, these sub-segments illustrate how innovation niches defend margin even as entry-level hardware commoditizes.
Wi-Fi 5 still commands 41.55% share thanks to mass-market affordability, but Wi-Fi 7 shipments are set for a 24.74% CAGR that will reshape the wireless router market. Enterprise demand for 6-15 Gbps real-world throughput pushes early adoption, and the wireless router market size linked to Wi-Fi 7 could surpass Wi-Fi 6 by the decade's end. Certification has eased multi-vendor interoperability concerns, although higher power requirements necessitate PoE switch upgrades.
Wi-Fi 6 remains a bridge technology, offering OFDMA efficiency to budget-constrained buyers. Legacy Wi-Fi 4 devices persist in niche IoT settings where cost and power trump speed. In advanced regions, procurement roadmaps now include phased Wi-Fi 7 rollouts paired with edge-compute investments, ensuring future-proof capacity without forklift overhauls.
Complete Report Scope:
- By Product Type
- Standalone Routers
- Mesh Wi-Fi Systems
- Mobile Hotspot Routers
- Industrial/Rugged Routers
- By Wi-Fi Standard
- 802.11n (Wi-Fi 4)
- 802.11ac (Wi-Fi 5)
- 802.11ax (Wi-Fi 6)
- 802.11be (Wi-Fi 7)
- By Frequency Band
- Single-Band
- Dual-Band
- Tri-/Quad-Band
- By End-user Industry
- Residential
- Enterprise
- BFSI
- Education
- Healthcare
- Media and Entertainment
- Retail
- Government and Public Sector
- Other Enterprises
- By Distribution Channel
- Online Retailers
- Offline (CE Stores, Hypermarkets)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific held 33.55% of global revenue in 2025, buoyed by 5G rollouts, smart-city programs, and ongoing manufacturing digitization. National initiatives in Singapore and South Korea anchor demand for Wi-Fi 7 backbone connectivity, while Chinese vendors navigate overseas regulatory headwinds tied to security scrutiny. Hyperscale data-center expansion throughout the region further bolsters enterprise orders for high-throughput routers.
North America remains pivotal, thanks to aggressive fiber builds and sizable BEAD funding that directs equipment to underserved rural zones. Fixed-wireless access surpassed 12 million subscribers in 2024, simultaneously pressuring and complementing router sales via hybrid cellular-Wi-Fi gateways. Enterprises already account for 2% of Wi-Fi 7 AP shipments, a figure expected to quintuple by 2025.
Europe posts steady gains behind multi-gigabit fiber and phased 6 GHz clearance. France leads Wi-Fi 7 adoption, showcasing how premium CPE differentiates broadband tiers. Germany and the U.K. prioritize Industry 4.0 and secure networking, driving demand for tri-band routers with WPA3 and AI-powered threat analytics. Regulatory nuances post-Brexit still complicate certification timetables, nudging vendors toward localized logistics strategies.
South America registers the fastest trajectory at 10.47% CAGR on the back of fiber-to-the-home expansion and rural-connectivity subsidies. Brazil spearheads rollouts, while regional currency volatility forces creative pricing models. Emerging markets in the Middle East and Africa are leveraging smart-city ambitions to pilot Wi-Fi 7 in hospitality, education, and public-sector environments, laying groundwork for long-term demand.
- TP-Link Technologies Co., Ltd.
- NETGEAR, Inc.
- ASUSTeK Computer Inc.
- D-Link Corporation
- Huawei Technologies Co., Ltd.
- Cisco Systems, Inc.
- Ubiquiti Inc.
- CommScope Holding Company, Inc. (ARRIS)
- Amazon.com, Inc. (eero)
- Google LLC (Nest Wi-Fi)
- Belkin International, Inc. (Linksys)
- Xiaomi Corporation
- Buffalo Americas, Inc.
- Zyxel Communications Corp.
- MikroTik SIA
- TOTOLINK (CJSC Est.)
- Edimax Technology Co., Ltd.
- Amped Wireless (A division of NexGen Connected LLC)
- Mercury-PC Technology Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing internet traffic and connected devices
- 4.2.2 Enterprise digitalization driving bandwidth demand
- 4.2.3 Rapid adoption of Wi-Fi 6/6E and forthcoming Wi-Fi 7
- 4.2.4 Mesh-Wi-Fi as a managed service by ISPs (under-the-radar)
- 4.2.5 Government-funded rural broadband CPE roll-outs (under-the-radar)
- 4.2.6 Emerging Wi-Fi sensing applications for ambient intelligence (under-the-radar)
- 4.3 Market Restraints
- 4.3.1 Network-security complexity and skill shortages
- 4.3.2 Mobile/5G broadband substitution risk
- 4.3.3 Semiconductor supply-chain volatility (under-the-radar)
- 4.3.4 Uneven global release of 6 GHz spectrum (under-the-radar)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Standalone Routers
- 5.1.2 Mesh Wi-Fi Systems
- 5.1.3 Mobile Hotspot Routers
- 5.1.4 Industrial/Rugged Routers
- 5.2 By Wi-Fi Standard
- 5.2.1 802.11n (Wi-Fi 4)
- 5.2.2 802.11ac (Wi-Fi 5)
- 5.2.3 802.11ax (Wi-Fi 6)
- 5.2.4 802.11be (Wi-Fi 7)
- 5.3 By Frequency Band
- 5.3.1 Single-Band
- 5.3.2 Dual-Band
- 5.3.3 Tri-/Quad-Band
- 5.4 By End-user Industry
- 5.4.1 Residential
- 5.4.2 Enterprise
- 5.4.3 BFSI
- 5.4.4 Education
- 5.4.5 Healthcare
- 5.4.6 Media and Entertainment
- 5.4.7 Retail
- 5.4.8 Government and Public Sector
- 5.4.9 Other Enterprises
- 5.5 By Distribution Channel
- 5.5.1 Online Retailers
- 5.5.2 Offline (CE Stores, Hypermarkets)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Russia
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 Middle East
- 5.6.4.1.1 Saudi Arabia
- 5.6.4.1.2 United Arab Emirates
- 5.6.4.1.3 Rest of Middle East
- 5.6.4.2 Africa
- 5.6.4.2.1 South Africa
- 5.6.4.2.2 Egypt
- 5.6.4.2.3 Rest of Africa
- 5.6.4.1 Middle East
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration Analysis
- 6.2 Strategic Moves (M&A, Partnerships, Launches)
- 6.3 Market Share Analysis (Top-15, 2024)
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 TP-Link Technologies Co., Ltd.
- 6.4.2 NETGEAR, Inc.
- 6.4.3 ASUSTeK Computer Inc.
- 6.4.4 D-Link Corporation
- 6.4.5 Huawei Technologies Co., Ltd.
- 6.4.6 Cisco Systems, Inc.
- 6.4.7 Ubiquiti Inc.
- 6.4.8 CommScope Holding Company, Inc. (ARRIS)
- 6.4.9 Amazon.com, Inc. (eero)
- 6.4.10 Google LLC (Nest Wi-Fi)
- 6.4.11 Belkin International, Inc. (Linksys)
- 6.4.12 Xiaomi Corporation
- 6.4.13 Buffalo Americas, Inc.
- 6.4.14 Zyxel Communications Corp.
- 6.4.15 MikroTik SIA
- 6.4.16 TOTOLINK (CJSC Est.)
- 6.4.17 Edimax Technology Co., Ltd.
- 6.4.18 Amped Wireless (A division of NexGen Connected LLC)
- 6.4.19 Mercury-PC Technology Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-space and Unmet-Need Assessment


