

|
시장보고서
상품코드
2121562
메타자일렌 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Meta-Xylene - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
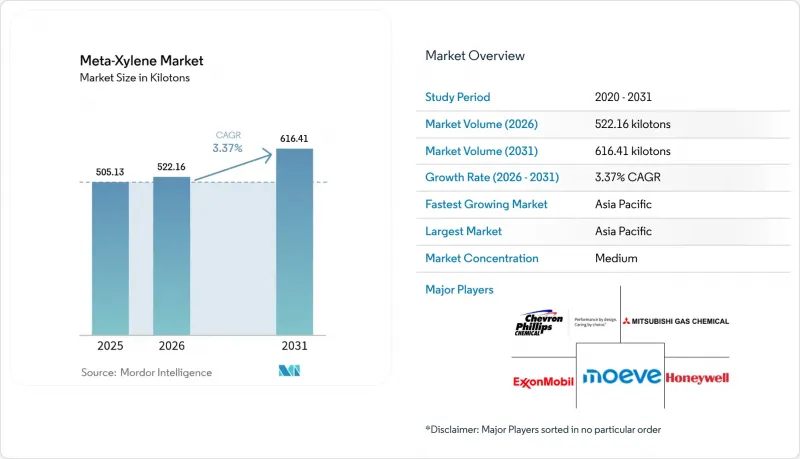
에 의하면, 메타자일렌 시장 규모는 2025년 505.13킬로톤에서 2026년에는 522.16킬로톤에 이르고, 2026-2031년 CAGR 3.37%로 성장을 지속하여 2031년까지 616.41킬로톤에 이를 것으로 예측됩니다.
본 보고서는 용도별(이소프탈산, 2,4- 및 2,6-크실리딘 등), 최종 사용자 산업별(건설 및 인프라, 포장, 자동차 및 운송 등),순도/등급(고순도 MX, 산업용 등급 MX 등), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 수량(톤) 단위로 제시되어 있습니다.
세계 메타자일렌 시장 동향 및 인사이트
PET 및 UPR 생산에서 이소프탈산 수요 증가
이소프탈산은 개질 PET의 열안정성 및 가스 차단 성능을 향상시키기 위해 고급 병, 필름, 산업용 섬유에 필수적인 소재가 되었습니다. 자동차 및 전자기기 제조업체들은 온도가 표준 PET의 허용 범위를 초과하는 경우, 이소프탈산 개질 PET의 사용을 지정하고 있으며, 이로 인해 메타자일렌 수요가 견인되고 있습니다. 혁신 파이프라인에서는 5-하이드록시메틸푸르푸랄(HMF)과 같은 재생 가능한 원료에 대한 의존도가 높아지고 있습니다. 상업적 규모에 도달하면, 브랜드 소유자들이 탄소 감축 목표를 추구하는 가운데 향후 10년 이내에 바이오 제조 경로가 시장 점유율을 확보할 것으로 예측됩니다. UPR 분야에서는 이소프탈산이 풍력 터빈의 나셀 및 선박용 복합재료에서 높은 내식성을 발휘하여, 아시아태평양의 조선소 및 유럽의 해상 시설에서 구조용 용도의 성장을 뒷받침하고 있습니다. PET와 UPR에서의 이중 수요는 그에 따라 메탁실렌 시장 동향에 가장 강력한 긍정적 영향을 미치고 있습니다.
고고형분·저VOC 산업 용도료로의 전환
미국 환경보호청(EPA)의 2024년 ‘유해물질 정보 전달 기준(Hazard Communication Standard)’ 개정에 따라 자일렌 유도체의 표시 기준이 엄격해졌으며, 배합 제조업체들은 효과적인 점도 제어를 위해 여전히 메타자일렌에 의존하고 있지만, 고고형분 시스템으로의 전환을 강요받고 있습니다. 마찬가지로, 유럽의 탈탄소화 로드맵도 저VOC 도료를 장려하고 있으며, 메타자일렌의 비교적 완만한 증발 특성이 높이 평가되어, 더 가볍고 증발이 빠른 용제에서 메타자일렌으로의 대체가 진행되고 있습니다. 수성 도료에서는 용제의 총 사용량이 감소하지만, 고급 건축용 및 산업용 유지보수 제품에서는 여전히 메타자일렌이 응집 보조제로 배합되어 있어, 예측 기간 동안 수요가 유지될 전망입니다.
독성 및 가연성 특성으로 인해 더 엄격한 노출 한계값 설정이 촉진됨
미국 독성물질 및 질병 등록국(ATSDR)은 자일렌에 대한 만성 노출과 관련된 신경계 문제를 강조하고 있으며, 이에 따라 유럽 규제 당국은 8시간 TWA(시간 평균) 직업 노출 한계치를 하향 조정하는 방안을 검토하고 있습니다. 환기 설비의 강화, 불꽃 방지형 취급 시스템 및 개인보호구(PPE)의 도입은 특히 소규모 또는 독립된 시설에서 생산 비용을 상승시킵니다. 가능한 경우, 도료 제조업체들은 대체 용매를 시험하고 있지만, 메타자일렌 특유의 용해력 및 가공 특성으로 인해 완전한 대체가 어려워 수요는 억제될 수는 있겠지만 완전히 사라지지는 않을 것입니다.
부문 분석
이소프탈산 생산은 2025년에 메타자일렌 시장 규모의 45.58%를 차지하며 최대 점유율을 기록하고 있어, 고성능 PET 병 및 내식성 UPR 라미네이트 분야에서 이 부문이 차지하는 확고한 역할을 부각시키고 있습니다. 바이오 유래 이소프탈산에 대한 점진적인 전환은 2031년까지 연평균 성장률(CAGR) 6.72%를 나타낼 것으로 예측되며, 재생 가능 화학 물질이 상업화 단계에 접어들면서 원료 조달의 구조적 재편이 진행되고 있음을 보여줍니다. 유럽과 일본의 조기 도입 기업들은 브랜드 소유자로부터 프리미엄 가격을 확보하기 위해 이미 물질 수지 절차 인증을 획득한 반면, 아시아의 생산자들은 바이오매스 공급 경로 인근에 신규 공장을 건설하고 있습니다.
중기적으로는 2,4- 및 2,6-자일리딘에서 유래한 농약 및 의약품 중간체는 독성에 대한 규제상의 우려에도 불구하고 틈새 수요를 유지할 것으로 보입니다. 용매 용도는 절대 톤수로는 축소되고 있지만, 특수 전자기기 및 의약품 세척에서 메타자일렌의 좁은 비등점 범위가 요구되는 분야에서는 가치가 견조한 것으로 나타났습니다. 이 모든 것을 종합해 보면, 용도 구성은 대량 용제에 대한 의존에서 수익성이 높은 수지 및 특수 화학제품 용도로 전환되고 있으며, 전반적인 성장률은 완만하지만 전반적인 수익성은 향상되고 있습니다.
지역별 분석
아시아태평양은 2025년에 세계 생산량의 52.98%를 차지할 것으로 예상되며, 원료의 유연성과 규모의 경제를 활용하는 중국 및 인도의 수직 통합형 복합 시설에 힘입어 2031년까지 연평균 성장률(CAGR) 5.32%를 나타낼 것으로 전망됩니다. 중국의 저우산(舟山) 방향족 허브와 광둥성의 CNOOC-쉘 합작 사업은 각각 지역의 자급률을 높이고, 미국 및 유럽으로부터의 수입 수요를 억제하고 있습니다. 인도의 870억 달러 규모의 석유화학 개발 계획은 2035년까지 국내 크실렌 생산 능력을 550만 톤으로 확대하여, 하류 폴리에스터, 도료, 의약품 산업 클러스터에 대한 원료 공급을 확보하는 것을 목표로 하고 있습니다. 일본과 한국은 중국의 수출 확대에 따른 경쟁 심화로 구조적인 이익률 압박에 직면해 있으며, 이에 따라 양국은 고순도 특수 제품 및 차별화된 배합 제품으로의 전환을 가속화하고 있습니다.
북미는 뛰어난 분리 기술, 풍부한 셰일 유래 나프타, 그리고 방대한 도료 고객 기반과의 근접성 덕분에 전략적 중요성을 유지하고 있습니다. 그러나 에너지 비용 상승 압력과 환경 규제 강화로 인해 운영비가 증가하고 있습니다. 셰브론이 Philips 66의 CPChem 지분을 150억 달러 규모로 인수할 계획인 것은 기업들이 규모 확대와 원료 통합의 이점을 추구하는 가운데 해당 지역의 업계 재편 흐름을 여실히 보여주고 있습니다. 멕시코에서 부상하고 있는 자동차 산업의 밸류체인은 용제 및 수지 수요를 자극하고 있지만, 미국산 수입에 크게 의존하고 있어 USMCA(미국·멕시코·캐나다 협정)에 따른 관세 안정성이 중요함을 시사합니다.
유럽은 가장 심각한 경영 과제에 직면해 있으며, 높은 에너지 비용과 엄격한 탄소 정책이 범용 방향족 화합물에 대한 신규 투자를 가로막고 있습니다. ‘유럽 그린딜’ 하에서 진화를 거듭하고 있는 탄소 국경 조정 메커니즘은 국내 생산을 부분적으로 보호할 가능성은 있지만, 행정적 복잡성을 가중시킬 수도 있습니다. 쉘(Shell)이 2030년까지 기초 화학 사업에서 철수하겠다고 발표한 것은 국제적인 대형 에너지 기업들이 자본을 LNG 및 재생에너지로 재분배하고 있는 상황을 상징합니다. 유럽에 남아 있는 각 생산 기업들은 기후 중립 소재에 대한 규제상의 우대 조치를 활용하여, 바이오 유래 이소프탈산 및 순환형 PET 원료에 주력하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the meta-Xylene market size is expected to grow from 505.13 kilotons in 2025 to 522.16 kilotons in 2026 and is forecast to reach 616.41 kilotons by 2031 at 3.37% CAGR over 2026-2031.
This report is Segmented by Application (Isophthalic Acid, 2, 4- & 2, 6-Xylidine, and More), End-User Industry (Construction & Infrastructure, Packaging, Automotive & Transportation, and More), Purity/Grade (High-Purity MX, Industrial-Grade MX, and More), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Volume (tons).
Global Meta-Xylene Market Trends and Insights
Growing Demand for Isophthalic Acid in PET & UPR Production
Isophthalic acid enhances thermal stability and gas-barrier performance in modified PET, making it indispensable for premium bottles, films and industrial fibers. Automotive and electronics manufacturers specify isophthalic acid-modified PET when temperatures exceed standard PET thresholds, reinforcing pull-through demand for meta-xylene. Innovation pipelines increasingly rely on renewable feedstocks such as 5-hydroxymethylfurfural (HMF); once commercial scale is reached, bio-based routes are expected to capture share within the next decade as brand owners pursue carbon-reduction goals. In UPR, isophthalic acid delivers higher corrosion resistance in wind-turbine nacelles and marine composites, supporting structural applications growth across Asia-Pacific shipyards and European offshore installations. The dual demand from PET and UPR accordingly registers the strongest positive impact on the meta-xylene market trajectory.
Shift Toward High-Solids/Low-VOC Industrial Coatings
The United States Environmental Protection Agency's 2024 Hazard Communication Standard update tightened labeling norms for xylene derivatives, pushing formulators toward higher-solids systems that still rely on meta-xylene for effective viscosity control. Europe's decarbonization roadmap similarly incentivizes low-VOC coatings, driving substitution of lighter, faster-evaporating solvents in favor of meta-xylene's more moderate evaporation profile. Although waterborne paints reduce aggregate solvent volumes, premium architectural and industrial maintenance products continue to incorporate meta-xylene as a coalescent aid, preserving demand through the forecast period.
Toxicological & Flammability Profile Driving Stricter Exposure Limits
The Agency for Toxic Substances and Disease Registry (ATSDR) underscores neurological concerns linked to chronic xylene exposure, prompting European regulators to contemplate lowering the 8-hour TWA occupational limit. Implementing enhanced ventilation, spark-proof handling systems, and personal protective equipment raises production costs, especially for small or standalone facilities. Where viable, coatings producers experiment with alternative solvents, yet meta-xylene's unique solvency and processing characteristics hinder full substitution, tempering but not eliminating demand.
Other drivers and restraints analyzed in the detailed report include:
- Capacity Expansions in Integrated PX-MX Aromatics Complexes
- Increasing Demand from Paints and Coatings Sector
- Crude-Oil Price Volatility Cascading to Aromatics Spreads
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Isophthalic acid production accounted for the largest share of the meta-xylene market size, at 45.58% in 2025, underscoring the segment's entrenched role in high-performance PET bottles and corrosion-resistant UPR laminates. The progressive switch toward bio-based isophthalic acid, projected to grow at 6.72% CAGR to 2031, signals a structural realignment in feedstock sourcing as renewable chemistries enter commercial deployment. Early adopters in Europe and Japan already certify mass-balance routines to capture brandowner premiums, while Asian producers erect greenfield units adjacent to biomass supply corridors.
Over the medium term, pesticide and pharmaceutical intermediates derived from 2,4- and 2,6-xylidine will preserve niche demand despite regulatory concerns around toxicology. Solvent applications shrink in absolute tonnage but exhibit value resilience where specialty electronics and pharmaceutical cleaning require meta-xylene's narrow boiling range. Taken together, the application mix is migrating from bulk solvent dependency toward higher-margin resin and specialty chemical use, elevating overall profitability despite moderate headline growth.
Complete Report Scope:
- By Application
- Isophthalic Acid
- 2,4- and 2,6-Xylidine
- Solvents
- Other Applications (Pesticide Intermediates, etc.)
- By End-user Industry
- Construction and Infrastructure
- Packaging
- Automotive and Transportation
- Pharmaceuticals and Agrochemicals
- Electrical and Electronics
- By Purity/Grade
- Greater than or equal to 99.9 % MX (High-Purity)
- Industrial-Grade MX
- Mixed Xylenes Stream
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific captured 52.98% of global volumes in 2025 and is forecast to clock a 5.32% CAGR through 2031, driven by vertically integrated complexes across China and India that harness feedstock flexibility and scale economics. China's Zhoushan aromatics hub and Guangdong CNOOC-Shell joint venture each broaden regional self-sufficiency, curbing import requirements from the United States and Europe. India's USD 87 billion petrochemical blueprint seeks to raise domestic xylene capacity to 5.5 million t by 2035, securing raw material availability for downstream polyester, coatings, and pharma corridors. Japan and South Korea confront structural margin pressure as Chinese exports intensify competition, spurring these economies to pivot toward high-purity specialties and differentiated formulations.
North America retains strategic significance through superior separation technologies, abundant shale-derived naphtha and proximity to a vast coatings customer base. However, upward pressure on energy costs and tightening environmental compliance increase operating expenditure. Chevron's potential USD 15 billion acquisition of Phillips 66's CPChem stake underscores the region's consolidation trajectory as companies chase scale and feedstock integration benefits. Mexico's emerging automotive value chain stimulates solvent and resin demand but relies heavily on United States imports, illustrating the importance of the USMCA's tariff stability.
Europe confronts the steepest operating challenges, with high utility costs and stringent carbon policies discouraging fresh investment in commodity aromatics. The European Green Deal's evolving carbon-border adjustment mechanism may partially shield domestic output yet adds administrative complexity. Shell's announcement to exit base chemicals by 2030 typifies how international energy majors reallocate capital toward LNG and renewables. Remaining European producers emphasize bio-based isophthalic acid and circular PET feedstocks, capitalizing on regulatory incentives for climate-neutral materials.
- Avantor, Inc.
- Chevron Phillips Chemical Company LLC
- Exxon Mobil Corporation
- Hengli Petrochemical
- Honeywell International Inc.
- JXTG Nippon Oil & Energy
- LOTTE Chemical CORPORATION
- MITSUBISHI GAS CHEMICAL COMPANY, INC.
- Moeve
- Shell Chemicals
- S-OIL CORPORATION
- Suzhou Jiutai Group Co., Ltd.
- Vizag Chemicals
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand for isophthalic acid in PET and UPR production
- 4.2.2 Shift toward high-solids/low-VOC industrial coatings
- 4.2.3 Capacity expansions in integrated PX-MX aromatics complexes
- 4.2.4 Increasing demand from paints and coatings sector
- 4.2.5 Expansion of the automotive sector
- 4.3 Market Restraints
- 4.3.1 Toxicological and flammability profile driving stricter exposure limits
- 4.3.2 Crude-oil price volatility cascading to aromatics spreads
- 4.3.3 Capital-intensive isomer separation technology deterring newcomers
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Application
- 5.1.1 Isophthalic Acid
- 5.1.2 2,4- and 2,6-Xylidine
- 5.1.3 Solvents
- 5.1.4 Other Applications (Pesticide Intermediates, etc.)
- 5.2 By End-user Industry
- 5.2.1 Construction and Infrastructure
- 5.2.2 Packaging
- 5.2.3 Automotive and Transportation
- 5.2.4 Pharmaceuticals and Agrochemicals
- 5.2.5 Electrical and Electronics
- 5.3 By Purity/Grade
- 5.3.1 Greater than or equal to 99.9 % MX (High-Purity)
- 5.3.2 Industrial-Grade MX
- 5.3.3 Mixed Xylenes Stream
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Avantor, Inc.
- 6.4.2 Chevron Phillips Chemical Company LLC
- 6.4.3 Exxon Mobil Corporation
- 6.4.4 Hengli Petrochemical
- 6.4.5 Honeywell International Inc.
- 6.4.6 JXTG Nippon Oil & Energy
- 6.4.7 LOTTE Chemical CORPORATION
- 6.4.8 MITSUBISHI GAS CHEMICAL COMPANY, INC.
- 6.4.9 Moeve
- 6.4.10 Shell Chemicals
- 6.4.11 S-OIL CORPORATION
- 6.4.12 Suzhou Jiutai Group Co., Ltd.
- 6.4.13 Vizag Chemicals
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


