

|
시장보고서
상품코드
2121701
유럽의 열가소성 엘라스토머 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Thermoplastic Elastomers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
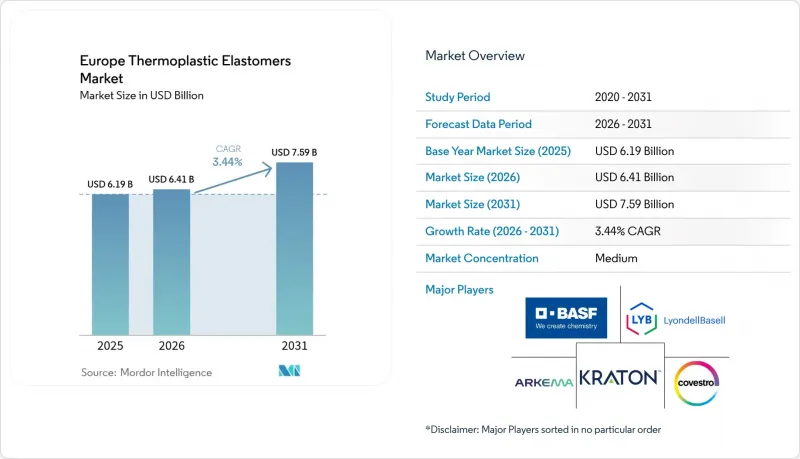
에 의하면, 유럽의 열가소성 엘라스토머 시장 규모는 2025년에 61억 9,000만 달러로 평가되었고, 2026년 64억 1,000만 달러에서 성장하여 2031년까지 75억 9,000만 달러에 이를 것으로 추정되고 있습니다.
예측 기간(2026-2031년) 동안 연평균 성장률(CAGR)은 3.44%를 기록할 전망입니다.
본 보고서는 제품 유형(스티렌계 블록 코폴리머, 열가소성 올레핀, 열가소성 폴리우레탄 등), 용도(자동차 및 운송, 건축 및 건설, 신발·스포츠 용품, 전기 및 전자, 의료 등), 지역(독일, 영국, 프랑스 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽의 열가소성 엘라스토머 시장 동향과 인사이트
EV가 주도하는 유럽 자동차 부품 업계의 경량화 붐
전기자동차 아키텍처에서는 배터리의 무게를 상쇄하기 위해 총 중량의 15-20%를 감량해야 합니다. 이에 따라 각 OEM 업체들은 다이캐스팅 금속이나 가황 고무 대신 재활용이 가능한 열가소성 엘라스토머를 우선적으로 채택하도록 자재 목록을 재검토하고 있습니다. 폭스바겐은 EPDM에 비해 30%의 경량화를 실현하고, 120°C의 오일에 노출되어도 견딜 수 있는 산토프렌 TPV 소재의 엔진 커버를 지정하고 있습니다. 콘티넨탈 AG는 발포 사출 성형 TPE로 제작된 도어 씰을 공동 개발하여 차량 1대당 200g의 경량화를 실현했습니다. 이 겉보기에는 미미한 수치도 볼프스부르크의 생산 대수로 환산하면 연간 400t의 경량화에 해당합니다. 프랑스와 스페인에서는 스텔란티스와 르노가 2027년까지 EU 배터리 규정에 명시된 ‘50 kg CO2e/kWh 미만’이라는 탄소 발자국 기준치를 충족하기 위해 현지에서 조달한 TPE 재질의 개스킷을 채택하고 있습니다. ISO 14040에 기반한 수명 주기 감사가 조달 결정에 영향을 미치게 되면서, 이에 따라 중소규모의 컴파운더들은 추적성 시스템 도입 자금을 확보할 수 있는 합병을 검토하고 있습니다.
건축용 실링재 분야에서 PVC 및 EPDM의 급속한 대체
독일 및 북유럽 각국의 창문·문 제조업체들은 할로겐계 폴리머 사용을 불이익 요인으로 간주하는 ‘DGNB 골드’ 및 ‘BREEAM 엑설런트’ 인증 요건을 충족하기 위해 TPE 프로파일로 전환을 추진하고 있습니다. TPE-S 및 TPE-V는 ISO 4892-2에 기반한 5,000시간의 크세논 아크 시험 후에도 200% 이상의 성장률을 유지하며, 가소제 유출 없이 PVC와 동등한 내후성을 실현하고 있습니다. 2025년부터 시행되는 영국의 ‘퓨처 홈스 스탠다드(Future Homes Standard)’에서는 50 Pa에서의 기밀성을 5 m³/h/m² 미만으로 유지할 것을 요구하고 있습니다. 공압출 성형된 TPE 코너 키는 이 목표를 달성함과 동시에, 1유닛당 시공 시간을 15분 단축합니다. Rehau사와 Deceuninck사는 40-50%의 산업 폐기물 유래 재생재를 배합하여, EPDM의 가격 변동을 완화하는 순환형 경제성을 높이고 있습니다. 곧 시행될 EU 건설 제품 규정 부속서 ZA에서는 환경 제품 선언(EPD) 제출이 의무화될 예정이며, 이에 따라 프랑크푸르트와 암스테르담의 파사드 시공 업체들에서 TPE의 채택이 가속화될 것입니다.
원유 가격에 연동되는 스티렌 및 이소시아네이트의 가격 변동
브렌트 원유 가격이 분기 내 20달러/배럴 이상 변동하면, 스티렌과 부타디엔은 나프타 스프레드에 거의 연동하여 움직이며, TPE-S 생산 비용의 최대 60%를 차지하는 원료 비용을 상승시킵니다. 북서유럽의 스티렌 현물 가격은 2024년 1월의 1,400달러/톤에서 10월까지 1,100달러/톤으로 21% 하락하여, INEOS Styrolution과 같은 일체형 생산 기업의 이익률을 압박했습니다. 이 회사는 여름 유지보수 기간 동안 앤트워프의 생산 라인을 중단했습니다. 2024년 2분기 BASF에서 발생한 MDI 불가항력 사태로 인해 이소시아네이트 가격은 18% 상승했고, TPU 압출 성형 업체에는 6주간의 리드타임이 발생했습니다. 헤지 수단이나 자체 조달 원료를 보유하지 않은 중소 복합재 제조업체들은 200-300 베이시스 포인트의 이익률을 희생할 수밖에 없었으며, 그 결과 더 많은 가족 경영 공장이 사모펀드에 의한 인수 및 통합 대상이 되었습니다.
부문별 분석
2025년, 스티렌계 블록 코폴리머는 유럽의 열가소성 엘라스토머 시장에서 38.92%의 점유율을 차지하며, 접착제, 신발, 부드러운 촉감의 가전 부품용 배합을 뒷받침했습니다. 열가소성 폴리우레탄은 2031년까지 연평균 성장률(CAGR) 3.56%를 나타낼 것으로 예측되며,의료 분야 및 고급 자동차 고객들이 쇼어 A 경도 80 이상의 수준에서 내마모성 및 내유성을 중시하고 있기 때문에 유럽의 열가소성 엘라스토머 시장에서의 점유율을 확대할 것으로 전망됩니다. 열가소성 올레핀(TPO)은 프라이머 없이 도장이 가능하다는 점 때문에 외장 패널의 대표 소재로 자리매김하고 있습니다. 그러나 아시아산 수입품은 유럽산보다 10-15% 저렴하여 현지 제조업체의 이익률을 압박하고 있습니다.
TPV로 분류되는 엘라스토머 합금은 ASTM D471에 따라 오일에 의한 팽윤율을 15% 이내로 억제해야 하는 보닛 내부 씰링재 시장을 독점하고 있습니다. 그러나 150°C 이상에서 연속 사용이 요구되는 전동 파워트레인용 개스킷 시장에서는 실리콘계 경쟁 제품에 의해 시장 점유율이 잠식되고 있습니다. 코폴리에스테르 및 폴리아미드계 엘라스토머는 고온용 튜브라는 틈새 시장을 공략하고 있지만, 습기에 민감하고 가공 비용과 관련된 과제에 직면해 있습니다. ISO 1629에 기반한 표시 제도로 인해 상표에 대한 제약이 해소되고 조달 팀이 신속하게 공급업체를 변경할 수 있게 됨에 따라, 유럽의 열가소성 엘라스토머 시장 전체에 가격 압박이 가중되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the Europe thermoplastic elastomers market size was valued at USD 6.19 billion in 2025 and estimated to grow from USD 6.41 billion in 2026 to reach USD 7.59 billion by 2031, at a CAGR of 3.44% during the forecast period (2026-2031).
This report is Segmented by Product Type (Styrenic Block Copolymer, Thermoplastic Olefin, Thermoplastic Polyurethane, and More), Application (Automotive and Transportation, Building and Construction, Footwear and Sporting Goods, Electrical and Electronics, Medical, and More), and Geography (Germany, United Kingdom, France, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Thermoplastic Elastomers Market Trends and Insights
EV-Driven Lightweighting Boom in European Auto Parts
Electric-vehicle architectures must shed 15-20% of their mass to counterbalance the weight of the battery, so OEMs are revising their material lists to favor recyclable thermoplastic elastomers over die-cast metal and vulcanized rubber. Volkswagen specifies Santoprene TPV engine covers that save 30% versus EPDM while handling 120°C oil exposure. Continental AG co-developed foam-injection TPE door seals, weighing 200 g less per vehicle. This seemingly small figure translates to 400 t of annual weight reduction at Wolfsburg volumes. In France and Spain, Stellantis and Renault source localized TPE gaskets to meet EU Battery Regulation carbon footprint thresholds of below 50 kg CO2e/kWh by 2027. ISO 14040 life-cycle audits now influence sourcing decisions, prompting smaller compounders to consider mergers that can finance traceability systems.
Rapid Substitution of PVC and EPDM in Building Seals
Window and door makers across Germany and the Nordics are transitioning to TPE profiles to meet the requirements of DGNB Gold and BREEAM Excellent labels, which penalize the use of halogenated polymers. TPE-S and TPE-V retain elongation above 200% after 5,000 hours of xenon-arc testing per ISO 4892-2, matching the weatherability of PVC without plasticizer bleed. The UK Future Homes Standard, effective from 2025, requires airtightness of below 5 m3/h/m2 at 50 Pa; co-extruded TPE corner keys meet this target while reducing installation time by 15 minutes per unit. Rehau and Deceuninck incorporate 40-50% post-industrial regrind, adding circularity that cushions EPDM price swings. The forthcoming EU Construction Products Regulation Annex ZA will require Environmental Product Declarations, thereby accelerating the uptake of TPE among facade contractors in Frankfurt and Amsterdam.
Volatile Crude-Linked Styrene and Isocyanate Prices
When Brent shifts more than USD 20/bbl inside a quarter, styrene and butadiene follow naphtha spreads almost in lockstep, driving feedstock costs that represent up to 60% of TPE-S production. Spot styrene in Northwest Europe slid 21% from USD 1,400/t in January 2024 to USD 1,100/t by October, pinching margins for integrated players such as INEOS Styrolution, which idled lines at Antwerp during summer maintenance. A BASF force-majeure event on MDI in Q2 2024 inflated isocyanate prices by 18% and left TPU extruders with six-week lead times. Smaller compounders that lack hedge tools or captive feedstocks surrendered 200-300 bps margin, pushing more family-owned plants into private-equity roll-ups.
Other drivers and restraints analyzed in the detailed report include:
- Medical-Grade TPU Demand from Catheter Extruders
- Foam-Injection TPE for Low-Density Interior Trims
- Tight EU REACH Limits on Phthalates and Styrene Monomer
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Styrenic block copolymers held 38.92% of the Europe thermoplastic elastomers market in 2025, underpinning formulations for adhesives, footwear, and soft-touch appliance parts. Thermoplastic polyurethanes are projected to post a 3.56% CAGR to 2031, increasing their share of the European thermoplastic elastomers market size as medical and premium automotive customers value abrasion and oil resistance at 80+ Shore A hardness levels. Thermoplastic olefins remain staples for exterior fascias due to their paintability without primers; however, Asian imports price them 10-15% below European output, thereby trimming margins for local producers.
Elastomeric alloys, positioned as TPVs, dominate under-hood seals that must limit oil swell to 15% per ASTM D471; however, silicone rivals are eroding their share in e-powertrain gaskets that require continuous use above 150 °C. Copolyesters and polyamide elastomers address high-temperature tubing niches, but they face hurdles related to moisture sensitivity and processing costs. ISO 1629 labeling has stripped away trade-name lock-in, letting procurement teams switch suppliers rapidly and sparking price pressure across the Europe thermoplastic elastomers market.
Complete Report Scope:
- By Product Type
- Styrenic Block Copolymer (TPE-S)
- Thermoplastic Olefin (TPE-O)
- Elastomeric Alloy (TPE-V / TPV)
- Thermoplastic Polyurethane (TPU)
- Thermoplastic Copolyester
- Thermoplastic Polyamide
- By Application
- Automotive and Transportation
- Building and Construction
- Footwear and Sporting Goods
- Electrical and Electronics
- Medical
- Household Appliances
- HVAC
- Adhesives, Sealants and Coatings
- Others
- By Geography
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Apar Industries Ltd.
- Arkema
- Avient Corporation
- BASF
- Celanese Corporation
- Covestro AG
- Covestro AG
- DSM
- DuPont
- Evonik Industries AG
- Exxon Mobil Corporation
- Grupo Dynasol
- Huntsman International LLC
- KRATON CORPORATION
- KURARAY CO. LTD.
- LANXESS
- LG Chem
- LyondellBasell Industries Holdings BV
- Mitsubishi Chemical Corporation
- Mitsui Chemicals Inc.
- SABIC
- Sirmax SpA
- Sumitomo Chemical Co. Ltd.
- The Lubrizol Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EV-driven lightweighting boom in European auto parts
- 4.2.2 Rapid substitution of Polyvinyl Chloride and EPDM in building seals
- 4.2.3 Medical-grade Thermoplastic-Urethane demand from catheter extruders
- 4.2.4 Foam-injection TPE for low-density interior trims
- 4.2.5 OEM take-back mandates fueling PCR-blend TPE usage
- 4.3 Market Restraints
- 4.3.1 Volatile crude-linked styrene and isocyanate prices
- 4.3.2 Tight EU REACH limits on phthalates and styrene monomer
- 4.3.3 Competition from high-temp silicones in e-mobility
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products and Services
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Styrenic Block Copolymer (TPE-S)
- 5.1.2 Thermoplastic Olefin (TPE-O)
- 5.1.3 Elastomeric Alloy (TPE-V / TPV)
- 5.1.4 Thermoplastic Polyurethane (TPU)
- 5.1.5 Thermoplastic Copolyester
- 5.1.6 Thermoplastic Polyamide
- 5.2 By Application
- 5.2.1 Automotive and Transportation
- 5.2.2 Building and Construction
- 5.2.3 Footwear and Sporting Goods
- 5.2.4 Electrical and Electronics
- 5.2.5 Medical
- 5.2.6 Household Appliances
- 5.2.7 HVAC
- 5.2.8 Adhesives, Sealants and Coatings
- 5.2.9 Others
- 5.3 By Geography
- 5.3.1 Germany
- 5.3.2 United Kingdom
- 5.3.3 France
- 5.3.4 Italy
- 5.3.5 Spain
- 5.3.6 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Apar Industries Ltd.
- 6.4.2 Arkema
- 6.4.3 Avient Corporation
- 6.4.4 BASF
- 6.4.5 Celanese Corporation
- 6.4.6 Covestro AG
- 6.4.7 Covestro AG
- 6.4.8 DSM
- 6.4.9 DuPont
- 6.4.10 Evonik Industries AG
- 6.4.11 Exxon Mobil Corporation
- 6.4.12 Grupo Dynasol
- 6.4.13 Huntsman International LLC
- 6.4.14 KRATON CORPORATION
- 6.4.15 KURARAY CO. LTD.
- 6.4.16 LANXESS
- 6.4.17 LG Chem
- 6.4.18 LyondellBasell Industries Holdings BV
- 6.4.19 Mitsubishi Chemical Corporation
- 6.4.20 Mitsui Chemicals Inc.
- 6.4.21 SABIC
- 6.4.22 Sirmax SpA
- 6.4.23 Sumitomo Chemical Co. Ltd.
- 6.4.24 The Lubrizol Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


