

|
시장보고서
상품코드
2121883
광학 코팅 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Optical Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
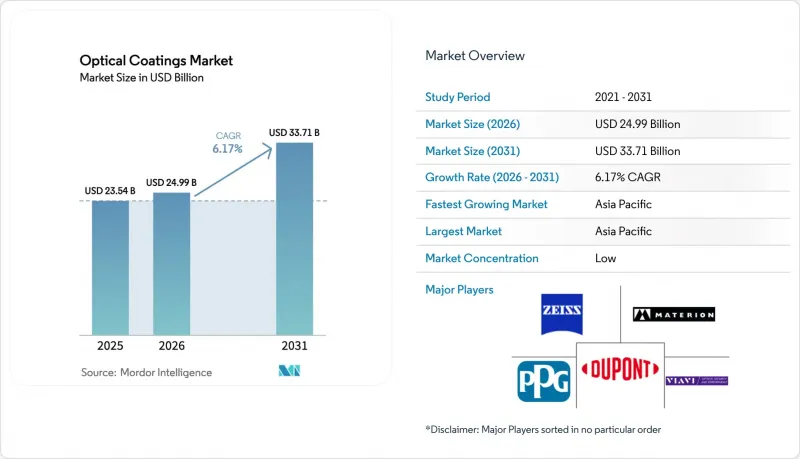
에 의하면, 광학 코팅 시장 규모는 2025년에 235억 4,000만 달러로 평가되었고, 2026년 249억 9,000만 달러에서 2031년까지 337억 1,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.17%를 나타낼 전망입니다.
본 보고서는 제품 유형별(광학 필터, 반사 방지 코팅 등), 성막 기술별(화학 기상 증착법, 이온 빔 스퍼터링 등), 최종 사용자 산업별(항공우주 및 방위, 일렉트로믹스 및 반도체 등), 지역별(아시아태평양, 북미, 유럽 등)로 분류되어 있습니다. 시장 전망은 매출액(달러) 기준으로 제시되어 있습니다.
세계의 광학 코팅 시장 동향 및 인사이트
태양광 등급 반사 방지 필름이 양면 수광형 태양광 모듈의 LCOE를 대폭 절감
양면에 반사 방지 코팅이 적용된 양면 수광형 태양광 모듈은 현재 셀 효율이 25%를 초과하며, 일사량이 많은 지역에서 균등화 발전 원가(LCOE)를 1kW시당 0.03달러 미만으로 낮추고 있습니다. 2025년에 발표된 Tongwei Solar사의 25.5% 터널 산화막 패시베이션 접점 셀은 300-1,200나노미터 파장 영역에서 반사를 최소화하는 최적화된 표면 및 뒷면 코팅을 통해 0.8퍼센트 포인트의 효율 향상을 실현했습니다. 출력 향상으로 시스템 전체 비용이 절감되었으며, 인도 국립 태양에너지 연구소는 사막 기후에서 양면 수광 어레이의 연간 발전량이 18% 증가할 것이라고 지적했습니다. 모듈 제조업체들은 제조 공정의 독창성을 확보하기 위해 코팅 공정을 자체 생산으로 전환하여 독립 코팅 업체에 대한 공급을 위축시키는 한편, 기가와트급 생산 라인 전체에서 플라즈마 증폭 CVD 설비에 대한 투자를 상각할 수 있는 기업을 우선적으로 선정하고 있습니다.
AR/VR용 메타코팅 : 소비자용 헤드셋용 AR/VR 도파관 구현
메타서피스 도파관은 부피가 큰 다층 스택 대신 파장 이하의 나노 구조를 채택함으로써 광학 엔진의 두께를 5mm 미만으로 얇게 만듭니다. Meta Platforms는 2024년에 효율 92%의 이산화티타늄 설계를 입증했으며, 이에 이어 삼성리서치는 2025년에 홀로그래픽 버전을 발표하여 안경과 병행 사용이 가능한 50도의 시야각을 실현했습니다. 메타 코팅에 대한 지적 재산권을 확보하고 이온 빔 스퍼터링 전문 기업과 제휴하는 브랜드는 향후 등장할 소비자용 전자 기기의 부품 구성을 주도하게 될 것입니다. 한편, 기존 AR 벤더들은 나노 제조 역량에 투자하지 않는 한 시대에 뒤처질 위험이 있습니다.
인듐-주석 산화물(ITO) 공급 취약성
미국 지질조사국(USGS)에 따르면, 정제 인듐의 60%를 중국이 장악하고 있으며, 미국은 2024년에 필요량의 100%를 수입했습니다. 2023년부터 2024년에 걸쳐 가격이 35% 급등한 것은 수출 할당량 축소를 반영한 것이며, 반면 재활용을 통한 스크랩 회수율은 15% 미만에 그치고 있습니다. 각 디스플레이 제조업체들은 그래핀이나 은 나노와이어 등의 대체 기술에 자금을 투자하고 있지만, 대량 생산 규모에서 ITO의 전도성과 투명성의 균형을 따라잡을 만한 기술은 아직 없습니다. 삼성디스플레이는 ITO를 사용하지 않는 기술 연구에 1억 2,000만 달러를 배정했으나, 2028년 이전에 상용화될 가능성은 낮으며, 코팅 제조업체들은 원자재 가격 급등에 계속 노출된 상태입니다.
부문 분석
2025년에는 반사 방지 코팅이 매출의 37.94%를 차지한 것으로 평가되었으며, 이 부문은 2031년까지 연평균 성장률(CAGR) 6.46%로 확대될 것으로 전망됩니다. 양면형 태양광 유리에 사용되는 양면 코팅층과 OLED 패널에 사용되는 저반사 코팅층이 소비량의 3분의 2 가까이를 차지하고 있습니다. 인듐 공급 제약에 직면해 있는 투명 전도성 코팅은 마이크로LED 헤드업 디스플레이 및 웨어러블 기기 시장이 성숙해짐에 따라 여전히 한 자릿수 중반대의 성장률을 유지하고 있습니다. 고반사 미러 코팅은 레이저 시스템용 특수 용도로만 제한되어 있지만, 빔 스플리터는 산업 자동화 분야의 머신 비전 카메라를 뒷받침하고 있습니다. 바이오포토닉스 및 양자 광학용 특수 필터는 50% 이상의 매출 총이익률을 유지하고 있습니다.
시장의 모멘텀은 광대역 AR 스택에서 두께 10나노미터 미만이며 반사율을 0.5% 미만으로 낮추는 파장 선택형 메타표면 필름으로 이동하고 있습니다. 삼성리서치는 2024년에 플렉서블 유형을 발표했으며, 도쿄 일렉트론은 300mm 웨이퍼를 시간당 20장의 처리량으로 패터닝할 수 있는 나노 임프린트 장비의 양산화를 추진하고 있습니다. CVD나 스퍼터링에만 의존하는 코팅 장비는 50나노미터 미만의 패턴 형성 능력이 부족하며, 아시아의 팹들이 다층막 제조 기술을 자체 생산화함에 따라 상품화 위험에 직면하고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 34.78%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 8.11%로 확대되어 이 기간 동안 광학 코팅 시장 규모를 30억 달러 이상으로 끌어올릴 전망입니다. 중국, 한국, 일본은 OLED 생산, 태양전지 모듈 조립, 정밀 계측 기기 제조를 통해 이 지역의 주도적 위치를 확립하고 있습니다. 인도 국립 태양에너지 연구소의 보고서에 따르면, 국내에서 코팅된 양면 유리는 모듈 비용을 와트당 0.02달러 절감하여 국내 코팅 라인에 대한 투자를 촉진하고 있습니다. 동남아시아는 각 브랜드가 중국에 대한 의존도를 분산시키는 가운데 제2의 거점으로 부상하고 있지만, 반도체 인프라가 제한적이어서 포토닉 등급의 성장은 제약을 받고 있습니다.
군용 광학 기기 및 포토닉스 집적 회로가 북미 광학 코팅 시장의 성장을 주도하고 있습니다. 미국 국방부는 2024년에 전기광학 및 적외선 시스템에 18억 달러를 배정하여, 가혹한 환경에서도 견딜 수 있는 이온 빔 코팅에 대한 수요를 뒷받침했습니다. 매터리온(Materion)과 코히런트(Coherent)는 기밀 프로그램에서의 실적을 바탕으로 계약을 수주하고 있는 반면, 캐나다의 포토닉스 클러스터는 코팅 개발을 위해 캐나다 국립연구위원회의 보조금을 활용하고 있습니다. 멕시코에서는 포드와 GM 공장에 제품을 공급하는 PPG가 트라스칼라에서 4,500만 달러 규모의 확장 공사를 진행하는 등 자동차용 코팅 프로젝트가 잇따르고 있습니다.
독일, 프랑스, 영국이 자동차 및 산업용 광학 분야를 주도하고 있어, 유럽은 세계 광학 코팅 시장에서 큰 점유율을 차지하고 있습니다. 쇼트(Schott)와 자이스(Zeiss)는 EU의 화학 물질 규제 강화에 따라 PFAS가 포함되지 않은 컨포멀 코팅을 공급하고 있습니다. 중동 및 아프리카에서는 사우디아라비아의 NEOM과 같은 태양광 발전 메가 프로젝트로 인해 광학 코팅 수요가 증가하고 있습니다. 이 프로젝트에서는 양면 코팅이 필요한 5기가와트급 양면 수광형 모듈이 채택되었습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the optical coatings market size was valued at USD 23.54 billion in 2025 and is estimated to grow from USD 24.99 billion in 2026 to reach USD 33.71 billion by 2031, at a CAGR of 6.17% during the forecast period (2026-2031).
This report is Segmented by Product Type (Optical Filter, Anti-Reflective, and More), Deposition Technology (Chemical Vapor Deposition, Ion-Beam Sputtering, and More), End-User Industry (Aerospace and Defense, Electronics and Semiconductors, and More), and Geography (Asia-Pacific, North America, Europe, and More). The Market Forecasts are Provided in Terms of Revenue (USD).
Global Optical Coatings Market Trends and Insights
Solar-Grade Anti-Reflective Films Slash LCOE in Bifacial PV Modules
Bifacial photovoltaic modules equipped with dual-sided anti-reflective stacks now exceed 25% cell efficiency, pushing the levelized cost of energy below USD 0.03 per kilowatt-hour in high-irradiance zones. Tongwei Solar's 25.5% tunnel-oxide passivated-contact cell, announced in 2025, attributed 0.8 percentage points of gain to optimized front- and rear-surface coatings that minimize reflection from 300 to 1,200 nanometers. Higher output cuts balance-of-system costs, prompting India's National Institute of Solar Energy to note 18% greater annual yield for bifacial arrays in desert climates. Module manufacturers are internalizing coating steps to secure stack recipes, tightening supply for independent coaters, and favoring players that amortize plasma-enhanced CVD capital across gigawatt-class lines.
AR/HR Meta-Coatings Enabling AR/VR Waveguides for Consumer Headsets
Metasurface waveguides replace bulky multilayer stacks with sub-wavelength nanostructures that slim optical engines below 5 millimeters. Meta Platforms documented a 92%-efficient titanium-dioxide design in 2024, and Samsung Research followed with a holographic variant in 2025, delivering a 50-degree field of view compatible with eyeglasses. Brands that secure meta-coating intellectual property and align with ion-beam sputtering specialists will control forthcoming consumer-electronics bill of materials, whereas legacy AR vendors face obsolescence unless they invest in nano-fabrication capacity.
Indium-Tin-Oxide Supply Vulnerability
China controls 60% of refined indium, and the United States imported 100% of its need in 2024 according to the US Geological Survey. A 35% price jump in 2023-2024 reflects tightened export quotas, while recycling captures less than 15% of scrap. Display makers fund alternatives such as graphene and silver nanowires, yet none match ITO's conductivity-transparency balance at mass scale. Samsung Display allocated USD 120 million to ITO-free research, but commercial release is unlikely before 2028, leaving coaters exposed to raw-material inflation.
Other drivers and restraints analyzed in the detailed report include:
- 6G-Ready Ultra-Low-Loss Filter Stacks for Photonic Integrated Circuits
- Military Hyperspectral Imaging Demand for Broad-Band Filter Coatings
- Stricter PFAS Bans Hitting Fluoride-Based Hard Coats
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Anti-reflective coatings commanded 37.94% of revenue in 2025, and the segment is projected to expand at a 6.46% CAGR through 2031. Dual-sided stacks on bifacial solar glass and low-reflectance layers on OLED panels account for nearly two-thirds of consumption. Transparent conductive coatings, hindered by indium constraints, still post mid-single-digit growth as microLED head-up displays and wearables mature. High-reflective mirror coatings remain specialized for laser systems, while beam splitters support machine-vision cameras in industrial automation. Specialty filters servicing biophotonics and quantum optics sustain gross margins above 50%.
Momentum is shifting from broadband AR stacks toward wavelength-selective metasurface films that reduce reflection below 0.5% with sub-10-nanometer thickness. Samsung Research unveiled a flexible variant in 2024, and Tokyo Electron is scaling nano-imprint tools that pattern 300-millimeter wafers at 20-per-hour throughput. Coaters tied solely to CVD or sputtering lack sub-50-nanometer pattern capabilities and risk commoditization as Asian fabs internalize multilayer recipes.
Complete Report Scope:
- By Product Type
- Optical Filter Coatings
- Anti-reflective Coatings
- Transparent Conductive Coatings
- High-Reflective Mirror Coatings
- Beam Splitter Coatings
- Others
- By Deposition Technology
- Chemical Vapor Deposition
- Ion-beam Sputtering
- Plasma Sputtering
- Atomic Layer Deposition
- Sub-wavelength Structured Surfaces
- By End-user Industry
- Aerospace and Defense
- Electronics and Semiconductors
- Telecommunications
- Healthcare
- Solar
- Automotive
- Others
- By Geography
- Asia-Pacific
- China
- Japan
- South Korea
- India
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordic Countries
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 34.78% of 2025 revenue and is advancing at an 8.11% CAGR to 2031, adding more than USD 3 billion to the optical coatings market size during the period. China, South Korea, and Japan anchor regional dominance through OLED production, solar module assembly, and precision metrology toolmaking. India's National Institute of Solar Energy reported that locally coated bifacial glass trims module costs by USD 0.02 per watt, stimulating domestic coating-line investment. Southeast Asia emerges as a secondary hub as brands diversify away from China, although limited semiconductor infrastructure restrains photonic-grade growth.
Military optics and photonic integrated circuits propel North America's optical coatings market growth. The US Department of Defense allocated USD 1.8 billion in 2024 for electro-optical and infrared systems, driving demand for ion-beam coatings that survive harsh environments. Materion and Coherent leverage classified-program credentials to secure contracts, while Canada's photonics cluster leverages National Research Council grants for coating development. Mexico attracts automotive-coating projects such as PPG's USD 45 million expansion in Tlaxcala, serving Ford and GM plants.
Europe accounts for a significant share of the global optical coatings market as Germany, France, and the United Kingdom dominate automotive and industrial optics. Schott and Zeiss supply PFAS-free conformal layers following the EU's tightened chemical regulations. The Middle East and Africa are witnessing rising demand for optical coatings due to solar mega-projects like Saudi Arabia's NEOM, which incorporates 5 gigawatts of bifacial modules requiring dual-side coatings.
- 3M
- Abrisa Technologies
- AccuCoat Inc.
- Artemis Optical Ltd
- DuPont
- Edmund Optics Inc.
- Inrad Optics
- Materion Corporation
- Newport Corporation
- Nippon Sheet Glass Co., Ltd.
- Optical Coatings Technologies
- PPG Industries Inc.
- Quantum Coating Inc.
- Reynard Corporation
- Schott AG
- SIGMAKOKI CO., LTD
- VIAVI Solutions Inc.
- Zeiss International
- Zygo
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Solar-grade anti-reflective (AR) films slash LCOE in bifacial PV modules
- 4.2.2 AR/HR "meta-coatings" enabling AR/VR waveguides for consumer headsets
- 4.2.3 6G-ready ultra-low-loss filter stacks for photonic integrated circuits
- 4.2.4 Military hyperspectral imaging demand for broad-band filter coatings
- 4.2.5 Mainstream demand surge from OLED/µLED displays
- 4.3 Market Restraints
- 4.3.1 Indium-tin-oxide (ITO) supply vulnerability
- 4.3.2 Stricter PFAS bans hitting fluoride-based hard coats
- 4.3.3 CAPEX intensity of atomic-layer deposition (ALD) lines
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Optical Filter Coatings
- 5.1.2 Anti-reflective Coatings
- 5.1.3 Transparent Conductive Coatings
- 5.1.4 High-Reflective Mirror Coatings
- 5.1.5 Beam Splitter Coatings
- 5.1.6 Others
- 5.2 By Deposition Technology
- 5.2.1 Chemical Vapor Deposition
- 5.2.2 Ion-beam Sputtering
- 5.2.3 Plasma Sputtering
- 5.2.4 Atomic Layer Deposition
- 5.2.5 Sub-wavelength Structured Surfaces
- 5.3 By End-user Industry
- 5.3.1 Aerospace and Defense
- 5.3.2 Electronics and Semiconductors
- 5.3.3 Telecommunications
- 5.3.4 Healthcare
- 5.3.5 Solar
- 5.3.6 Automotive
- 5.3.7 Others
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 South Korea
- 5.4.1.4 India
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Nordic Countries
- 5.4.3.7 Russia
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 Abrisa Technologies
- 6.4.3 AccuCoat Inc.
- 6.4.4 Artemis Optical Ltd
- 6.4.5 DuPont
- 6.4.6 Edmund Optics Inc.
- 6.4.7 Inrad Optics
- 6.4.8 Materion Corporation
- 6.4.9 Newport Corporation
- 6.4.10 Nippon Sheet Glass Co., Ltd.
- 6.4.11 Optical Coatings Technologies
- 6.4.12 PPG Industries Inc.
- 6.4.13 Quantum Coating Inc.
- 6.4.14 Reynard Corporation
- 6.4.15 Schott AG
- 6.4.16 SIGMAKOKI CO., LTD
- 6.4.17 VIAVI Solutions Inc.
- 6.4.18 Zeiss International
- 6.4.19 Zygo
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


