

|
시장보고서
상품코드
2121957
아라미드 섬유 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Aramid Fiber - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 아라미드 섬유 시장 규모는 45억 2,000만 달러로 추정되고, 2025년 43억 달러에서 확대해, 2031년에는 57억 8,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 5.04%로 성장할 것으로 전망됩니다.
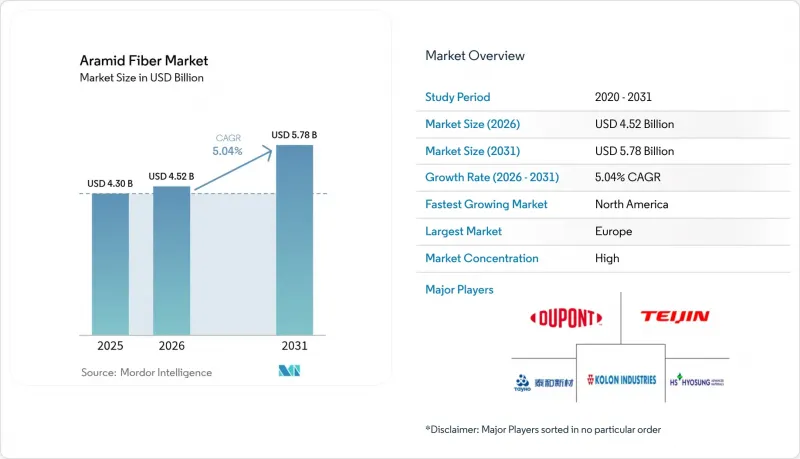
본 보고서에서는 시장을 제품 유형별(파라아라미드, 메타아라미드), 방적 공정별(습식 방적, 건습식 방적), 용도별(보안·보호 장비, 마찰재·브레이크재 등), 최종 사용자 산업별(안전·보호 장비, 항공우주 등), 지역별(아시아태평양, 북미, 유럽 등)로 분류하고 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 아라미드 섬유 시장 동향 및 인사이트
아시아 제조 거점에서의 PPE(개인보호구(PPE)) 안전 규제 강화
중국, 인도 및 동남아시아의 신흥 경제국에서 산업 안전 규정의 시행이 강화됨에 따라, 아라미드 강화 장갑, 헬멧, 내열 작업복의 주문이 증가하고 있습니다. 아라미드 복합 소재로 제작된 산업용 헬멧은 ABS 제품보다 내충격성이 37% 더 높으며, 이러한 성능 차이로 인해 공장 내 도입이 가속화되고 있습니다. 파라아라미드가 배합된 절단 방지 장갑은 레벨 5의 보호 성능을 갖추면서도 무게를 30% 줄여, 장시간 착용 시의 편안함을 향상시켰습니다. 메타아라미드를 배합한 난연성 작업복은 425°C에서도 구조적 무결성을 유지하며, 주조소나 석유화학 업계의 더욱 엄격한 안전 기준을 준수하고 있습니다. 그 결과, 이 지역에 제품을 공급하는 제조업체들은 아라미드 원사와 아라미드 원단의 조달량을 늘리고 있으며, 이는 아라미드 섬유 시장의 성장 추세를 뒷받침하고 있습니다.
EU의 그린 딜 : 아라미드로 보강된 경량 전기차 타이어 추진
유럽의 자동차 제조업체들은 전기차의 주행 거리를 연장하기 위해 차량 중량을 줄이는 타이어 재설계 프로그램을 가속화하고 있습니다. 아라미드로 보강된 타이어 카카스는 중량을 최대 25%까지 줄일 수 있으며, 이러한 경량화 효과는 그린 딜의 운송 부문 탈탄소화 목표와 직결됩니다. 1Kg의 경량화마다 0.7킬로미터의 주행 거리 향상이 예상되므로, OEM 각사는 폴리에스터나 스틸 코드 대신 아라미드를 채택하고 있습니다. 각 컴파운더 기업들은 구름 저항을 줄이면서도 내구성을 유지하는 아라미드 충전 고무 혼합물을 상품화하고 있으며, 이로 인해 유럽은 물론 조만간 북미에서도 아라미드 섬유 시장에 대한 수요가 더욱 높아지고 있습니다.
MPD 및 PPD 원료 가격 변동
원유 가격의 급격한 변동과 지역적인 공급 차질로 인해 MPD 및 PPD의 원가 곡선이 상승하고 있으며, 생산자의 이익률이 압박받고 장기 계약의 안정성이 위협받고 있습니다. 미국 상무부는 방향족 디아민을 지정학적으로 생산이 집중되어 있는 화학적으로 중요한 원료 중 하나로 꼽고 있어, 공급 안정성에 대한 리스크가 높아지고 있습니다. 각 제조업체는 바이오 유래 중간체나 아라미드 스크랩의 폐쇄형 회수 방안을 검토하며 이에 대응하고 있지만, 단기적인 가격 변동은 여전히 아라미드 섬유 시장의 성장세를 둔화시키고 있습니다.
부문 분석
파라아라미드 부문은 방탄 보호, 항공우주 및 마찰재 수요에 힘입어 2025년 아라미드 섬유 시장에서 64.35%라는 압도적인 점유율을 차지했습니다. 파라아라미드 원사는 3.8 GPa에 가까운 인장 강도를 발휘하여 방탄 조끼 및 항공기용 허니콤 구조재 분야에서 입지를 유지하고 있습니다. 미국의 국방 예산 증액과 자동차용 경량 복합재료에 대한 관심이 다시 고조됨에 따라, 아라미드 섬유 시장에서 파라아라미드의 안정적인 수요 전망이 확보되고 있습니다. Toray의 한국 거점에서의 3,000톤 생산 능력 증강 등 대규모 투자는 이 섬유 등급에 대한 자본 배분 규모를 여실히 보여주고 있습니다.
메타아라미드는 시장 규모는 작지만, 2031년까지 연평균 성장률(CAGR) 5.28%라는 가장 빠른 성장 궤도를 그리고 있습니다. 첨단 습식 방적 필라멘트는 현재 1,255 MPa의 인장 강도에 도달하며, 장기간 자외선에 노출된 후에도 90% 이상의 강도를 유지하기 때문에 송전선 커버 등 실외 용도로의 확대가 가능해졌습니다. 난연성 섬유, 단열지, 여과백에 적용되는 메타아라미드는 전자, 산업 안전, 환경 보호 분야의 열 안정성 요건을 충족합니다. 아시아 전역의 반도체 생산 능력 확대와 EU의 그린 전환 프로젝트를 배경으로, 메타아라미드의 아라미드 섬유 시장 규모는 꾸준히 확대될 것으로 예측되며, 가격뿐만 아니라 소재의 특성이 고객의 전환을 결정짓는 경쟁 환경이 형성되고 있습니다.
2025년에는 습식 방사가 아라미드 섬유 시장 점유율의 59.40%를 차지했으며, 연평균 성장률(CAGR) 5.71%로 시장 전체를 상회하는 성장을 이어가고 있습니다. 이 공정에서는 균일한 폴리머 응고가 가능하며, 절연지 및 여과재에 필수적인 높은 유전 안정성을 실현하는 균일하고 고밀도의 섬유를 생산합니다. 개선된 용매 재활용 모듈은 배출량과 비용을 절감하여, 지속가능성을 중시하는 최종 사용자들 사이에서도 채택을 촉진하고 있습니다. 습식 방사를 통한 아라미드 섬유 시장 규모는 전동화의 진전과 여과재 수요 증가에 따라 확대될 것으로 예측됩니다.
파라아라미드의 경우, 사슬의 배향에 의해 매우 높은 인장 특성이 나타나기 때문에 건식 및 습식 방적은 여전히 필수적입니다. 폴리이미드 유사체에 대한 실험실 시험에서는 최대 2.72 GPa의 인장 강도와 114GPa를 초과하는 탄성 계수가 확인되어, 향후 파라아라미드의 성능 향상 여지가 있음을 뒷받침하고 있습니다. 전체 시장 점유율은 작지만, 이 공정은 고급 방탄 섬유공급을 뒷받침하며 국방부 및 고급 스포츠 용품 브랜드 수요를 충족시키고 있습니다. 처리 효율 향상과 용매 회수 기술을 목표로 한 지속적인 생산 라인 업그레이드를 통해, 시장에서 이 공정이 차지하는 틈새 시장의 기여도는 앞으로도 유지될 것입니다.
지역별 분석
유럽은 2025년 매출의 34.65%를 차지하며 세계 시장의 중심이 되었습니다. 엄격한 산업안전법, ISO 준수 난연성 기준, 그리고 유럽연합(EU)의 그린 딜이 자동차 및 산업 분야에서의 고부가가치 제품 채택을 촉진하고 있습니다. 수출 지향적인 자동차 산업을 기반으로 하는 독일이 이 지역의 생산량 확대를 주도하는 한편, 프랑스와 네덜란드는 첨단 여과 기술 및 항공우주용 적층 소재를 전문으로 하고 있습니다. 전기차 배터리 공장에 대한 정부의 장려책은 폴리머 복합재료의 채택을 더욱 촉진하고 있습니다.
북미는 2026-2031년 5.21%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 미국의 아라미드 섬유 시장은 연방 정부의 국방 예산에 힘입어 파라아라미드 방탄 소재에 대한 지속적인 수요가 뒷받침되고 있는 반면, NASA와 민간 로켓 발사 사업자들은 메타아라미드 열 차폐막에 투자하고 있습니다. 미국의 통신 사업자들은 허리케인 피해를 입기 쉬운 지역의 공중 광섬유 백본을 교체하고 있으며, 폭풍우로 인한 피해를 줄이기 위해 아라미드 재질의 보강재를 채택하고 있습니다. 캐나다도 유사한 추세를 보이고 있으며, 특히 광업 및 에너지 인프라 분야에서 공공 안전에 중점을 두고 있습니다.
아시아태평양은 이 시장의 차세대 성장 거점으로 부상하고 있습니다. 중국은 수입 의존도를 낮추기 위해 국내 생산을 확대하고 있으며, 2020년대 중반까지 파라아라미드의 자급자족을 목표로 하고 있습니다. 스마트 팩토리, 전기차(EV) 배터리 공장, 재생에너지 인프라의 대규모 건설로 인해 경량이며 내열성이 뛰어난 소재에 대한 수요가 비약적으로 증가하고 있습니다. 일본과 한국에서는 반도체 및 5G 하드웨어 분야의 첨단 기술 도입이 진행되고 있어, 아라미드가 제공하는 유전 안정성과 기계적 내구성이 요구되고 있습니다. 인도의 ‘메이크 인 인디아(Make in India)’ 국방 프로그램과 개정된 산업안전보건 기준에 따라, 현지 개인보호장비(PPE) 및 방탄 장비의 소비가 확대되면서 지역 성장에 더욱 탄력을 주고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, aramid fiber market size in 2026 is estimated at USD 4.52 billion, growing from 2025 value of USD 4.30 billion with 2031 projections showing USD 5.78 billion, growing at 5.04% CAGR over 2026-2031.
This report Segments the Industry by Product Type (Para-Aramid, Meta-Aramid), Spinning Process (Wet Spinning, Dry Wet Spinning), Application (Security and Protection Equipment, Frictional and Brake Materials, and More), End-User Industry (Safety and Protection Equipment, Aerospace, and More), and Geography (Asia-Pacific, North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Aramid Fiber Market Trends and Insights
Escalating PPE Safety Mandates Across Asian Manufacturing Hubs
Growing enforcement of industrial-safety rules in China, India, and emerging Southeast Asian economies is lifting orders for aramid-reinforced gloves, helmets, and heat-resistant workwear. Industrial helmets made with aramid composites show 37% higher impact resistance than ABS counterparts, a performance gap that accelerates factory adoption. Cut-resistant gloves incorporating para-aramid deliver Level 5 protection with 30% less weight, improving comfort for continuous wear. Fire-retardant workwear formulated with meta-aramid maintains structural integrity at 425 °C, aligning with stricter foundry and petrochemical safety codes. Manufacturers supplying this region therefore raise allocation for aramid yarns and fabrics, strengthening the growth profile of the aramid fiber market.
EU Green-Deal Push for Lightweight EV Tires Reinforced with Aramid
European automakers accelerate tire redesign programs that shave vehicle mass to extend electric-car range. Aramid-reinforced tire carcasses cut weight by up to 25%, a saving directly linked to the Green Deal's transport decarbonization targets . Every kilogram trimmed offers a 0.7 km range gain, motivating OEMs to substitute polyester or steel cords with aramid. Compounders are commercializing aramid-filled rubber mixes that lower rolling resistance yet keep durability, reinforcing demand for the aramid fiber market in Europe and soon North America.
MPD & PPD Feedstock Price Volatility
Surging crude-oil swings and regional supply disruptions elevate MPD and PPD cost curves, compressing producer margins and unsettling long-term contracts. The U.S. Department of Commerce lists aromatic diamines among chemically critical inputs subject to geopolitically concentrated production, heightening supply-security risks . Manufacturers counter by exploring bio-based intermediates and closed-loop recovery of aramid scrap, yet near-term volatility still shaves growth momentum within the aramid fiber market.
Other drivers and restraints analyzed in the detailed report include:
- 5G Roll-out Surge Elevating Demand for Aramid-Reinforced Optical-Fiber Cables
- Hypersonic & Space Defense Investments Raising Meta-Aramid Thermal-Shield Consumption
- Patent Cross-Licensing Barriers Deterring New Para-Aramid Entrants
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The para-aramid segment held a commanding 64.35% aramid fiber market share in 2025, supported by ballistic protection, aerospace, and friction-material demand. Para-aramid yarns deliver tensile strength near 3.8 GPa, sustaining their position in body armor and aviation honeycombs. Defense-budget uplifts in the United States and renewed interest in lightweight automotive composites ensure stable volume pipelines for para-aramid within the aramid fiber market. Significant investments, such as a 3,000-ton capacity addition at Toray's South Korea site, underscore the scale of capital allocation toward this fiber class.
Meta-aramid, while smaller in base, stages the fastest trajectory at a 5.28% CAGR through 2031. Advanced wet-spun filaments now reach 1,255 MPa tensile strength and retain over 90% strength after prolonged UV exposure, unlocking outdoor applications like transmission-line covers. Embedded in fire-retardant fabrics, insulation papers, and filtration bags, meta-aramid addresses thermal stability demands in electronics, industrial safety, and environmental protection. The aramid fiber market size for meta-aramid is forecast to expand steadily because of expanding semiconductor capacity across Asia and EU green-transition projects, setting a competitive dynamic where material attributes, not only price, decide customer conversion.
Wet spinning captured 59.40% of aramid fiber market share in 2025 and continues to out-pace the headline market with a 5.71% CAGR. The process offers homogeneous polymer coagulation, producing uniformly dense fibers that achieve high dielectric stability, a prerequisite for electrical papers and filtration media. Upgraded solvent-recycling modules reduce emissions and cost, supporting adoption even among sustainability-minded end-users. The aramid fiber market size for wet-spun output is projected to widen in line with electrification and filter-media demand growth.
Dry-jet wet spinning remains indispensable for para-aramid where chain orientation drives extreme tensile metrics. Lab runs of polyimide analogues display tensile strength up to 2.72 GPa and modulus above 114 GPa, confirming pathway headroom for future para-aramid enhancement. Although overall share is smaller, the process anchors high-end ballistic yarn supply, aligning with the needs of defense ministries and premium sports-equipment brands. Continuous line upgrades aimed at throughput efficiency and solvent-capture technology will safeguard its niche contribution to the market.
Complete Report Scope:
- By Product Type
- Para Aramid
- Meta Aramid
- By Spinning Process
- Wet Spinning
- Dry Jet Wet Spinning
- By Application
- Security and Protection Equipment
- Frictional and Brake Materials
- Optical Fiber Cables
- Aerospace Components
- Automotive Composites
- Electrical Insulation
- Others (industrial filtration, rubber and tire reinforcement)
- By End User Industry
- Safety and Protection Equipment
- Aerospace
- Automotive
- Electronics and Telecommunication
- Other End User Industries
- Geography
- Asia Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia Pacific
Geography Analysis
Europe anchors the global market with 34.65% revenue in 2025. Stringent worker-safety laws, ISO-aligned flame standards, and the European Union's Green Deal propel high-value adoption in automotive and industrial settings. Germany, with its export-oriented automotive base, leads regional volume expansion, while France and the Netherlands specialize in advanced filtration and aerospace laminates. Government incentives for electric-vehicle battery plants further stimulate polymer-composite uptake.
North America posts the fastest CAGR at 5.21% for 2026-2031. The US Aramid Fiber Market benefits from Federal defense appropriations feed continuous demand for para-aramid ballistic materials, whereas NASA and private launch providers channel investments into meta-aramid thermal shields. U.S. telecom carriers renew aerial fiber backbones across hurricane-prone corridors, specifying aramid strength members to mitigate storm damage. Canada follows similar trends with a public-safety focus, particularly in mining and energy infrastructure.
Asia-Pacific represents the next frontier of scale for the market. China escalates domestic output to cut reliance on imports and targets self-sufficiency in para-aramid by mid-decade. Massive construction of smart factories, EV battery plants, and renewable infrastructure multiplies demand for lightweight, heat-resistant materials. Japan and South Korea refine high-tech deployment in semiconductors and 5G hardware, requiring dielectric stability and mechanical resilience that aramid delivers. India's Make-in-India defense program and updated occupational-safety codes build local PPE and armor consumption, adding depth to regional growth.
- Aramid Hpm, LLC.
- China National Bluestar (Group) Co. Ltd.
- DuPont
- HS HYOSUNG ADVANCED MATERIALS
- Huvis Corp.
- Kolon Industries, Inc.
- Sinochem Internation Corporation
- SINOPEC YIZHENG CHEMICAL FIBRE LIMITED
- SRO Aramid
- Suzhou Zhaoda Specially Fiber Technical Co.,Ltd.
- TAEKWANG INDUSTRIAL CO., LTD.
- Teijin Limited
- Toray Industries Inc.
- TOYOBO MC Corporation
- Wuxi City Shengte Carbon Fiber Products Co.,Ltd
- X-FIPER NEW MATERIAL CO.,LTD
- Yantai Tayho Advanced Materials Co.,Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating PPE Safety Mandates Across Asian Manufacturing Hubs
- 4.2.2 EU Green Deal Push for Lightweight EV Tires Reinforced with Aramid
- 4.2.3 5G Rollout Surge Elevating Demand for Aramid-Reinforced Optical-Fiber Cables
- 4.2.4 Increase in Defense Spending by Many Countries
- 4.2.5 Hypersonic and Space Defense Investments Raising Meta Aramid Thermal Shield Consumption
- 4.3 Market Restraints
- 4.3.1 MPD and PPD Feedstock Price Volatility
- 4.3.2 Patent Cross Licensing Barriers Deterring New Para-Aramid Entrants
- 4.3.3 High Production Costs
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Para Aramid
- 5.1.2 Meta Aramid
- 5.2 By Spinning Process
- 5.2.1 Wet Spinning
- 5.2.2 Dry Jet Wet Spinning
- 5.3 By Application
- 5.3.1 Security and Protection Equipment
- 5.3.2 Frictional and Brake Materials
- 5.3.3 Optical Fiber Cables
- 5.3.4 Aerospace Components
- 5.3.5 Automotive Composites
- 5.3.6 Electrical Insulation
- 5.3.7 Others (industrial filtration, rubber and tire reinforcement)
- 5.4 By End User Industry
- 5.4.1 Safety and Protection Equipment
- 5.4.2 Aerospace
- 5.4.3 Automotive
- 5.4.4 Electronics and Telecommunication
- 5.4.5 Other End User Industries
- 5.5 Geography
- 5.5.1 Asia Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Aramid Hpm, LLC.
- 6.4.2 China National Bluestar (Group) Co. Ltd.
- 6.4.3 DuPont
- 6.4.4 HS HYOSUNG ADVANCED MATERIALS
- 6.4.5 Huvis Corp.
- 6.4.6 Kolon Industries, Inc.
- 6.4.7 Sinochem Internation Corporation
- 6.4.8 SINOPEC YIZHENG CHEMICAL FIBRE LIMITED
- 6.4.9 SRO Aramid
- 6.4.10 Suzhou Zhaoda Specially Fiber Technical Co.,Ltd.
- 6.4.11 TAEKWANG INDUSTRIAL CO., LTD.
- 6.4.12 Teijin Limited
- 6.4.13 Toray Industries Inc.
- 6.4.14 TOYOBO MC Corporation
- 6.4.15 Wuxi City Shengte Carbon Fiber Products Co.,Ltd
- 6.4.16 X-FIPER NEW MATERIAL CO.,LTD
- 6.4.17 Yantai Tayho Advanced Materials Co.,Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Market Expansion of Unmanned Aerial Vehicles (UAV)


