

|
시장보고서
상품코드
2122050
원심 압축기 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Centrifugal Compressor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
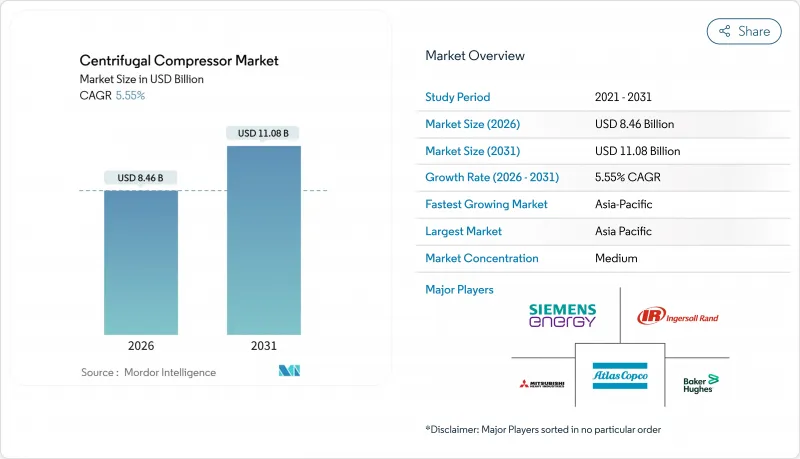
에 의하면, 원심식 압축기 시장 규모는 2026년에 84억 6,000만 달러로 추정되며, 예측 기간(2026-2031년)에 CAGR 5.55%로 성장을 지속하여 2031년에는 110억 8,000만 달러에 이를 전망입니다.
본 보고서는 압축기의 설계(스트레이트 스루형 및 일체형 기어식), 단수(단단식 및 다단식), 냉각 방식(공랭식 및 수랭식), 최종 사용자 산업(석유 및 가스,석유화학·화학, 발전, 금속 및 광업, 식품 및 음료, 기타) 및 지역(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)별로 분류되어 있습니다.
전 세계 원심식 압축기 시장 동향 및 인사이트
천연가스 파이프라인 건설의 급증
북미의 프로젝트는 거대한 간선 파이프라인에서 퍼미안 분지 및 애팔래치아 분지의 유전을 멕시코만 연안의 LNG 터미널로 연결하는 지선으로 전환되고 있습니다. 2024년에만 승인된 7개의 미국 파이프라인 프로젝트로 인해 하루 3.2 bcf의 수송 능력이 추가되었으며, 각 프로젝트에는 여러 대의 원심 압축기 스테이션이 필요합니다. 킨더 모건의 텍사스-루이지애나 간 파이프라인에는 서지 손실 없이 입구 압력 변동에 대응할 수 있는 22,500마력 유닛 6대가 도입되었습니다. 사우디아라비아에서는 ‘마스터 가스 시스템’의 4단계에서 설치 공간을 절약하기 위해 콤팩트한 일체형 기어식 기계를 채택하여, 2027년까지 일일 3 bcf의 수송 능력을 증강할 예정입니다. 중동의 사업자들은 현장 설치 기간을 18개월에서 12개월로 단축하고, 요금 회수 기간을 단축할 수 있는 모듈식 스키드를 선호하고 있습니다. 이러한 네트워크의 확장에 따라 회전 장비의 교체 주기가 단축되어 원심식 압축기 시장을 견인하고 있습니다.
LNG 액화 및 재기화 능력 증강
세계 액화 능력은 2024-2030년간 연간 300 bcm의 속도로 확대될 전망이며, 각 트레인에서는 가스를 -162°C까지 냉각하기 위해 4-6대의 원심식 압축기가 사용됩니다. 벤처 세계의 프락민스 프로젝트에서는 18개의 모듈형 트레인에 총 72대의 압축기가 설치되어 연간 20 mtpa의 수출 능력을 실현하고 있습니다. 카타르의 노스 필드 이스트에서는 미쓰비시 중공업에 대해 부분 부하 시 전력 소비량을 8% 절감하는 96대의 압축기에 대해 18억 달러 규모의 수주가 확정되었습니다. 수요 측면에서는 유럽에서 2024년에 3기의 FSRU가 가동을 시작했으며, 각 선박은 2기의 고압 송출 압축기를 사용하여 70 bar의 압력으로 가스를 주입하고 있습니다. LNG 계약은 자본 집약적이며 계약 기간이 20년에 달하기 때문에 이러한 압축기는 장기 사이클 자산으로서 단기적인 가격 변동의 영향을 덜 받는 특징이 있습니다.
높은 설비 투자액과 왕복동식 대체 기기와의 비교
원심식 기계의 설치 비용은 1마력당 800-2,500달러인 반면, 중출력 범위의 왕복동식 유닛은 600-900달러입니다. 연간 가동 시간이 4,000-6,000시간인 소규모 바이오가스 및 매립지 가스 프로젝트의 경우, 간헐적인 가동으로는 원심식의 높은 비용을 정당화할 수 없기 때문에 피스톤식이 선택되고 있습니다. 가변 주파수 드라이브, 서지 방지 제어, 진동 모니터링 등의 추가 비용으로 인해 40만-60만 달러가 더 소요됩니다. 인도와 동남아시아에서는 리스 계약 시 왕복동식 장비가 선호됩니다. 이 지역에서는 금융 기관이 잔존 가치에 대한 위험을 낮게 평가하기 때문입니다. 경제성 측면에서 원심식 설계가 유리해지는 것은 연간 가동 시간이 7,000시간을 초과하고 인건비가 시간당 80달러를 초과하는 경우로 한정되지만, 이러한 기준을 충족하는 사례는 많은 신흥 지역에서 여전히 드뭅니다.
부문 분석
2025년에는 스트레이트 스루(Straight-through) 방식이 원심식 압축기 시장의 88.4%를 차지하며 시장을 장악했습니다. 파이프라인 및 가스 집하 사업자들은 이 방식의 단순한 샤프트 라인과 유지보수가 용이한 베어링을 높이 평가했습니다. 일체형 기어 모델은 연평균 성장률(CAGR) 7.3%로 확대될 것으로 예측됩니다. 이는 설치 면적이 30%-40% 줄어들기 때문에 데크 공간이 매우 귀중한 부유식 LNG(FLNG)나 해양 플랫폼에 적합하기 때문입니다.
원심식 압축기 시장에서는 API 617-2024의 진동 제한으로 인해 고가의 샤프트 개조를 피하기 위해 1990년대에 제조된 유닛에 대한 기어박스 사후 개조가 촉진되고 있는 점이 반영되어 있습니다. 부지 제약이 있는 유럽 및 아시아의 구매자들은 소음을 6dB 저감하고 설치 면적을 35% 줄일 수 있는 기어드 레이아웃을 선호합니다. 분말 야금 기어 덕분에 오버홀 주기가 40,000시간에서 60,000시간으로 연장되고 수명 주기 비용이 12% 절감됨에 따라 기어박스의 비용 프리미엄은 점차 줄어들고 있습니다.
2025년에는 장거리 파이프라인 및 암모니아 플랜트에서 4:1 이상의 압력비가 필요하기 때문에 다단식 장비가 원심 압축기 시장 규모의 60.6%를 차지했습니다. 그러나 3:1 미만의 압력비가 필요한 데이터센터 냉각 및 식품 가공 수요에 힘입어, 단단식 구성은 2031년까지 연평균 성장률(CAGR) 6.8%로 확대될 것으로 예측됩니다.
전산유체역학(CFD) 기술을 통해 3D 곡면 블레이드가 개발되어, 단단식 압축기의 압력비를 3.8:1까지 높일 수 있게 되었습니다. 이로 인해 인터쿨러가 불필요해져, 트레인당 30만-40만 달러의 비용 절감이 실현되고 있습니다. 광업 분야에서는 브라질의 펠릿 제조 플랜트가 단간 씰이 필요 없어 유지보수 비용을 20% 절감할 수 있다는 점을 이유로 12대의 단단식 유닛을 도입했습니다. ISO 8573-1 클래스 제로 인증의 보급에 따라, 식품 등급의 질소 공급 및 이산화탄소 주입 용도가 오일 침지식 피스톤 압축기에서 전환됨에 따라 원심식 압축기 시장이 혜택을 보고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 38.3%를 차지할 것으로 예상되며, 중국이 80대 이상의 압축기를 도입한 6개의 석유화학 단지를 가동함에 따라 연평균 성장률(CAGR) 6.2%로 확대될 것으로 전망됩니다. 인도 KG 분지에서 각각 15MW 용량의 해저 압축기 12대에 대한 수주는 해양 분야에서의 수익화 추세를 여실히 보여주고 있습니다. 일본과 한국에서는 황 함량 10ppm 이하의 선박용 연료 규제 요건을 충족하기 위해 윤활유 관련 위험이 있는 장비를 오일프리 기계로 교체하고 있습니다.
북미는 퍼미안 분지의 파이프라인과 멕시코만 연안의 액화 사업에 힘입어 2025년 세계 수요의 30% 가까이를 차지했습니다. 프락민스 LNG와 코퍼스 크리스티 3단계 프로젝트는 총 48대의 혼합 냉매용 압축기를 발주했습니다. 캐나다의 LNG Canada는 15%의 수소 혼합 가스를 처리할 수 있는 압축기·터빈 패키지를 15억 5,000만 달러에 발주했습니다. 멕시코의 와하라하라 시스템에서는 가스를 500km 떨어진 과달라하라로 수송하기 위해 4곳의 고압 스테이션이 가동을 시작했습니다.
유럽은 원심식 압축기 시장의 약 5분의 1을 차지하고 있으며, 독일의 3기 FSRU에서는 현재 70바의 압력으로 재기화된 LNG를 주입하고 있습니다. ISO 50001에 기반한 산업용 설비 개조를 통해 2010년 이전의 기계가 교체되었으며, EU 혁신 기금의 보조금이 활용되고 있습니다. 중동 및 아프리카는 2025년 수요의 약 13%를 차지하고 있으며, 카타르의 노스 필드 확장 계획과 16기의 수소 재활용 유닛을 설치한 ADNOC의 루와이스 정유시설 개보수에 그 향방이 달려 있습니다. 남미는 여전히 4%-5%로 규모가 작지만, 부지오스 유전의 압력 유지를 지원하는 페트로브라스의 3억 2,000만 달러 규모 해저 압축 설비 수주가 주목받고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.10According to Mordor Intelligence, the centrifugal compressor market size is estimated at USD 8.46 billion in 2026, and is expected to reach USD 11.08 billion by 2031, at a CAGR of 5.55% during the forecast period (2026-2031).
This report is Segmented by Compressor Design (Straight-Through and Integrally Geared), Stage (Single-Stage and Multi-Stage), Cooling Method (Air-Cooled and Water-Cooled), End-User Industry (Oil and Gas, Petrochemicals and Chemicals, Power Generation, Metals and Mining, Food and Beverage, and Others), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa).
Global Centrifugal Compressor Market Trends and Insights
Surging Natural-Gas Pipeline Build-Outs
North American projects are moving from mega trunk lines toward laterals that link Permian and Appalachian fields to Gulf Coast LNG terminals. Seven U.S. pipeline approvals in 2024 alone added 3.2 bcf/d of capacity, each requiring multiple centrifugal compressor stations. Kinder Morgan's Texas-Louisiana line deployed six 22,500-horsepower units able to handle fluctuating inlet pressures without surge losses. In Saudi Arabia, Phase IV of the Master Gas System will add 3 bcf/d by 2027 using compact integrally geared machines to save plot space. Middle-Eastern operators favor modular skids that cut field-installation time from 18 months to 12 months, improving tariff recovery timelines. As these networks increase mileage, rotational equipment replacement cycles shorten, feeding the centrifugal compressor market.
LNG Liquefaction & Regas Capacity Additions
Global liquefaction capacity is on pace to grow by 300 bcm per year between 2024 and 2030, with each train relying on 4-6 centrifugal compressors to chill gas to -162 °C. Venture Global's Plaquemines project installed 72 compressors across 18 modular trains, delivering 20 mtpa of export capacity. Qatar's North Field East awarded Mitsubishi Heavy Industries a USD 1.8 billion order for 96 units that offer 8% lower power draw in part-load. On the demand side, Europe brought three FSRUs online in 2024, each using two high-pressure send-out compressors to inject gas at 70 bar. The capital-intensive, 20-year nature of LNG contracts makes these compressors long-cycle assets immune to short-term price swings.
High Capex vs. Reciprocating Alternatives
Installed costs range from USD 800 to USD 2,500 per horsepower for centrifugal machines, versus USD 600-900 for reciprocating units in mid-power ranges. Small-scale biogas and landfill-gas projects with 4,000-6,000 operating-hours per year opt for pistons because their intermittent duty does not justify centrifugal premiums. Add-on expenses such as a variable-frequency drive, anti-surge controls, and vibration monitoring add another USD 400,000-600,000. Leasing options favor reciprocating equipment in India and Southeast Asia, where financiers see lower residual-value risk. Economics swing in favor of centrifugal designs only when annual run-hours exceed 7,000 and labor costs top USD 80 per hour, thresholds still rare in many emerging regions.
Other drivers and restraints analyzed in the detailed report include:
- Industrial CCGT Capacity Expansion
- Hydrogen Hub Demand for Oil-Free Compression
- Alloy-Impeller Supply Bottlenecks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Straight-through machines dominated with 88.4% centrifugal compressor market share in 2025; pipeline and gas-gathering operators value their simpler shaft line and easier bearing maintenance. Integrally geared models are forecast to expand at a 7.3% CAGR because a 30%-40% footprint reduction suits floating LNG and offshore platforms where deck space commands premiums.
The centrifugal compressor market reflects that API 617-2024 vibration limits encourage gearbox retrofits of 1990s-vintage units to avoid costly shaft modifications. European and Asian buyers facing land constraints prefer geared layouts that cut noise by 6 dB and plot area by 35%. Gearbox cost premiums are narrowing as powder-metallurgy gears extend overhaul intervals from 40,000 hours to 60,000 hours, reducing lifecycle costs by 12%.
Multi-stage equipment captured 60.6% of the centrifugal compressor market size in 2025 because long-haul pipelines and ammonia plants need 4:1 or higher pressure ratios. Yet single-stage configurations are expected to advance at a 6.8% CAGR through 2031, buoyed by data-center cooling and food processing that demand ratios below 3:1.
Computational fluid dynamics now yields 3D curved blades that push single-stage ratios to 3.8:1, eliminating intercoolers and saving USD 300,000-400,000 per train. In mining, Brazilian pellet plants selected 12 single-stage units for 20% lower maintenance due to no interstage seals. The centrifugal compressor market benefits when ISO 8573-1 Class Zero certification drives food-grade nitrogen and carbonation service away from oil-flooded pistons.
Complete Report Scope:
- By Compressor Design
- Straight-through
- Integrally geared
- By Stage
- Single-stage
- Multi-stage
- By Cooling Method
- Air-cooled
- Water-cooled
- By End-user Industry
- Oil and Gas
- Petrochemicals and Chemicals
- Power Generation
- Metals and Mining
- Food and Beverage
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Australia and New Zealand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific retained 38.3% of 2025 revenue and is forecast to advance at a 6.2% CAGR as China commissioned six petrochemical complexes deploying more than 80 compressors. India's KG Basin subsea compression order for 12 units at 15 MW each highlights offshore monetization trends. Japan and South Korea are swapping out lubricant-risk units with oil-free machines to meet 10 ppm sulfur marine fuel mandates.
North America contributed close to 30% of global demand in 2025, supported by Permian pipelines and Gulf Coast liquefaction. Plaquemines LNG and Corpus Christi Stage 3 together placed 48 orders for mixed-refrigerant compressors. Canada's LNG Canada awarded a USD 1.55 billion compressor-turbine package that can handle 15% hydrogen blends. Mexico's Wahalajara system commissioned four high-pressure stations to move gas 500 km to Guadalajara.
Europe held nearly one-fifth of the centrifugal compressor market; three German FSRUs now inject regasified LNG at 70 bar. Industrial retrofits under ISO 50001 are replacing pre-2010 machines and unlocking EU Innovation Fund grants. The Middle East and Africa, roughly 13% of 2025 demand, hinge on Qatar's North Field expansion and ADNOC's Ruwais refinery upgrade, which installed 16 hydrogen recycle units. South America remains small at 4%-5% but notable for Petrobras' USD 320 million subsea compression order supporting Buzios field pressure maintenance.
- Atlas Copco AB
- Ingersoll Rand Inc.
- Siemens Energy AG
- Baker Hughes Co.
- Mitsubishi Heavy Industries Ltd
- Sundyne LLC
- Elliott Group
- Howden Group
- MAN Energy Solutions
- Kobe Steel Ltd
- HMS Group
- Borsig GmbH
- Hitachi Ltd
- Kirloskar Pneumatic Co.
- FS-Elliott
- Gardner Denver Nash
- Shenyang Blower Works Group
- Boldrocchi
- IHI Rotating Machinery
- Sulzer Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging natural-gas pipeline build-outs
- 4.2.2 LNG liquefaction & regas capacity additions
- 4.2.3 Industrial CCGT capacity expansion
- 4.2.4 Stricter energy-efficiency retrofits
- 4.2.5 Hydrogen hub demand for oil-free compression
- 4.2.6 Predictive-maintenance led replacement cycles
- 4.3 Market Restraints
- 4.3.1 High capex vs. reciprocating alternatives
- 4.3.2 Upstream spend cycles tied to volatile oil prices
- 4.3.3 Alloy-impeller supply bottlenecks
- 4.3.4 Rise of modular screw-compressor packages
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Compressor Design
- 5.1.1 Straight-through
- 5.1.2 Integrally geared
- 5.2 By Stage
- 5.2.1 Single-stage
- 5.2.2 Multi-stage
- 5.3 By Cooling Method
- 5.3.1 Air-cooled
- 5.3.2 Water-cooled
- 5.4 By End-user Industry
- 5.4.1 Oil and Gas
- 5.4.2 Petrochemicals and Chemicals
- 5.4.3 Power Generation
- 5.4.4 Metals and Mining
- 5.4.5 Food and Beverage
- 5.4.6 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Spain
- 5.5.2.5 Italy
- 5.5.2.6 NORDIC Countries
- 5.5.2.7 Russia
- 5.5.2.8 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Australia and New Zealand
- 5.5.3.7 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Chile
- 5.5.4.4 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Egypt
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Atlas Copco AB
- 6.4.2 Ingersoll Rand Inc.
- 6.4.3 Siemens Energy AG
- 6.4.4 Baker Hughes Co.
- 6.4.5 Mitsubishi Heavy Industries Ltd
- 6.4.6 Sundyne LLC
- 6.4.7 Elliott Group
- 6.4.8 Howden Group
- 6.4.9 MAN Energy Solutions
- 6.4.10 Kobe Steel Ltd
- 6.4.11 HMS Group
- 6.4.12 Borsig GmbH
- 6.4.13 Hitachi Ltd
- 6.4.14 Kirloskar Pneumatic Co.
- 6.4.15 FS-Elliott
- 6.4.16 Gardner Denver Nash
- 6.4.17 Shenyang Blower Works Group
- 6.4.18 Boldrocchi
- 6.4.19 IHI Rotating Machinery
- 6.4.20 Sulzer Ltd
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment


