

|
시장보고서
상품코드
2122363
유기 과산화물 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Organic Peroxide - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
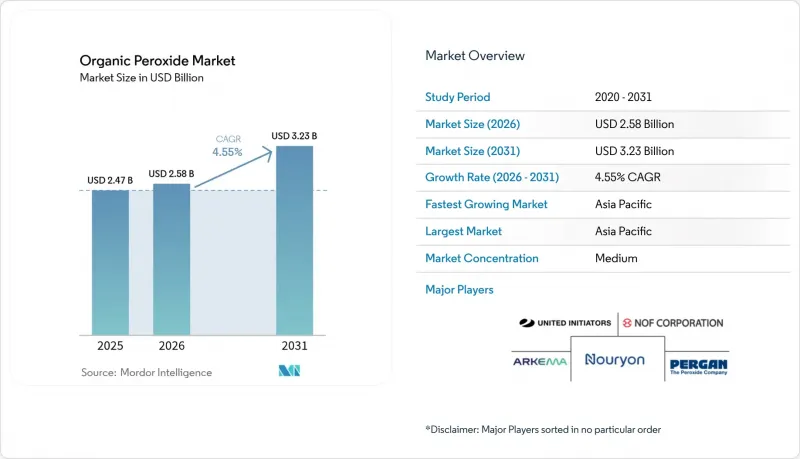
에 의하면, 유기 과산화물 시장 규모는 2025년 24억 7,000만 달러로 평가되었고, 2026년에는 25억 8,000만 달러로 추정되고, 2026-2031년 CAGR 4.55%로 성장을 지속할 전망이며, 2031년에는 32억 3,000만 달러에 이를 것으로 예측됩니다.

본 보고서에서는 업계를 유형별(디아실 과산화물, 디알킬 과산화물, 케톤 과산화물 등), 기능별(중합 개시제 등), 형태별(액체, 고체, 페이스트/에멀젼), 용도별(폴리머·고무, 코팅·접착제, 종이 및 섬유, 화장품 등) 및 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류하고 있습니다.
세계의 유기 과산화물 시장 동향 및 인사이트
고급 PE 및 PP 등급으로의 전환
포장 및 자동차 부품 분야에서 유변학적으로 제어된 폴리프로필렌과 고용융강도 PP에 대한 수요가 증가함에 따라, 아시아태평양 전체에서 유기 과산화물의 소비량이 증가하고 있습니다. LyondellBasell사는 2024년에 재활용 및 재생 가능 자원에서 유래한 폴리머 생산량을 65% 증가한 20만 톤 이상으로 끌어올리고, 2030년까지 연간 200만 톤을 목표로 하고 있으며, 이에 따라 분자량 및 분지 구조를 미세 조정하기 위한 유기 과산화물 수요가 증가하고 있습니다. 가공업체에 따르면, 사슬 절단제로 디크밀 과산화물을 사용할 경우 PP의 가공 효율이 18% 향상되며, Perkadox 및 Trigonox(R) 등급을 사용하여 제조된 분지형 PP는 발포 특성이 30% 향상된다고 합니다. 지역 수지 제조업체들이 특수 수지의 생산 능력을 확대함에 따라, 유기 과산화물 시장은 안정적인 수요 기반을 확보하고 있습니다.
EVA 태양전지 봉지재에 유기 과산화물 적용
급성장하고 있는 태양광 발전 설비에서는 Luperox TBEC 등의 과산화물로 가교 처리된 EVA 봉지 시트가 채택되고 있으며, 겔 함유율을 75% 이상으로 높임으로써 모듈의 내구성이 향상되고 있습니다. 중국은 EVA 시트의 생산량을 주도하고 있으며, 유럽의 모듈 제조업체들도 전력 손실을 억제하기 위해 더 높은 순도의 과산화물 시스템으로 전환을 추진하고 있습니다. 이러한 동향은 단기적으로 유기 과산화물 시장, 특히 분해 프로파일이 좁은 고압 중합용 등급에서 꾸준한 수요 증가로 이어질 것입니다.
에너지 저장 시설의 보험료
2025년 1월 1일 개정된 ADR 체계가 시행됨에 따라, 유기 과산화물의 창고 보관에 관한 분류 및 검사가 더욱 엄격해지고 있습니다. 유럽의 보험사는 대규모 보관 시설에 대한 보험료를 인상하고 있으며, 이로 인해 운영 비용이 증가하여 확장 프로젝트가 지연되고 있습니다. 생산자들은 재고 수준 최적화나 소규모 위성 창고에 대한 투자로 대응하고 있지만, 고정비 급등이 유기 과산화물 시장의 이익률 확대를 제약하고 있습니다.
부문 분석
2025년, 벤조일 과산화물은 유기 과산화물 시장에서 23.70%의 매출 점유율을 유지했습니다. 이는 폴리머 중합의 개시제 및 외용 피부과 치료제로서의 이중 용도를 반영한 것입니다. 자유 라디칼 중합이 스티렌계 수지 및 아크릴계 수지의 대량 생산 경로로 여전히 주류를 이루고 있기 때문에 산업용 등급의 출하량이 시장을 독점하고 있습니다. 그러나 특정 소비자 제품에서 벤젠 오염에 대한 우려가 높아지고 감시가 엄격해짐에 따라 제품의 재조성이 촉진되고 있습니다.
과탄산염은 친환경적이라는 특징과 세정제로서의 폭넓은 수요에 힘입어 연평균 성장률(CAGR) 4.68%로 가장 빠르게 성장하는 하위 부문입니다. 폐수 처리를 위한 과탄산염 기반의 고도 산화 공정의 실용화로 고객층이 확대되면서 향후 시장 점유율 확대가 촉진되고 있습니다.
중합 개시제는 2025년에 유기 과산화물 시장의 64.45% 점유율을 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 5.14%를 나타낼 것으로 전망됩니다. 생산량이 많은 LDPE 및 PP 제조 시설에서는 분해 속도가 예측 가능하기 때문에 tert-부틸퍼옥시-2-에틸헥사노에이트와 같이 특성이 충분히 규명된 개시제가 선호됩니다. 가교제는 그 다음으로 큰 범주에 속하며, 고온에서 치수 안정성이 요구되는 전선 및 케이블 피복재, 발포 단열재, 복합재료 부품에 사용됩니다. 경화제 및 경화 촉진제는 생산량은 적지만, 3D 프린팅 및 고압 RTM 복합재용 첨단 수지 화학 분야에서 중요성이 커지고 있습니다.
지역별 분석
아시아태평양은 2025년에 유기 과산화물 시장의 38.85%를 차지했으며, 하류 플라스틱 및 엘라스토머 분야의 견조한 생산 능력 확대에 힘입어 연평균 성장률(CAGR) 4.83%로 성장하고 있습니다. 중국이 이 지역 수요를 주도하고 있으며, 2024년 11월 누리온(Nourion)사가 닝보에서 진행한 확장 공사로 인해 “Perkadox 14” 및 “Trigonox 101”의 생산량은 6,000톤으로 두 배 증가했습니다. 이는 제어된 유변학 조절제에 대한 현지 수요가 높음을 뒷받침하는 것입니다.
북미 시장은 자동차용 복합재료, 헬스케어 및 고순도 반도체용 폴리머 분야에서 성숙기에 접어들었음에도 불구하고 부가가치가 높은 수요가 특징입니다. 각 제조업체는 보다 안전한 배합을 중시하고 있으며, 일부 기업은 과산화물의 대량 운송에 관한 미국 교통부(DOT)의 강화된 지침을 준수하는 에멀젼계 개시제를 도입하고 있습니다.
유럽은 이에 근소한 차이로 뒤를 잇고 있으며, VOC 배출을 규제하고 위험물의 보다 안전한 운송을 의무화하는 환경 규제가 성장의 원동력이 되고 있습니다. 2025년에 시행될 ADR 개정에 따라 보관 시 분리 및 교육에 관한 요건이 더욱 엄격해져 운영 비용이 증가할 것으로 예상에 따라, 페이스트형 및 폴리머 결합형의 채택이 촉진되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the organic peroxide market size is expected to grow from USD 2.47 billion in 2025 to USD 2.58 billion in 2026 and is forecast to reach USD 3.23 billion by 2031 at 4.55% CAGR over 2026-2031.
This report Segments the Industry by Type (Diacyl Peroxides, Dialkyl Peroxides, Ketone Peroxides, and More), Function (Polymerization Initiators, and More), Form (Liquid, Solid, and Paste/Emulsion), Application (Polymers and Rubber, Coatings and Adhesives, Paper and Textile, Cosmetics, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa).
Global Organic Peroxide Market Trends and Insights
Shift Toward Advanced PE and PP Grades
Rising requirements for controlled rheology polypropylene and high-melt-strength PP in packaging and automotive parts lift organic peroxide consumption across Asia Pacific. LyondellBasell raised recycled and renewable-based polymer output by 65% in 2024 to more than 200,000 t, with a target of 2 million t annually by 2030, increasing the need for organic peroxides that fine-tune molecular weight and branching. Processors report an 18% jump in PP processing efficiency when dicumyl peroxide is applied as a chain breaker, while branched PP made with Perkadox and Trigonox(R) grades delivers 30% better foam properties. As regional resin producers expand specialty capacity, the organic peroxide market gains a stable demand base.
Adoption of Organic Peroxides in EVA Solar Encapsulants
Fast-growing photovoltaic installations rely on EVA encapsulation sheets cross-linked with peroxides such as Luperox TBEC to reach gel contents above 75%, thereby enhancing module durability. China dominates EVA sheet output, and European module makers are also upgrading to higher-purity peroxide systems to curb power loss. These trends translate into steady incremental volumes for the organic peroxide market in the near term, especially for high-pressure polymerization grades that offer narrow decomposition profiles.
Insurance Premiums for Storage Facilities
Implementation of the revised ADR framework on 1 January 2025 elevates classification and inspection rigor for organic peroxide warehousing. European underwriters have lifted premiums for large-volume sites, raising operating costs and delaying expansion projects. Producers are responding by optimizing inventory levels and investing in smaller satellite depots, yet higher fixed costs constrain margin expansion for the organic peroxide market.
Other drivers and restraints analyzed in the detailed report include:
- Growth of VOC-Free Powder Coatings in Europe
- Automotive Lightweighting Drives Composite Applications
- Feedstock Supply Tightness
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Benzoyl peroxide retained a 23.70% revenue share of the organic peroxide market in 2025, reflecting its dual usage in polymer initiation and topical dermatology. Industrial grade volumes dominate because free-radical polymerization remains a high-throughput route for styrenics and acrylics. Nevertheless, concerns over benzene contamination in certain consumer products have raised scrutiny, spurring product reformulation.
Percarbonates, propelled by eco-friendly credentials and broad cleaning-agent appeal, are the fastest-growing sub-segment at a 4.68% CAGR. Commercialization of percarbonate-based advanced oxidation processes for wastewater remediation broadens the customer mix and supports future share gains.
Polymerization initiators captured 64.45% of the organic peroxide market share in 2025 and are forecast to post a 5.14% CAGR to 2031. High throughput LDPE and PP facilities favor well-characterized initiators such as tert-butyl peroxy-2-ethylhexanoate owing to predictable decomposition kinetics. Cross-linking agents are the next-largest category, used in wire-and-cable jacketing, foam insulation, and composite parts that need dimensional stability at elevated temperatures. Curing and hardening agents, though smaller in volume, gain importance in advanced resin chemistries for 3D printing and high-pressure RTM composites.
Complete Report Scope:
- By Type
- Diacyl Peroxides
- Dialkyl Peroxides
- Ketone Peroxides
- Hydro-Peroxides
- Percarbonates
- Benzoyl Peroxide
- Peroxyesters
- Others
- By Function
- Polymerization Initiators
- Cross-Linking Agents
- Curing/Hardening Agents
- By Form
- Liquid
- Solid
- Paste/Emulsion
- By Application
- Polymers and Rubber
- Coatings and Adhesives
- Paper and Textiles
- Cosmetics
- Healthcare
- Other Application
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordics
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia Pacific held 38.85% of the organic peroxide market in 2025 and is growing at a 4.83% CAGR, supported by robust downstream plastics and elastomer capacity additions. China dominates regional demand, and Nouryon's November 2024 expansion in Ningbo doubled the output of Perkadox 14 and Trigonox 101 to 6,000 tons, underscoring local appetite for controlled rheology modifiers.
North America is characterized by mature but value-added demand in automotive composites, healthcare, and high-purity semiconductor polymers. Producers emphasize safer formulations, and several have introduced emulsion-based initiators that align with stricter Department of Transportation guidelines on bulk peroxide transport.
Europe trails closely, with growth driven by environmental legislation that restricts VOC emissions and mandates safer carriage of dangerous goods. The ADR update, effective in 2025, imposes tighter storage segregation and training requirements, increasing operating costs but encouraging the adoption of paste and polymer-bound forms.
- ADEKA CORPORATION
- AKPA Kimya
- Arkema
- BASF
- Dow
- Evonik Industries AG
- Hanwha Group
- Jiangsu qiangsheng chemical co. LTD
- Kawaguchi Chemical Industry Co., LTD.
- Lianyungang Hualun Chemical Co.,Ltd.
- MITSUBISHI GAS CHEMICAL COMPANY, INC.
- MPI Chemie BV
- NOF CORPORATION
- Nouryon
- Novichem Sp. z o.o.
- PERGAN GmbH
- Plasti Pigments Pvt. Ltd.
- Shenzhen Bailingwei Technology Co., Ltd.
- Solvay
- United Chemicals
- United Initiators GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Polymer Demand Shift toward Advanced PE and PP Grades in Asia-Pacific
- 4.2.2 Rapid Adoption of Organic Peroxides in High-Pressure EVA Solar Encapsulants
- 4.2.3 Growth of VOC-free, UV-curable Powder Coatings in Europe
- 4.2.4 Automotive Lightweighting, Elevated Use in Fiber-Reinforced Composites
- 4.2.5 Surging Utilization in Coating Applications
- 4.3 Market Restraints
- 4.3.1 High Insurance Premiums for Large-Scale Storage Facilities in EU
- 4.3.2 Supply Tightness of Feedstock
- 4.3.3 Rising Cost of Organic Peroxide Inhibitors for Long-Haul Transit
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers/Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products and Services
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Diacyl Peroxides
- 5.1.2 Dialkyl Peroxides
- 5.1.3 Ketone Peroxides
- 5.1.4 Hydro-Peroxides
- 5.1.5 Percarbonates
- 5.1.6 Benzoyl Peroxide
- 5.1.7 Peroxyesters
- 5.1.8 Others
- 5.2 By Function
- 5.2.1 Polymerization Initiators
- 5.2.2 Cross-Linking Agents
- 5.2.3 Curing/Hardening Agents
- 5.3 By Form
- 5.3.1 Liquid
- 5.3.2 Solid
- 5.3.3 Paste/Emulsion
- 5.4 By Application
- 5.4.1 Polymers and Rubber
- 5.4.2 Coatings and Adhesives
- 5.4.3 Paper and Textiles
- 5.4.4 Cosmetics
- 5.4.5 Healthcare
- 5.4.6 Other Application
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Nordics
- 5.5.3.7 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (Mergers and Acquisitions, JVs, Capacity Expansions)
- 6.3 Market Share(%)/ Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 ADEKA CORPORATION
- 6.4.2 AKPA Kimya
- 6.4.3 Arkema
- 6.4.4 BASF
- 6.4.5 Dow
- 6.4.6 Evonik Industries AG
- 6.4.7 Hanwha Group
- 6.4.8 Jiangsu qiangsheng chemical co. LTD
- 6.4.9 Kawaguchi Chemical Industry Co., LTD.
- 6.4.10 Lianyungang Hualun Chemical Co.,Ltd.
- 6.4.11 MITSUBISHI GAS CHEMICAL COMPANY, INC.
- 6.4.12 MPI Chemie BV
- 6.4.13 NOF CORPORATION
- 6.4.14 Nouryon
- 6.4.15 Novichem Sp. z o.o.
- 6.4.16 PERGAN GmbH
- 6.4.17 Plasti Pigments Pvt. Ltd.
- 6.4.18 Shenzhen Bailingwei Technology Co., Ltd.
- 6.4.19 Solvay
- 6.4.20 United Chemicals
- 6.4.21 United Initiators GmbH
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Growing Demand for Light-Weight Materials


