

|
시장보고서
상품코드
2122569
UV 경화형 접착제 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)UV-Curable Adhesives - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
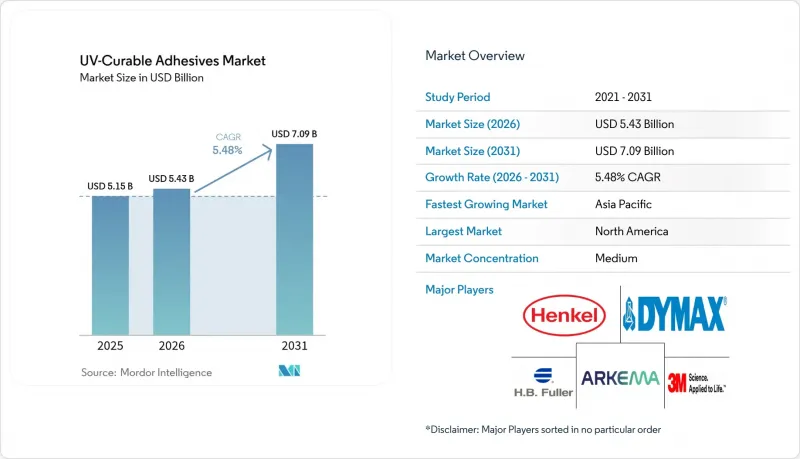
에 의하면, UV 경화형 접착제 시장 규모는 2025년 51억 5,000만 달러로 평가되었습니다. 2026년에는 54억 3,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 5.48%로 성장을 지속하여, 2031년에는 70억 9,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 수지 유형(아크릴, 실리콘, 폴리우레탄, 에폭시, 기타 수지), 최종 사용자 산업(의료, 전기 및 전자, 운송, 포장, 가구, 기타 최종 사용자 산업), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 UV 경화형 접착제 시장 동향 및 인사이트
자동차 및 항공우주 분야의 UV 경화형 접착제 채택
OEM 제조업체들은 ADAS 카메라 모듈, 파노라마 루프 유리 및 전기차 배터리 팩 부품의 접착에 있어 2액형 에폭시 수지에서 UV 경화형 접착제로의 전환을 추진하며, 고정 시간을 30분에서 60초 미만으로 단축하고 있습니다. 2025년 5월에 도입된 DELO사의 스테이터 포팅용 LED 경화형 수지는 150°C의 연속 운전 조건을 견디면서 생산 라인의 처리량을 30% 향상시켰습니다. 2024년에 공표된 IEC 62899-1 가이드라인에 따라 검증 프로토콜이 표준화되어, 1차 공급업체 인증에 소요되는 공수가 6개월 단축되었습니다.
VOC/REACH 규제의 강화로 인해 무용제계 화학물질이 주목받고 있습니다.
유럽화학물질청(ECHA)은 2025년 3월, 3유형의 글리콜 에테르를 REACH 후보 목록에 추가하여 VOC를 전혀 포함하지 않는 UV 경화형 아크릴계 접착제로의 전환을 가속화했습니다. 캘리포니아주 사우스코스트 대기질 관리구는 2026년 1월부터 산업용 접착제의 VOC 제한치를 50 g/L로 낮추어, 각 변환 업체에 생산 라인 재구성을 촉구하고 있습니다. 중국의 GB 38507-2024에 따르면, 공장 수준의 VOC 배출량이 80 mg/m³로 낮아져 광둥성에서 UV 기술에 대한 투자가 촉진되고 있습니다. 미국 환경보호청(EPA)이 2025년 10월에 공표한 유해 대기 오염 물질 기준 개정안에 따라, 2029년까지 용제형 접착제 시장 점유율 15%가 대체될 것으로 예측됩니다.
UV-LED 경화 시스템의 높은 도입 비용
산업용 UV-LED 컨베이어 시스템의 가격은 5만-30만 달러에 달하고, 소규모 가공업체에게는 진입 장벽이 되고 있습니다. 2024년 접착제 및 실란트 협의회(Adhesive & Sealant Council)의 조사에 따르면, 북미 포장 제조업체의 38%가 설비 투자 비용을 가장 큰 장벽으로 꼽았습니다. 인도의 라벨 인쇄업체들은 수입 시스템에 대해 28%의 관세에 더해 18%의 GST(상품 및 서비스세)를 부담하고 있어, 이로 인해 가격이 52%나 치솟았습니다. Phoseon사의 구독 모델을 통해 유럽의 초기 도입 기업 40곳의 초기 비용이 60% 절감되었습니다. 로렌스 버클리 국립연구소의 조사에 따르면, 수은 아크 기술에 비해 70%의 전력 절감 효과가 확인되었으며, 이로 인해 연간 1만 5,000-2만 5,000달러의 운영 비용이 상쇄되고 있습니다.
부문별 분석
2025년, 아크릴계는 UV 경화형 접착제 시장 점유율의 47.12%를 차지하며, 압력 감지 라벨 및 의료용 조립에 선호되는 가성비를 실현했습니다. 에폭시 수지는 25 MPa를 초과하는 인장 강도 및 120°C를 초과하는 유리 전이 온도가 필요한 자동차 및 항공우주 분야 수요에 힘입어 2031년까지 연평균 성장률(CAGR) 5.61%를 나타낼 것으로 예측됩니다. 에폭시 제품 중 UV 경화형 접착제 시장 규모는 전기차용 배터리 팩의 채택 확대에 따라 꾸준히 성장할 것으로 전망됩니다. 실리콘계 UV 등급은 고온 환경의 전자기기 및 LED 패키징에 활용되고 있으며, 다우코닝(Dow Corning)사의 OE-6630이 엔진룸용 센서 인증을 획득한 것이 그 한 예입니다. 폴리우레탄계 UV 접착제는 성장률이 300%를 초과하여 기판의 변형을 박리 없이 흡수할 수 있기 때문에 플렉서블 회로 및 섬유 제품 사용자들로부터 지지를 받고 있습니다.
아크릴계 접착제공급망은 범용 모노머 가격이 1kg당 2.20달러 선에서 형성되고 있는 혜택을 받고 있지만, 한편 시클로알리파틱 에폭시 수지는 1kg당 6.50달러를 초과하고 있어 아크릴계의 비용 우위가 뒷받침되고 있습니다. SikaFlex-525 UV와 같은 하이브리드형(UV+습기 경화) 에폭시 수지는 10초간의 조사로 최종 강도의 80%에 도달하며, 그늘진 곳에서는 습기에 의한 가교 반응을 통해 경화를 완료합니다. 2024년 EU가 소비자용 제품에 대한 방향족 디이소시아네이트 사용을 규제함에 따라, 폴리우레탄 배합 제품은 원자재 비용 상승에 직면해 있습니다. 실리콘계 UV 접착제는 3배의 가격 프리미엄이 부과되고 있지만, 200°C의 내열성이 필수적인 상황에서는 여전히 없어서는 안 될 존재입니다.
지역별 분석
2025년, 북미는 UV 경화형 접착제 시장을 주도하며 매출의 42.88%를 차지했습니다. 이는 매사추세츠주, 캘리포니아주, 미네소타주에 의료기기 산업 집적지가 밀집해 있으며, FDA 승인을 받은 웨어러블 기기의 60%가 이 지역에서 설계되고 있기 때문입니다. 제너럴 모터스(GM)와 포드(Ford) 등 자동차 OEM 기업들은 ADAS 카메라와 파노라마 루프에 UV 경화형 접착 기술을 도입하여 조립 시간을 40% 단축했습니다. 2026년에 시행될 캘리포니아주의 VOC(휘발성 유기 화합물) 50 g/L 규제로 인해 용제계 제품에서 벗어나는 추세가 더욱 가속화되고 있습니다. 2024년 3월 캐나다 보건부가 ISO 10993을 승인함에 따라 인슐린 펌프 및 진단용 카트리지 분야에서 생체 적합성 UV 경화형 접착제에 대한 수요가 증가했습니다.
아시아태평양은 중국 양쯔강 삼각주 지역의 대규모 스마트폰 및 디스플레이 제조, 한국의 반도체 거점, 그리고 베트남의 조립 산업 클러스터에 힘입어 2026년부터 2031년까지 연평균 성장률(CAGR) 5.69%를 나타낼 것으로 예측됩니다. 중국의 GB 38507-2024에 따른 VOC(휘발성 유기 화합물) 상한 규제로 인해 각 컨버터 업체들은 UV 시스템으로의 전환을 추진하고 있으며, 한편,인도의 이륜차 OEM 업체들은 제조 시 배출 가스에 관한 ‘바랏 스테이지 VI’ 규제를 충족하기 위해 UV 접착제를 채택하고 있습니다. 일본의 올림푸스와 테르모는 2024년에 UV 접착으로 전환한 결과, 내시경 및 카테터 조립 시간을 30% 단축했습니다. 한국의 패널 제조업체들은 접이식 OLED에 대한 수요 증가에 대응하기 위해 UV 경화형 접착제를 채택했습니다.
유럽 수요는 독일, 프랑스, 영국이 주도하고 있습니다. 독일의 전기차 배터리 팩 생산 라인에서는 경화 사이클의 에너지 소비를 35% 절감하기 위해 현재 UV 경화형 접착제의 사용이 지정되어 있습니다. 프랑스 제약 업계에서는 유럽 약전(European Pharmacopoeia)의 잔류 모노머 기준을 충족하기 위해 프리필드 주사기 및 경피 흡수 패치에 UV 접착 기술이 채택되었습니다. 영국에서는 브렉시트 이후 EU 이행 규정이 시행됨에 따라, 플렉서블 패키지 가공업체들이 용제계 라미네이션용 접착제를 UV용 등급으로 대체하는 움직임이 확산되고 있습니다. 남미, 중동 및 아프리카는 UV-LED 장비 비용의 제약으로 인해 아직 초기 단계 시장에 머물러 있지만, 브라질의 자동차 제조업체나 UAE의 의료기기 프리존에서는 틈새 용도를 위한 시범 도입이 진행되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the UV-Curable adhesives market size is expected to grow from USD 5.15 billion in 2025 to USD 5.43 billion in 2026 and is forecast to reach USD 7.09 billion by 2031 at 5.48% CAGR over 2026-2031.
This report is Segmented by Resin Type (Acrylic, Silicon, Polyurethane, Epoxy, and Other Resin Types), End-User Industry (Medical, Electrical and Electronics, Transportation, Packaging, Furniture, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global UV-Curable Adhesives Market Trends and Insights
UV-Curable Adhesives Adoption in Automotive and Aerospace
Original-equipment manufacturers are swapping two-part epoxies for UV-curable adhesives when bonding ADAS camera modules, panoramic-roof glass, and electric-vehicle battery-pack components, lowering fixture time from 30 minutes to under 60 seconds. DELO's LED-curable resin for stator potting, introduced May 2025, boosted line throughput by 30% while withstanding 150°C continuous operation. The IEC 62899-1 guideline, published in 2024, standardized validation protocols, reducing qualification effort for Tier-1 suppliers by six months.
Stricter VOC/REACH Regulations Favor Solvent-Free Chemistries
The European Chemicals Agency added three glycol ethers to the REACH Candidate List in March 2025, accelerating the shift to UV-curable acrylic adhesives containing zero VOCs. California's South Coast Air Quality Management District cut VOC limits for industrial adhesives to 50 g/L effective January 2026, compelling converters to retool production lines. China's GB 38507-2024 lowered plant-level VOC emissions to 80 mg/m3, stimulating UV technology investment in Guangdong. The U.S. EPA's October 2025 draft revision of hazardous-air-pollutant standards is projected to displace 15% of solvent-based adhesive volume by 2029.
High Capital Cost of UV-LED Curing Systems
Industrial UV-LED conveyors cost USD 50,000 to USD 300,000, deterring small converters. A 2024 Adhesive & Sealant Council survey showed 38% of North American packagers citing capital cost as their chief barrier. Indian label printers absorb 28% customs duty plus 18% GST on imported systems, inflating price by 52%. Subscription models from Phoseon trimmed upfront cost by 60% for 40 European early adopters. Lawrence Berkeley National Laboratory documented 70% electricity savings relative to mercury-arc technology, offsetting USD 15,000-25,000 annual operating expenses.
Other drivers and restraints analyzed in the detailed report include:
- Miniaturization in Consumer Electronics
- Rapid Uptake in Wearable Medical Devices
- Availability of Alternative 2-Part Epoxies and Cyanoacrylates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Acrylic accounted for 47.12% of UV-curable adhesives market share in 2025 and delivered the cost-to-performance blend favored for pressure-sensitive labels and medical assemblies. Epoxy is forecast to post a 5.61% CAGR through 2031, powered by automotive and aerospace needs for tensile strengths above 25 MPa and glass-transition temperatures over 120 °C. The UV-curable adhesives market size for epoxy products is projected to expand steadily alongside rising electric-vehicle battery-pack adoption. Silicone UV grades serve high-temperature electronics and LED packaging as demonstrated by Dow Corning OE-6630 qualifying for engine-compartment sensors. Polyurethane UV adhesives attract flexible-circuit and textile users because elongation surpasses 300%, absorbing substrate movement without delamination.
Acrylic supply chains benefit from commodity monomer pricing near USD 2.20 /kg, whereas cycloaliphatic epoxy resins exceed USD 6.50 /kg, supporting acrylic cost leadership. Hybrid UV-plus-moisture epoxies such as SikaFlex-525 UV reach 80% of ultimate strength after 10 seconds of irradiation, finishing cure in shaded areas through moisture crosslinking. Polyurethane formulations face higher raw material costs after the EU restricted aromatic di-isocyanates in consumer products in 2024. Silicone UV adhesives command a triple price premium but remain indispensable where 200 °C thermal endurance is non-negotiable.
Complete Report Scope:
- By Resin Type
- Acrylic
- Silicon
- Polyurethane
- Epoxy
- Other Resin Types
- By End-user Industry
- Medical
- Electrical and Electronics
- Transportation
- Packaging
- Furniture
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Indonesia
- Malaysia
- Thailand
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Turkey
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- Egypt
- Nigeria
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
North America led the UV-curable adhesives market in 2025 with 42.88% revenue owing to dense medical-device clusters in Massachusetts, California, and Minnesota, where 60% of FDA-cleared wearables are designed. Automotive OEMs such as General Motors and Ford integrated UV-curable bonding on ADAS cameras and panoramic roofs, trimming assembly time by 40%. California's 50 g/L VOC limit, effective 2026, further accelerates migration from solvent-based grades. Health Canada's March 2024 endorsement of ISO 10993 strengthened demand for biocompatible UV-curable bonds in insulin pumps and diagnostic cartridges.
Asia-Pacific is projected to grow at a 5.69% CAGR over 2026-2031, propelled by vast smartphone and display manufacturing in China's Yangtze River Delta, South Korea's semiconductor hubs, and Vietnam's assembly corridors. China's GB 38507-2024 VOC cap is moving converters toward UV systems, while India's two-wheeler OEMs adopt UV adhesives to satisfy Bharat Stage VI rules on manufacturing emissions. Japan's Olympus and Terumo cut endoscope and catheter assembly time by 30% after switching to UV bonding in 2024. South Korean panel manufacturers utilized UV-curable adhesives in response to the increasing demand for foldable OLEDs.
Europe's demand is led by Germany, France, and the United Kingdom. Germany's EV battery-pack lines now specify UV-curable adhesives to save 35% energy on cure cycle. France's pharma sector adopted UV bonds in prefilled syringes and transdermal patches to meet European Pharmacopoeia residual-monomer limits. The U.K. enforces EU migration rules post-Brexit, prompting flexible-pack converters to replace solvent-borne laminating adhesives with UV grades. South America and Middle-East and Africa remain early-stage markets constrained by UV-LED equipment costs, although Brazil's automakers and the UAE's medical-device free zones are piloting niche uses.
- 3M
- Arkema
- artience Co., Ltd.
- AVERY DENNISON CORPORATION
- DELO Industrie Klebstoffe GmbH & Co. KGaA
- Dymax
- H.B. Fuller Company
- Henkel AG & Co. KGaA
- Master Bond Inc.
- Panacol-Elosol GmbH
- Parson Adhesives, Inc.
- Permabond Engineering Adhesives Ltd
- Sika AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 UV-Curable Adhesives Adoption in Automotive and Aerospace
- 4.2.2 Stricter VOC/REACH Regulations Favor Solvent-Free Chemistries
- 4.2.3 Miniaturisation in Consumer Electronics
- 4.2.4 Rapid Uptake in Wearable Medical Devices
- 4.2.5 In-Line Digital Packaging Print Lines Demanding Instant Bonding
- 4.3 Market Restraints
- 4.3.1 High Capital Cost of UV-LED Curing Systems
- 4.3.2 Availability of Alternative 2-Part Epoxies and Cyanoacrylates
- 4.3.3 Supply Volatility of Key Photoinitiators
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Acrylic
- 5.1.2 Silicon
- 5.1.3 Polyurethane
- 5.1.4 Epoxy
- 5.1.5 Other Resin Types
- 5.2 By End-user Industry
- 5.2.1 Medical
- 5.2.2 Electrical and Electronics
- 5.2.3 Transportation
- 5.2.4 Packaging
- 5.2.5 Furniture
- 5.2.6 Other End-user Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Indonesia
- 5.3.1.6 Malaysia
- 5.3.1.7 Thailand
- 5.3.1.8 Vietnam
- 5.3.1.9 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Turkey
- 5.3.3.7 Russia
- 5.3.3.8 NORDIC Countries
- 5.3.3.9 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 United Arab Emirates
- 5.3.5.3 Qatar
- 5.3.5.4 Egypt
- 5.3.5.5 Nigeria
- 5.3.5.6 South Africa
- 5.3.5.7 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 Arkema
- 6.4.3 artience Co., Ltd.
- 6.4.4 AVERY DENNISON CORPORATION
- 6.4.5 DELO Industrie Klebstoffe GmbH & Co. KGaA
- 6.4.6 Dymax
- 6.4.7 H.B. Fuller Company
- 6.4.8 Henkel AG & Co. KGaA
- 6.4.9 Master Bond Inc.
- 6.4.10 Panacol-Elosol GmbH
- 6.4.11 Parson Adhesives, Inc.
- 6.4.12 Permabond Engineering Adhesives Ltd
- 6.4.13 Sika AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


