

|
시장보고서
상품코드
2122763
의료보험 청구 관리 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Healthcare Claim Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 의료보험 청구 관리 시장 규모는 2025년에 277억 2,000만 달러로 평가되었습니다. 2026년 321억 7,000만 달러에서 2031년까지 677억 8,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 16.05%를 나타낼 전망입니다.

본 보고서는 솔루션 유형(통합 청구 관리 플랫폼, 기타), 구성 요소(소프트웨어, 서비스), 제공 형태(클라우드 기반, On-Premise·프라이빗 클라우드), 최종 사용자(의료 보험사, 기타), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 의료보험 청구 관리 시장 동향 및 인사이트
공공 및 민간 건강보험의 적용 범위 확대
보험 보급이 확대됨에 따라 새로 보험 적용 대상이 되는 인구가 수백만 명에 달하며, 보험 청구 건수와 복잡성이 증가하고 있습니다. 아시아태평양 신흥 시장에서는 디지털 혁신이 가속화되고 있으며, 그 예로 태국의 AI를 활용한 국민건강보험 로드맵이나 인도가 추진하는 전국 건강 기록과 보험자 시스템의 통합을 들 수 있습니다. 미국에서는 ‘메디케어 공유 절감 프로그램(Medicare Shared Savings Program)’에 따라 의료 제공업체들이 계속해서 책임 의료(Accountable Care) 계약으로 전환하고 있으며, 공유 절감금 결제를 조정하는 고급 분석 기능을 갖춘 플랫폼에 대한 수요가 증가하고 있습니다.
보험금 청구 거부에 따른 재무적 영향 확대
2024년 보험금 청구 기각률은 11.8%에 달했으며, 병원에는 재처리 비용과 수익 손실로 197억 달러의 비용이 발생했습니다. 기각된 청구 건당 시정 비용은 평균 25-181달러이며, 기각된 사례의 65%는 재제출되지 않기 때문에 선제적인 기각 방지가 필수적입니다. 인터마운틴 헬스(Intermountain Health)는 고급 분석을 활용하여 2,000만 달러를 회수했으며, 청구 기각 관리 워크플로우를 재구축함으로써 향후 3,500만 달러의 절감 효과가 예상됩니다.
엄격한 환자 데이터 개인정보 보호 및 사이버 보안 규제
GDPR(EU 개인정보보호규정) 및 HIPAA와 같은 세계 규제 체계에서는 데이터 유출에 대해 엄격한 처벌이 부과되고 있어, 공급업체들은 제로 트러스트 아키텍처 및 종단 간암호화에 투자할 수밖에 없습니다. 의료 기관을 대상으로 한 랜섬웨어 공격이 빈번하게 발생함에 따라 경영진은 보안 인증 및 지속적인 모니터링에 더욱 주력하고 있습니다.
부문별 분석
2025년에는 조직들이 수혜 자격 확인, 사전 승인, 수익 주기 관리 도구를 단일 작업 공간에 통합한 전사적 제품군을 채택함에 따라 통합 플랫폼이 매출 점유율의 42.10%를 차지하며 시장을 장악했습니다. 의료보험 청구 관리 시장에서는 벤더의 난립을 억제하고 규정 준수 감사를 간소화하는 올인원형 생태계가 계속해서 중요시되고 있습니다. 그러나 관리자들이 10%를 초과하는 거절률을 목표로 하고 있기 때문에 AI 기반 거절 관리 모듈은 2031년까지 연평균 성장률(CAGR) 18.21%를 나타낼 것으로 예측됩니다. 이러한 용도는 청구 데이터, 코딩, 임상 기록을 분석하여 지급 기관에 전달되기 전에 고위험 청구를 식별함으로써 재작업에 드는 비용을 절감합니다.
독립형 지급 무결성 엔진은 중규모 보험사에게 여전히 매력적인 선택지입니다. 이는 핵심 심사 시스템을 교체하지 않고도 부정 행위 감지 능력을 신속하게 개선하고자 하는 요구를 충족시킵니다. 옵텀(Optum)의 ‘Integrity One’은 베타 테스트 기간 동안 코더의 생산성을 20% 이상 향상시켰습니다. 한편, 코그니잔트(Cognizant)의 분석 스택을 도입한 한 지역 의료 보험 플랜에서는 미처리 건수를 15분의 1로 줄였습니다. 따라서 의료보험 청구 관리 시장에서는 사후 감사에서 동시 및 사전 리스크 스코어링으로의 명확한 전환이 나타나고 있습니다.
2025년 지출 중 소프트웨어 라이선스가 62.65%를 차지했으며, 이는 최신 플랫폼을 뒷받침하는 AI 규칙 세트, API 라이브러리, 워크플로우 오케스트레이션 엔진에 대한 막대한 투자를 반영합니다. 한편, 병원, 보험사, TPA가 도입, 설정 및 지속적인 최적화 지원을 계약함에 따라 서비스 부문은 연평균 성장률(CAGR) 9.85%로 확대되고 있습니다. 청구 처리의 외부 위탁은 심각한 인력 부족을 보완하는 것이며, 매니지드 서비스 계약은 사내 팀으로는 실현하기 어려운 SLA를 보장합니다.
컨설팅 업무는 개인정보 영향 평가, TEFCA 대응 준비, 금액 기준 계약 모델링을 중심으로 전개되는 경우가 많습니다. 레거시 COBOL 시스템의 운영 종료에 따라 의료 서비스 제공업체들은 다운타임 없이 수백만 건의 기록을 마이그레이션하기 위해 서비스 파트너에 의존하고 있습니다. 그 결과, 의료보험 청구 관리 시장에서 자문 및 매니지드 서비스 부문 시장 규모는 향후 5년간 라이선스 수익 성장률을 상회할 것으로 예측됩니다.
지역별 분석
북미는 2025년 매출의 45.90%를 차지했으며, 그 배경에는 연간 총 수십억 건의 청구를 심사하는 메디케어, 메디케이드, 민간 보험사가 있습니다. '21세기 치료법(21st Century Cures Act)' 및 TEFCA와 같은 연방 정부의 의무화 조치에 따라 FHIR의 상호 운용성이 철저히 보장되고 있으며, 플랫폼의 지속적인 업그레이드가 촉진되고 있습니다. 캐나다의 단일 지불자 모델은 수급 자격 확인 자동화에 활용된 주 차원의 노력을 추진하고 있는 반면, 멕시코의 보험 확대 프로그램은 사회보장 기관의 새로운 시스템 도입을 뒷받침하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 17.20%로 가장 빠르게 성장하고 있는 지역이며, 그 원동력은 의무 보험 제도, 민간 보험사의 급속한 확대, 정부의 AI 로드맵입니다. 중국은 부정행위를 억제하기 위해 국가 환급 의약품 목록에 대한 AI 기반 청구 검증을 추진하고 있으며, 일본은 증가하는 고령 인구를 관리하기 위해 만성 질환 관리 등록 제도를 도입하고 있습니다. 인도에서는 의료 ID 번호를 보험사 데이터베이스와 연동하여 전자 청구 효율화를 도모하고 있으며, 호주의 공유 의료 기록 플랫폼은 원격 진료에서 실시간 심사 처리를 가속화하고 있습니다.
유럽에서는 GDPR(EU 개인정보보호규정)(일반 데이터 보호 규정) 준수 및 전자 처방전 의무화가 도입 우선순위를 좌우하는 가운데, 도입이 착실히 진행되고 있습니다. 독일에서는 ‘Krankenhauszukunftsgesetz(병원 미래법)’ 자금 지원 프로그램을 통해 시맨틱 상호운용성 기준을 추진하고 있으며, 한편 영국의 NHS(국민보건서비스)에서는 통합된 사전 승인 워크플로우를 지원하기 위해 핵심 시스템을 업그레이드하고 있습니다. 남유럽 국가들에서는 유럽 부흥 기금을 활용하여 국경을 넘는 치료에 대한 청구가 가능하도록 청구 포털의 현대화에 투자하고 있습니다. 이러한 노력들이 어우러져 유럽 전역의 의료 청구 관리 시장 확대가 지속될 것으로 확실시되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the healthcare claims management market size was valued at USD 27.72 billion in 2025 and estimated to grow from USD 32.17 billion in 2026 to reach USD 67.78 billion by 2031, at a CAGR of 16.05% during the forecast period (2026-2031).
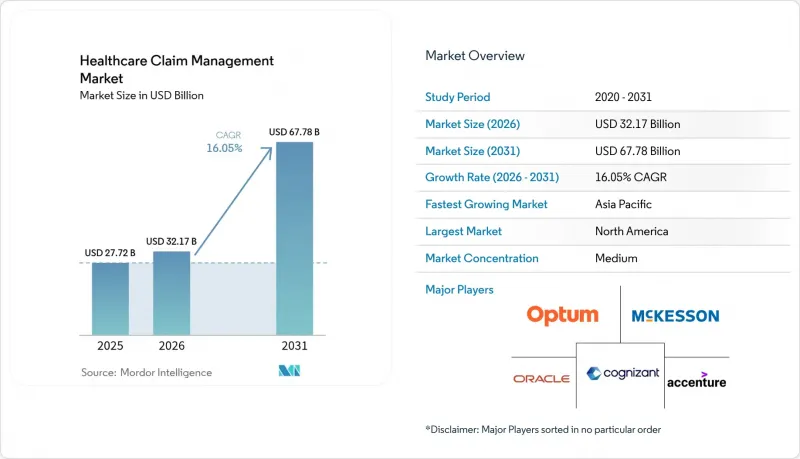
This report is Segmented by Solution Type (Integrated Claims Management Platforms, and More), Component (Software and Services), Delivery Mode (Cloud-Based and On-Premise/Private Cloud), End-User (Healthcare Payers, and More), Geography (North America, Europe, Asia-Pacific, The Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Healthcare Claim Management Market Trends and Insights
Expansion Of Public and Private Health-Insurance Coverage
Wider insurance adoption adds millions of newly covered lives, increasing claims volume and complexity. Emerging Asia-Pacific markets accelerate digital reforms, illustrated by Thailand's AI-enabled universal-coverage roadmap and India's push to integrate national health records with payer systems. In the United States, the Medicare Shared Savings Program continues to migrate providers into accountable-care contracts, driving demand for analytics-rich platforms that reconcile shared-savings payments.
Escalating Financial Impact of Claim Denials
Denial rates reached 11.8% in 2024, costing hospitals USD 19.7 billion in rework and lost revenue. The average denied claim costs USD 25-181 to remediate, and 65% of denied cases are never resubmitted, making proactive denial avoidance essential. Intermountain Health used advanced analytics to recoup USD 20 million and projected USD 35 million in future savings by restructuring its denial-management workflow.
Stringent Patient Data Privacy and Cybersecurity Regulations
Global frameworks such as GDPR and HIPAA impose stiff penalties for data breaches, compelling vendors to invest in zero-trust architectures and end-to-end encryption. Frequent ransomware attacks on healthcare facilities heighten executive focus on security certifications and continuous monitoring.
Other drivers and restraints analyzed in the detailed report include:
- Growing Geriatric and Chronic Disease Population
- Adoption Of AI-Enabled Payment Integrity Platforms
- High Upfront Implementation and Migration Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Integrated platforms dominated 2025 with a 42.10% revenue share as organizations adopted enterprise-wide suites that merge eligibility, prior authorization, and revenue-cycle tools into a single workspace. The healthcare claims management market continues to prize all-in-one ecosystems that lower vendor sprawl and simplify compliance audits. AI-based denial-management modules, however, are set to grow at an 18.21% CAGR through 2031 as administrators target denial rates above 10%. These apps mine claims, coding, and clinical notes to flag high-risk submissions before they reach payers, reducing rework costs.
Standalone payment-integrity engines remain attractive to mid-size payers that want rapid fraud-detection gains without replacing core adjudicators. Optum's Integrity One recorded more than 20% coder-productivity gains during beta testing, while one regional health plan using Cognizant's analytics stack cut pending inventory fifteen-fold. The healthcare claims management market therefore shows a clear pivot from retrospective auditing to concurrent and prospective risk scoring.
Software licenses represented 62.65% of 2025 spending, reflecting large investments in AI rule sets, API libraries, and workflow orchestration engines that anchor modern platforms. Yet the services category is advancing at a 9.85% CAGR as hospitals, payers, and TPAs contract for implementation, configuration, and ongoing optimization support. Outsourced claims-processing units fill critical labor gaps, and managed-service deals guarantee SLAs that internal teams struggle to match.
Consulting engagements often revolve around privacy-impact assessments, TEFCA readiness, and value-based-contract modeling. As legacy COBOL systems sunset, providers rely on service partners to migrate millions of records without downtime. Consequently, the healthcare claims management market size for advisory and managed-services lines is forecast to outpace license revenue growth over the next five years.
Complete Report Scope:
- By Solution Type
- Integrated Claims Management Platforms
- Stand-Alone Claims Management Platforms
- Ai-Based Denial Management Modules
- Payment Integrity Solutions
- By Component
- Software
- Services (Bpo, Consulting, Managed)
- By Delivery Mode
- Cloud-Based
- On-Premise / Private Cloud
- By End-User
- Healthcare Payers (Public And Private)
- Healthcare Providers
- Third-Party Administrators (Tpas)
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 45.90% of 2025 revenue, underpinned by Medicare, Medicaid, and commercial insurers that together adjudicate billions of claims annually. Federal mandates such as the 21st Century Cures Act and TEFCA enforce FHIR interoperability, prompting continuous platform upgrades. Canada's single-payer model drives provincial initiatives to automate eligibility verification, while Mexico's insurance-expansion programs fuel new deployments among social-security institutes.
Asia-Pacific is the fastest-growing region with a 17.20% CAGR, propelled by compulsory insurance schemes, rapid private-payer expansion, and governmental AI roadmaps. China encourages AI-based claim verification within its national-reimbursement-drug list to curb fraud, and Japan embraces chronic-care registries to manage an expanding elder population. India integrates health-identity numbers with payer databases to streamline e-claims, and Australia's shared health-record platform accelerates real-time adjudication for tele-consults.
Europe maintains steady adoption as GDPR compliance and e-prescription mandates shape purchasing priorities. Germany promotes semantic interoperability standards in the Krankenhauszukunftsgesetz funding program, while the United Kingdom's NHS upgrades spine services to support centralized prior-authorization workflows. Southern European countries invest European Recovery funds to modernize claims portals that enable cross-border treatment billing. Collectively, these initiatives ensure the healthcare claims management market continues its expansion across the continent.
- Optum
- Mckesson
- Cognizant (Trizetto)
- Oracle
- Accenture Plc
- Ibm Corporation
- Conduent
- Genpact
- R1 Rcm Inc.
- Cotiviti
- Athenahealth
- Allscripts
- Vee Technologies
- Zelis Healthcare
- Change Healthcare (Legacy)
- Aspirion
- Wns Global Services
- Firstsource Solutions
- Pch Global
- Enablecomp
- Experian Health
- Osp Labs
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope Of The Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Public and Private Health-Insurance Coverage
- 4.2.2 Escalating Financial Impact of Claim Denials
- 4.2.3 Growing Geriatric and Chronic Disease Population
- 4.2.4 Adoption of Ai-Enabled Payment Integrity Platforms
- 4.2.5 Deployment of Robotic Process Automation in Claims Adjudication
- 4.2.6 Shift Toward Value-Based and Real-Time Reimbursement Models
- 4.3 Market Restraints
- 4.3.1 Stringent Patient Data Privacy and Cybersecurity Regulations
- 4.3.2 High Upfront Implementation and Migration Costs
- 4.3.3 Interoperability Challenges Across Legacy Core Systems
- 4.3.4 Shortage of Analytics and Ai-Skilled Workforce
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat Of New Entrants
- 4.5.2 Bargaining Power Of Buyers / Consumers
- 4.5.3 Bargaining Power Of Suppliers
- 4.5.4 Threat Of Substitute Products
- 4.5.5 Intensity Of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Solution Type
- 5.1.1 Integrated Claims Management Platforms
- 5.1.2 Stand-Alone Claims Management Platforms
- 5.1.3 Ai-Based Denial Management Modules
- 5.1.4 Payment Integrity Solutions
- 5.2 By Component
- 5.2.1 Software
- 5.2.2 Services (Bpo, Consulting, Managed)
- 5.3 By Delivery Mode
- 5.3.1 Cloud-Based
- 5.3.2 On-Premise / Private Cloud
- 5.4 By End-User
- 5.4.1 Healthcare Payers (Public And Private)
- 5.4.2 Healthcare Providers
- 5.4.3 Third-Party Administrators (Tpas)
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Optum, Inc.
- 6.3.2 Mckesson Corporation
- 6.3.3 Cognizant (Trizetto)
- 6.3.4 Oracle
- 6.3.5 Accenture Plc
- 6.3.6 Ibm Corporation
- 6.3.7 Conduent Inc.
- 6.3.8 Genpact Limited
- 6.3.9 R1 Rcm Inc.
- 6.3.10 Cotiviti Inc.
- 6.3.11 Athenahealth Inc.
- 6.3.12 Allscripts Healthcare Solutions
- 6.3.13 Vee Technologies
- 6.3.14 Zelis Healthcare
- 6.3.15 Change Healthcare (Legacy)
- 6.3.16 Aspirion
- 6.3.17 Wns Global Services
- 6.3.18 Firstsource Solutions
- 6.3.19 Pch Global
- 6.3.20 Enablecomp
- 6.3.21 Experian Health
- 6.3.22 Osp Labs
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


