

|
시장보고서
상품코드
2122785
압출 코팅 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Extrusion Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
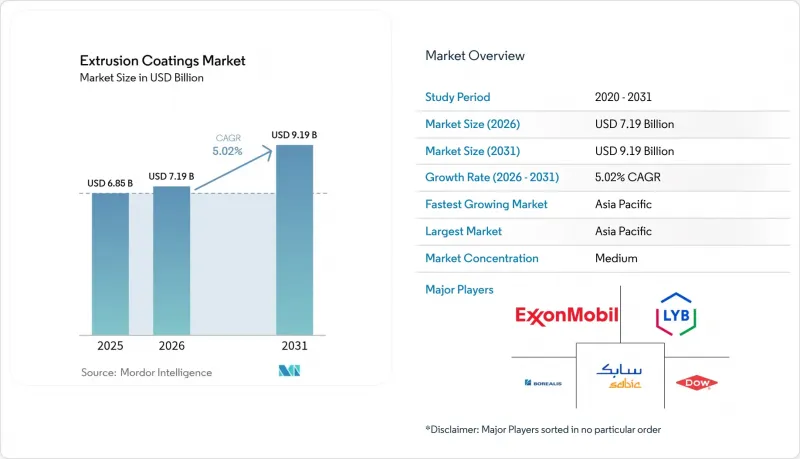
에 의하면, 압출 코팅 시장 규모는 2025년에 68억 5,000만 달러로 평가되었고, 2026년 71억 9,000만 달러에서 2031년까지 91억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.02%를 나타낼 전망입니다.
본 보고서에서는 업계를 소재별(폴리에틸렌, 에틸렌-비닐아세테이트 공중합체(EVA) 등), 기판별(판지·골판지,폴리머 필름 등), 용도별(액체 포장, 연포장 등), 최종 사용자 산업별(식품 및 음료, 헬스케어 및 제약 등), 지역별(아시아태평양, 북미 등)로 분류하고 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 압출 코팅 시장 동향 및 인사이트
액체 및 플렉서블 식품 포장에 대한 수요 증가
2024년, 액체 식품용 카톤 및 경량 파우치는 압출 코팅 시장의 48.95%를 차지했으며, 이 점유율은 신흥국에서의 콜드체인 인프라 미비 및 브랜드 소유자의 상온 보관 가능 형태에 대한 선호로 인해 더욱 공고해지고 있습니다. 2024년에 출시된 바이오매스 유래의 새로운 LDPE 및 EVA 등급은 기존의 차단 성능을 유지하면서 화석 유래 원료의 사용량을 20% 줄였습니다. 포장 가공업체들은 이러한 수지를 활용하여 열밀봉 성능을 저하시키지 않으면서 라미네이트 두께를 얇게 만들어 물류 시 무게를 줄이고 있습니다. 식물성 유제품 대체품이 매장 내 점유율을 확대하고 있는 점과 맞물려, 아시아 및 라틴아메리카 전역에서 꾸준한 판매량 증가가 예상됩니다.
전자상거래용 보호 포장 처리량의 급증
풀필먼트 센터에서는 자동 성형, 고속 밀봉, 라스트 마일 취급에도 견딜 수 있는 코팅층이 요구됩니다. 메탈로센계 촉매를 사용한 PE는 이 워크플로우에 필요한 투명성, 미끄러움, 내천자성을 갖추고 있어, 브랜드 소유주들은 ASTM 운송 낙하 시험 기준을 충족하면서 30-50%의 재활용 소재를 포함한 필름의 채택을 지정하고 있습니다. 이 분야에 대한 결정적인 세계 수량 데이터는 부족하지만, 컨버터의 수주 현황을 보면 2023년 이후 두 자릿수 성장이 예상되며, 이는 전자상거래가 압출 코팅 시장 시장 진출기업들에게 견고한 수요의 축임을 뒷받침하고 있습니다.
폴리올레핀 원료 가격의 격심한 변동
중국의 PE 평균 계약 가격은 2024년 1분기부터 4분기에 걸쳐 톤당 120달러 이상 변동하여, 컨버터의 이익률을 압박하는 동시에 현물 구매로의 조달 전환을 초래했습니다. 통합형 제조업체는 사내 에틸렌 공급을 통해 가격 변동의 충격을 완화하고 있지만, 중소규모 코팅 제조업체는 운전 자금 부족에 직면해 있어 신규 생산 라인에 대한 투자가 지연되는 사례도 나타나고 있습니다. 선물 계약이나 전략적 비축을 통해 일부는 완화되고 있지만, 원자재 가격의 불확실성은 계속해서 압출 성형용 코팅 시장에 단기적인 부담으로 작용하고 있습니다.
부문 분석
폴리에틸렌은 2025년에 압출 코팅 시장의 42.12% 점유율을 차지했으며, 대량 생산되는 액체 및 연포장재의 기반 역할을 계속하고 있습니다. 메탈로센 촉매 기술의 발전으로 인성과 광학적 특성이 향상되고 있는 한편, 화학 재활용 노력을 통해 대규모 순환형 원료 공급이 기대되고 있습니다. 이미 1개의 상업용 생산 라인이 연간 3만 톤을 생산하고 있으며, 2026년까지 연간 50만 톤을 목표로 하고 있습니다. 연평균 성장률(CAGR) 5.67%로 확대되고 있는 에틸렌-비닐아세테이트 공중합체(EVA)는 뛰어난 접착력과 저온에서의 유연성을 활용하여 의료용 및 특수 식품용 틈새 시장을 확보하고 있습니다. EVA와 저밀도 폴리에틸렌(LDPE)을 혼합함으로써, 기계적 재활용 공정에 적합한 단일 소재의 라미네이트 구조도 구현할 수 있습니다. 폴리프로필렌, PET 및 특수 아크릴레이트는 내구성, 높은 차단성 또는 내열성이 필요한 분야를 다루고 있지만, 생산량 측면에서는 여전히 부차적인 위치를 차지하고 있습니다. 수지의 지속적인 혁신은 순환 경제 규제가 엄격해지는 상황에서도 압출 코팅 시장이 다양한 폴리머 라인업을 유지하고 있는 이유를 뒷받침합니다.
밀봉 시작 온도 저하, 에너지 소비 절감, 그리고 바이오 의약품을 위한 글리콜계 멸균 사이클에 대응하는 엔지니어링 블렌드에서 두 번째 성장의 물결이 뚜렷하게 나타나고 있습니다. 이러한 기능적 향상은 컨버터의 전환 비용을 높임으로써, 보다 광범위한 압출 코팅 업계에서 폴리에틸렌이 주력 수지로서의 역할을 공고히 하고 있습니다. 대조적으로, EVA 생산량 증가는 일관된 VA 함량과 식품 접촉 적합성을 확보하고자 하는 아시아태평양 공급업체들 사이에서 후방 통합 움직임을 촉진하고 있습니다.
2025년, 판지 및 골판지는 압출 코팅 시장 규모의 52.10%를 차지했으며, 무균 카톤 및 테이크아웃용 식품 용기에서 그 확고한 역할을 반영하고 있습니다. 2025년에 출시된 특수 바이오 폴리머 첨가제 덕분에 내유성을 유지하면서 최대 50%까지 두께를 얇게 만들 수 있게 되어, 브랜드 소유자가 섬유 재활용 목표를 달성하는 데 도움이 되고 있습니다. 연평균 성장률(CAGR) 6.34%로 성장하고 있는 폴리머 필름은 높은 라인 속도, 두께의 얇아짐, 그리고 묶음용 수축 필름 및 우편용 필름에서의 용도 확대의 혜택을 받고 있습니다. 캐스트 아크릴계 폴리머(PP)의 다양한 제품군은 현재 BO-PP와 동등한 투명성과 봉투 제조 효율을 실현하면서도 비용을 최대 15% 절감하고 있어, 건조 식품 및 퍼스널케어 제품 포장에 대한 보급을 가속화하고 있습니다. 금속 호일은 재활용성 문제가 있음에도 불구하고, 습기 관리가 중요한 의약품 포장에는 여전히 필수적입니다. 특수 직물 및 부직포는 내화학성이 필요한 산업용 요구 사항을 충족하고 있지만, 그 채택은 비용과 공정의 복잡성으로 인해 제한되고 있습니다.
기술적 상호 교류가 두드러집니다. 원래 필름 제조 라인을 위해 개발된 무용제 프라이머의 화학 성분이 판지용으로 재조성됨에 따라, 가공 업체들은 기판 플랫폼을 넘나들며 공통된 툴킷을 활용할 수 있게 되었습니다. 이러한 융합은 압출 코팅 시장이 차단 성능, 재활용성, 비용 관리를 동시에 달성해야 하는 시대에, 기판의 유연성이 가져다주는 전략적 가치를 부각시키고 있습니다.
지역별 분석
아시아태평양은 2025년에 압출 코팅 시장 규모의 56.70%를 차지했으며, 대규모 수지 생산 확대와 가처분 소득 증가를 배경으로 2031년까지 연평균 성장률(CAGR) 6.08%로 성장할 전망입니다. 중국의 지속적인 폴리머 자급자족 전략과 인도의 870억 달러 규모의 석유화학 플랜트 건설로 풍부한 원자재가 공급되는 한편, 급속한 도시화로 인해 포장 식품 및 전자상거래의 보급이 가속화되고 있습니다. 2024년에 착공한 SABIC의 푸젠성 에틸렌 합작 사업은 2027년경 현지 수지 공급을 강화할 것으로 보입니다.
북미에서는 선진적인 재활용 실증 실험과 FDA의 엄격한 포장 기준을 활용하여 기술적 리더십을 유지하고 있습니다. 다우(Dow)사가 2024년 말에 비핵심 사업인 접착제 자산을 매각함으로써, 미래 수요를 대비한 순서큘러 폴리머 규모 확대를 위한 자금이 확보될 것입니다. 유럽은 재활용 및 탄소 배출 목표를 통한 정책적 영향력을 유지하고 있으며, 이는 제품의 신속한 재조성을 촉구하는 한편, 규제를 준수하는 배리어 솔루션에 대한 프리미엄 가격 책정을 촉진하고 있습니다. 멕시코의 생산 능력 증대-예를 들어, 악소노벨(AkzoNobel)의 360만 달러 규모 압출 코팅 라인 등-은 지역 가공업체에 대응하기 위한 북미 시장의 재편을 시사하고 있습니다.
남미, 중동 및 아프리카는 낮은 수준에서 시작되었지만 견조한 성장세를 보이고 있습니다. 사우디아라비아의 1조 5,000억 달러 규모의 인프라 계획은 내식성 랩 소재 수요를 끌어올리고 있는 반면, GCC(걸프협력회의) 국가들의 도료 및 코팅 시장은 2027년까지 45억 달러에 달할 것으로 예측됩니다. 이러한 지역들은 포화 상태에 이른 유럽 및 미국 시장에서 사업 다각화를 목표로 하는 중견 기업들에게 전략적인 그린필드 기회를 제공합니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측(달러)
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the extrusion coatings market size was valued at USD 6.85 billion in 2025 and estimated to grow from USD 7.19 billion in 2026 to reach USD 9.19 billion by 2031, at a CAGR of 5.02% during the forecast period (2026-2031).
This report Segments the Industry by Material (Polyethylene, Ethyl Vinyl Acetate (EVA), and More), Substrate (Paperboard and Cardboard, Polymer Films, and More), Application (Liquid Packaging, Flexible Packaging, and More), End-User Industry (Food and Beverage, Healthcare and Pharma, and More) and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Extrusion Coatings Market Trends and Insights
Growing Demand for Liquid & Flexible Food Packaging
Liquid food cartons and lightweight pouches capture 48.95% of the extrusion coatings market in 2024, a share reinforced by limited cold-chain infrastructure in emerging economies and brand owner preference for shelf-stable formats. New biomass-derived LDPE and EVA grades launched in 2024 match incumbent barrier performance yet cut fossil feedstock by 20%. Packaging converters are leveraging these resins to downgauge laminate thickness and reduce logistics weight without sacrificing heat-seal integrity. Combined with plant-based dairy alternatives gaining shelf space, the outlook affirms steady volume gains across Asia and Latin America.
Surge in E-commerce Protective Packaging Volumes
Fulfilment centers require coating layers that withstand automated forming, high-speed sealing and last-mile handling. Metallocene-catalyzed PE delivers the clarity, slip, and puncture resistance needed for this workflow, prompting brand owners to specify films with 30-50% recycled content that still meet ASTM shipping drop tests. Although the sector lacks definitive global volume data, converter order books reveal double-digit growth since 2023, confirming e-commerce as a resilient demand pillar for extrusion coatings market participants.
High Polyolefin Feedstock Price Volatility
Average PE contract prices in China swung by more than USD 120/ton between Q1 and Q4 2024, compressing converter margins and triggering procurement shifts toward spot purchases. Integrated producers buffer volatility through internal ethylene supply, yet small and midsized coaters face working-capital stress, occasionally delaying new line investments. While futures contracts and strategic stockpiling offer partial relief, raw-material uncertainty remains a near-term drag on the extrusion coatings market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Sterile Medical & Pharma Packaging
- Recyclable Mono-material Structures Adoption
- Increasing Carbon-Footprint Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene captured 42.12% of the extrusion coatings market share in 2025 and continues to anchor high-volume liquid and flexible packaging. Advancements in metallocene catalysis lift toughness and optics, while chemical-recycling initiatives promise circular feedstock at scale; one commercial line already delivers 30,000 t/y and targets 500,000 t/y by 2026. Ethyl vinyl acetate, expanding at 5.67% CAGR, secures medical and specialty food niches due to superior adhesion and low-temperature flexibility. Blending EVA with LDPE also enables mono-material laminate architectures that fit mechanical recycling streams. Polypropylene, PET, and specialty acrylates fill durability, high-barrier, or high-heat slots but remain secondary volume contributors. Continuous resin innovation underscores why the extrusion coatings market maintains a diversified polymer slate even as circular-economy mandates tighten.
A second wave of growth is evident in engineered blends that lower seal initiation temperature, cut energy use, and meet glycol-based sterilization cycles for biologics. These functional enhancements raise switching costs for converters, cementing polyethylene's role as the workhorse resin within the broader extrusion coatings industry. By contrast, EVA's rising volume encourages backward-integration moves among Asia-Pacific suppliers keen to ensure consistent VA content and food-contact compliance.
Paperboard and cardboard accounted for 52.10% of the extrusion coatings market size in 2025, reflecting their entrenched role in aseptic cartons and take-out foodservice. Specialty biopolymer additives launched in 2025 allow downgauging up to 50% while maintaining grease resistance, helping brand owners align with fibre-recycling goals. Polymer films, growing at 6.34% CAGR, benefit from high line speeds, downgauged thickness, and expanding applications in collation shrink and mailer films. Cast PP variants now match BO-PP clarity and bag-making efficiency yet cost up to 15% less, accelerating their penetration into dry food and personal-care wraps. Metal foils remain indispensable for moisture-critical pharma packs despite recyclability challenges. Specialty fabrics and non-wovens fill chemical-resistant industrial slots, but their adoption is tempered by cost and process complexity.
Technological cross-pollination is notable: solvent-less primer chemistries originally developed for film lines are being re-formulated for paperboard, giving converters a common toolkit across substrate platforms. This convergence emphasizes the strategic value substrate agility provides in an era where the extrusion coatings market must balance barrier performance, recyclability, and cost discipline simultaneously.
Complete Report Scope:
- By Material
- Polyethylene
- Low Density Polyethylene (LDPE)
- High Density Polyethylene (HDPE)
- Other Polyethylenes (LLDPE & m-LLDPE, etc.)
- Ethyl Vinyl Acetate (EVA)
- Ethyl Butyl Acrylate (EBA)
- Polypropylene
- Polyethylene Terephthalate
- Other Materials
- Polyethylene
- By Substrate
- Paperboard and Cardboard
- Polymer Films
- Metal Foils
- Other Substrates (Woven Fabrics and Non-wovens, etc.)
- By Application
- Liquid Packaging
- Flexible Packaging
- Medical Packaging
- Personal-Care and Cosmetics Packaging
- Photographic Film
- Industrial Packaging/Wrapping
- Other Applications (Corrosion Protection, etc.)
- By End-User Industry
- Food and Beverage
- Healthcare and Pharma
- Personal-Care and Cosmetics
- Industrial and Chemical
- Other End-User Industries (Publishing, Photographic)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific commanded 56.70% of the extrusion coatings market size in 2025 and is poised to compound at 6.08% CAGR through 2031 on the back of large-scale resin expansion and rising disposable incomes. China's sustained polymer self-sufficiency strategy and India's USD 87 billion petrochemical build-out furnish abundant raw materials, while rapid urbanization intensifies packaged-food and e-commerce penetration. SABIC's joint venture ethylene unit in Fujian, breaking ground in 2024, reinforces localized resin supply circa 2027.
North America leverages advanced recycling pilots and stringent FDA packaging norms to sustain technology leadership. Dow's divestment of non-core adhesive assets in late 2024 frees capital for circular-polymer scale-ups aimed at future demand. Europe maintains policy influence via recycling and carbon targets that compel rapid reformulation but also unleash premium pricing for compliant barrier solutions. Capacity additions in Mexico-such as AkzoNobel's USD 3.6 million extrusion-coatings line-signal North American realignment to serve regional converters.
South America, the Middle East, and Africa expand from a lower base yet post robust gains. Saudi Arabia's USD 1.5 trillion infrastructure pipeline lifts demand for corrosion-resistant wraps, while the GCC paints and coatings sector is projected to reach USD 4.5 billion by 2027. These regions offer strategic greenfield opportunities for mid-tier players aiming to diversify beyond saturated Western markets.
- Akzo Nobel N.V.
- Axalta Coating Systems, LLC
- Borealis AG
- Celanese Corporation
- Chevron Phillips Chemical Company LLC
- Davis-Standard
- Dow
- DuPont
- Eastman Chemical Company
- Exxon Mobil Corporation
- LyondellBasell Industries Holdings B.V.
- Optimum Plastics
- PPG Industries, Inc.
- Qenos Pty Ltd
- SABIC
- SCG Chemicals Public Company Limited
- The Lubrizol Corporation
- The Sherwin-Williams Company
- Transcendia
- Westlake Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand for liquid & flexible food packaging
- 4.2.2 Surge in e-commerce protective packaging volumes
- 4.2.3 Expansion of sterile medical & pharma packaging
- 4.2.4 Recyclable mono-material structures adoption
- 4.2.5 Increasing usage in construction applications
- 4.3 Market Restraints
- 4.3.1 High polyolefin feedstock price volatility
- 4.3.2 Increasing carbon-footprint regulations
- 4.3.3 Shift toward water-based barrier alternatives
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (USD)
- 5.1 By Material
- 5.1.1 Polyethylene
- 5.1.1.1 Low Density Polyethylene (LDPE)
- 5.1.1.2 High Density Polyethylene (HDPE)
- 5.1.1.3 Other Polyethylenes (LLDPE & m-LLDPE, etc.)
- 5.1.2 Ethyl Vinyl Acetate (EVA)
- 5.1.3 Ethyl Butyl Acrylate (EBA)
- 5.1.4 Polypropylene
- 5.1.5 Polyethylene Terephthalate
- 5.1.6 Other Materials
- 5.1.1 Polyethylene
- 5.2 By Substrate
- 5.2.1 Paperboard and Cardboard
- 5.2.2 Polymer Films
- 5.2.3 Metal Foils
- 5.2.4 Other Substrates (Woven Fabrics and Non-wovens, etc.)
- 5.3 By Application
- 5.3.1 Liquid Packaging
- 5.3.2 Flexible Packaging
- 5.3.3 Medical Packaging
- 5.3.4 Personal-Care and Cosmetics Packaging
- 5.3.5 Photographic Film
- 5.3.6 Industrial Packaging/Wrapping
- 5.3.7 Other Applications (Corrosion Protection, etc.)
- 5.4 By End-User Industry
- 5.4.1 Food and Beverage
- 5.4.2 Healthcare and Pharma
- 5.4.3 Personal-Care and Cosmetics
- 5.4.4 Industrial and Chemical
- 5.4.5 Other End-User Industries (Publishing, Photographic)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Akzo Nobel N.V.
- 6.4.2 Axalta Coating Systems, LLC
- 6.4.3 Borealis AG
- 6.4.4 Celanese Corporation
- 6.4.5 Chevron Phillips Chemical Company LLC
- 6.4.6 Davis-Standard
- 6.4.7 Dow
- 6.4.8 DuPont
- 6.4.9 Eastman Chemical Company
- 6.4.10 Exxon Mobil Corporation
- 6.4.11 LyondellBasell Industries Holdings B.V.
- 6.4.12 Optimum Plastics
- 6.4.13 PPG Industries, Inc.
- 6.4.14 Qenos Pty Ltd
- 6.4.15 SABIC
- 6.4.16 SCG Chemicals Public Company Limited
- 6.4.17 The Lubrizol Corporation
- 6.4.18 The Sherwin-Williams Company
- 6.4.19 Transcendia
- 6.4.20 Westlake Corporation
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment
- 7.2 Development of Bio-based Polymers as Raw Material


