

|
시장보고서
상품코드
2122899
자동차 점화 코일 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Automotive Ignition Coil - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
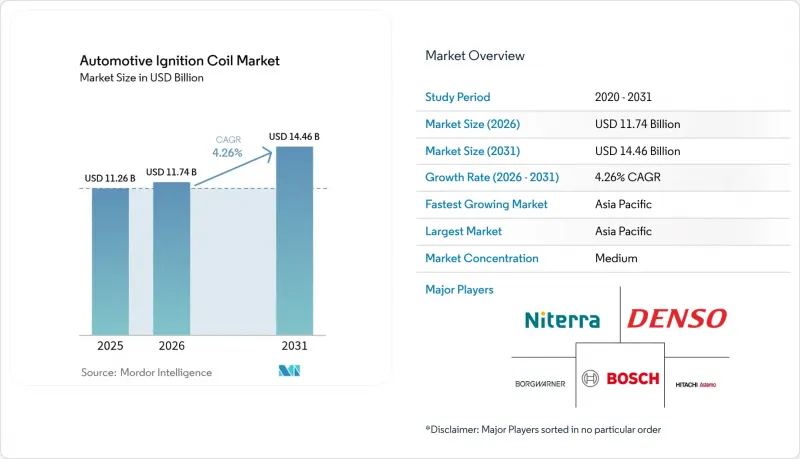
에 의하면, 2026년 자동차 점화 코일 시장 규모는 117억 4,000만 달러로 추정되고 2025년 112억 6,000만 달러에서 확대해, 2031년에는 144억 6,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 동안 연평균 성장률(CAGR) 4.26%로 성장할 것으로 전망됩니다.

본 보고서는 유형별(블록형 점화 코일, 코일 온 플러그(COP), 기타), 작동 원리별(싱글 스파크 기술, 듀얼 스파크 기술), 유통 채널별(OEM, 애프터마켓), 차종별(승용차, 상용차),지역별(북미, 남미, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 자동차 점화 코일 시장 동향 및 인사이트
승용차 및 소형 상용차의 세계 생산 대수 증가
자동차 생산 대수는 팬데믹으로 인한 침체에서 회복세를 이어가고 있으며, 특히 아시아태평양에서는 2024년 상반기 산업 매출이 7% 증가했습니다. 소형 상용차의 전동화는 승용차에 비해 약 5년 정도 뒤처져 있기 때문에 생산 회복은 자동차 점화 코일 시장에 긍정적인 요인으로 작용할 것입니다. 또한, 각 자동차 제조업체는 내연기관(ICE)을 계속 활용하는 48V 마일드 하이브리드 플랫폼을 도입하고 있어, 배기 가스를 줄이면서 코일 수요를 확대되고 있습니다. 유로 7 기준을 충족하기 위한 정밀한 점화 타이밍에 대한 중시는 각 실린더 제어를 지원하는 COP 어셈블리에 호재가 되고 있습니다. 이러한 요인들이 복합적으로 작용하여 성장 궤도에 완만한 상승 효과를 가져오고 있습니다.
노후화된 차량 보유량에 기인한 애프터마켓 교체 수요
2024년, 미국의 차량 평균 보유 연수는 12.5년에 달했습니다. 노후 차량은 정비 빈도가 높아지기 때문에 코일 애프터마켓이 활기를 띠고 있습니다. 스탠다드 모터 프로덕츠(Standard Motor Products)는 이미 800개의 SKU를 라인업하여 99%의 커버율을 달성하고 있습니다. 한편, NGK의 유럽용 제품 라인업은 420개의 품번을 아우르며, 운행 중인 차량의 87%를 지원합니다. 독립 정비 공장은 폭넓은 호환성을 중시하기 때문에 애프터마켓은 점점 더 수익성이 높은 판매 채널이 되고 있습니다. 구형 차량이 폐차되기까지의 시간적 여유 덕분에, 적어도 한 번의 모델 주기에 걸쳐 지속적인 수익원이 확보됩니다.
BEV 보급에 따른 기존 점화 시스템의 도태
전기자동차에서는 스파크 점화 어셈블리 전체가 제거되므로 유지보수 비용이 최대 40% 절감됩니다. 덴소는 2035년까지 BEV가 전 세계 생산 대수의 상당 부분을 차지할 것으로 예측하고 있으며, 이에 따라 공급업체들은 배터리, 인버터, 열 관리 모듈로 사업을 전환하고 있습니다. 승용차 부문에서는 초기에 급격한 감소가 예상되지만, 주행 거리 및 적재량 제한으로 인해 더 무거운 상용차 부문의 전환은 지연될 것으로 보입니다. 이러한 방향 전환으로 인해 향후 코일 출하량에는 상한선이 생길 것입니다.
부문별 분석
2025년 매출에서 코일 온 플러그(COP) 시스템이 차지하는 비중은 51.07%이었으며, 연평균 성장률(CAGR) 6.08%라는 수치를 바탕으로 자동차 점화 코일 시장에서 확실한 성장 동력으로서의 입지를 확고히 하고 있습니다. 이 설계로 인해 고전압 리드선이 불필요해지고 전자기 손실이 감소할 뿐만 아니라, 터보차저 탑재 엔진에 요구되는 정교한 노크 제어 전략에도 대응할 수 있습니다. 블록 코일과 레일 어셈블리는 비용 효율을 중시하는 모델, 특히 신흥국 시장의 엔트리 레벨 부문에서 여전히 경쟁력을 유지하고 있습니다.
OEM 사례도 이러한 변화를 뒷받침하고 있습니다. 보쉬(Bosch)는 점화 플러그의 연결 신뢰성을 향상시키기 위해 BMW 모델용 스프링 접점식 COP를 도입했습니다. 한편, 덴소(Denso)의 제품 포트폴리오 로드맵에서는 유통업체리스 솔루션이 핵심 제품 라인으로 자리 잡고 있습니다. 48V 전동 모터와 내연기관(ICE)을 결합한 하이브리드 파워트레인에서는 여전히 실린더 1개당 코일 1개가 필요하기 때문에 이를 통해 2031년까지 COP 유닛 수요가 확보될 것입니다. 경쟁력 있는 가격 책정, 설치의 간소화, 엔진 관리 성능의 점진적인 향상을 통해 COP는 자동차 점화 코일 시장의 중심적인 위치를 계속 유지할 것으로 보입니다.
2025년에는 싱글 스파크 설계가 매출의 62.27%를 차지했으며, 이는 제조 기술의 성숙도, 입증된 신뢰성, 낮은 비용을 반영한 결과입니다. 그러나 프리미엄 OEM 업체들이 더욱 높은 연소 효율을 추구하는 가운데, 듀얼 스파크 유닛의 연평균 성장률(CAGR)은 5.76%로 성장을 지속하고 있습니다. 브라질의 플렉스 연료 차량의 경우, 에탄올 함량이 변동하기 때문에 안정적인 화염 전파를 위해서는 여러 개의 점화 지점이 유리합니다.
보그워너의 멀티 스파크 제품 라인은 공급업체들이 드웰 시간을 연장하거나 순차적으로 펄스를 공급하여 연소 시간을 최적화하고 있음을 보여줍니다. 규제 당국이 미세먼지 배출 기준을 강화하면 듀얼 스파크의 가치는 높아집니다. 싱글 스파크의 방대한 도입 실적과 폭넓은 엔진 라인업과의 호환성을 고려할 때, 이 구성의 자동차 점화 코일 시장 규모는 예측 기간 동안 계속해서 상당한 규모를 유지할 것으로 전망됩니다.
지역별 분석
아시아태평양은 46.05%의 점유율로 자동차 점화 코일 시장을 주도하고 있으며, 연평균 성장률(CAGR) 6.74%로 성장을 지속하고 있습니다. 중국에서는 2024년에 자동차 산업 매출이 10조 위안에 달하고, 국내 브랜드가 매출의 61.9%를 차지함에 따라 현지 코일 수요가 견조한 추세를 보였습니다. NGK 등 일본 제조업체들은 전 세계에 첨단 제품을 공급하고 있는 반면, 인도의 저비용 기반은 OEM 공급 및 애프터마켓용 수출에 대한 투자를 유도하고 있습니다. 북미는 성숙했지만 수익성이 높은 시장이며, 차량의 평균 보유 연수가 12.5년인 만큼 애프터마켓 수요는 안정적이며, 미국 EPA의 엄격한 규제로 인해 남아 있는 내연기관(ICE) 플랫폼용 고성능 코일 수요는 계속해서 유지되고 있습니다.
유럽에서는 적극적인 BEV 정책과 과도기적인 유로 7 규제에 대한 대응이 병행되고 있습니다. 자동차 제조업체들은 배터리 플랫폼이 보급될 때까지 미세먼지 배출 제한을 충족하기 위해 고출력 코일을 탑재해야 하며, NGK의 애프터마켓 87% 커버율 덕분에 노후화된 가솔린 차량 및 마일드 하이브리드 차량 군에 대한 부품 공급이 확보되어 있습니다. 남미 시장은 브라질의 플렉스 연료 생태계에 힘입어 성장하고 있습니다. 브라질에서는 경차의 82%가 에탄올 혼합 연료로 주행하고 있으며, 이러한 상황은 코일에 가해지는 부하를 높이는 동시에 내식성 설계에 대한 수요를 끌어올리고 있습니다. 브라질의 에탄올 생산량은 2023년에 353억 리터에 달했습니다. 중동 및 아프리카는 여전히 시장 규모가 작지만, 자동차 보급률 상승에 따라 꾸준한 성장을 기록하고 있습니다. 정세 불안과 환율 변동이 물류를 복잡하게 만들고 있지만, 일본 및 중국 브랜드의 현지 조립이 진행됨에 따라 나이지리아, 이집트, 남아프리카공화국에서 코일 관련 비즈니스 기회가 창출되고 있습니다. 전반적으로 지리적 다양성이 자동차 점화 코일 시장을 특정 지역의 충격으로부터 보호하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, automotive ignition coil market size in 2026 is estimated at USD 11.74 billion, growing from 2025 value of USD 11.26 billion with 2031 projections showing USD 14.46 billion, growing at 4.26% CAGR over 2026-2031.
This report is Segmented by Type (Block Ignition Coils, Coil On Plug, and More), Operating Principle (Single Spark Technology and Dual Spark Technology), Distribution Channel (OEM and Aftermarket), Vehicle Type (Passenger Cars and Commercial Vehicles), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Ignition Coil Market Trends and Insights
Rising Global Production of Passenger and Light Commercial Vehicles
Vehicle volumes continue to rebound from pandemic lows, especially in Asia Pacific, where industry revenue climbed 7% in 1H 2024. Production upswings favor the automotive ignition coil market because light commercial electrification trails passenger adoption by roughly five years. Automakers are also rolling out 48V mild-hybrid platforms that keep internal-combustion engines (ICE) in play, extending coil demand while cutting emissions. The emphasis on precise ignition timing to satisfy Euro 7 creates tailwinds for COP assemblies that support individual-cylinder control. Together, these forces add a moderate uplift to the growth trajectory.
Aftermarket Replacement Demand From Ageing Parc
Average fleet age reached 12.5 years in the United States during 2024. Older vehicles require more frequent service, which supports a vibrant aftermarket for coils. Standard Motor Products already fields 800 SKUs with 99% coverage, while NGK's European range covers 420-part numbers that fit 87% of vehicles on the road. Independent workshops rely on broad compatibility, making the aftermarket an increasingly lucrative channel. The time buffer before legacy vehicles retire creates a durable revenue stream for at least one model cycle.
BEV Penetration Eliminates Conventional Ignition Systems
Electric cars remove the entire spark-ignition assembly, cutting maintenance costs by up to 40%. DENSO projects BEVs will dominate global production by 2035, prompting suppliers to pivot toward battery, inverter, and thermal-management modules . Passenger segments will see the sharpest drop first, while heavier commercial classes will transition later due to range and payload limits. Nonetheless, the directional shift places a ceiling on future coil volumes.
Other drivers and restraints analyzed in the detailed report include:
- Stringent Emission Norms Pushing High-Performance Coils
- Turbo-Charged Downsized Gasoline Engines Need COP Coils
- Price Volatility of Copper and Rare-Earth Magnets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Coil-on-plug systems accounted for 51.07% of 2025 revenue, and their 6.08% CAGR positions them as the clear growth engine for the automotive ignition coil market. The design removes high-voltage leads, reduces electromagnetic loss, and supports advanced knock-control strategies demanded by turbocharged engines. Block coils and rail assemblies stay competitive in cost-sensitive models, especially in entry-level segments across emerging economies.
OEM case studies reinforce the shift: Bosch introduced a spring-contact COP for BMW models to improve spark-plug connection reliability, while DENSO's portfolio roadmap highlights distributor-less solutions as a core product line. Hybrid powertrains, which blend a 48 V e-motor with an ICE, still require one coil per cylinder, securing volume for COP units through 2031. Competitive pricing, simplified installation, and incremental engine-management gains will keep COP at the center of the automotive ignition coil market narrative.
Single-spark designs owned 62.27% of sales in 2025, reflecting mature manufacturing, proven reliability, and lower cost. Yet dual-spark units are tracking a 5.76% CAGR as premium OEMs chase further combustion efficiency. In Brazil's flex-fuel fleet, variable ethanol content makes multiple ignition points advantageous for stable flame propagation.
BorgWarner's multi-spark line illustrates how suppliers extend dwell time or deliver sequential pulses to optimize burn time. Dual-spark value scales when regulators tighten particulate limits. Even so, single-spark's sizeable installed base and compatibility with a broad engine mix mean that the automotive ignition coil market size for this configuration will remain substantial through the forecast horizon.
Complete Report Scope:
- By Type
- Block Ignition Coils
- Coil-on-Plug (COP)
- Ignition Coil Rail
- By Operating Principle
- Single Spark Technology
- Dual Spark Technology
- By Distribution Channel
- OEM
- Aftermarket
- By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- New Zealand
- Rest of Asia Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia Pacific leads the automotive ignition coil market with 46.05% share and is on pace for 6.74% CAGR. China recorded auto-industry revenue of 10 trillion yuan in 2024, and domestic brands accounted for 61.9% of sales, driving strong local coil demand. Japanese manufacturers such as NGK ship advanced units worldwide, while India's low-cost base draws investment for OEM supply and aftermarket export. North America is a mature but profitable arena; the 12.5-year average fleet age secures steady aftermarket pull, and strict U.S. EPA rules keep premium coils relevant for remaining ICE platforms.
Europe balances aggressive BEV policy with interim Euro 7 compliance. Automakers must fit high-output coils to meet particulate limits until battery platforms scale, and NGK's 87% aftermarket coverage ensures part availability for aging gasoline and mild-hybrid fleets. South America is driven by Brazil's flex-fuel ecosystem, where 82% of the light-vehicle park runs on ethanol blends, a scenario that raises coil stress and boosts demand for corrosion-resistant designs; Brazil's ethanol output reached 35.3 billion liters in 2023 . The Middle East and Africa remain smaller contributors yet record incremental gains as motorization rates climb. Political instability and currency volatility complicate logistics, but localized assembly by Japanese and Chinese brands is opening coil opportunities in Nigeria, Egypt, and South Africa. Overall, geographic diversity cushions the automotive ignition coil market against single-region shocks.
- NGK Spark Plug Co. Ltd (Niterra)
- Denso Corporation
- Robert Bosch GmbH
- Hitachi Astemo Ltd
- Diamond Electric Holdings Co. Ltd
- Taiwan Ignition System Co. Ltd
- BorgWarner Inc. (incl. Delphi Technologies)
- Eldor Corporation
- Valeo SA
- Continental AG
- Mitsubishi Electric Corporation
- Standard Motor Products Inc.
- Federal-Mogul (Tenneco)
- Mahle GmbH
- Walker Products Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Production of Passenger and Light Commercial Vehicles
- 4.2.2 Aftermarket Replacement Demand From Ageing Parc
- 4.2.3 Stringent Emission Norms Pushing High-Performance Coils
- 4.2.4 Turbo-Charged Downsized Gasoline Engines Need COP Coils
- 4.2.5 Flex-Fuel Programs in Emerging Markets Require Robust Coils
- 4.2.6 Connected-Vehicle Smart-Diagnostic Coils Adoption
- 4.3 Market Restraints
- 4.3.1 BEV Penetration Eliminates Conventional Ignition Systems
- 4.3.2 Price Volatility of Copper and Rare-Earth Magnets
- 4.3.3 48 V Hybrid Architectures Cutting Coil Count per Vehicle
- 4.3.4 Emergence of Low-Tension Plasma Ignition Techs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Type
- 5.1.1 Block Ignition Coils
- 5.1.2 Coil-on-Plug (COP)
- 5.1.3 Ignition Coil Rail
- 5.2 By Operating Principle
- 5.2.1 Single Spark Technology
- 5.2.2 Dual Spark Technology
- 5.3 By Distribution Channel
- 5.3.1 OEM
- 5.3.2 Aftermarket
- 5.4 By Vehicle Type
- 5.4.1 Passenger Cars
- 5.4.2 Commercial Vehicles
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 New Zealand
- 5.5.4.7 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Egypt
- 5.5.5.4 Turkey
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 NGK Spark Plug Co. Ltd (Niterra)
- 6.4.2 Denso Corporation
- 6.4.3 Robert Bosch GmbH
- 6.4.4 Hitachi Astemo Ltd
- 6.4.5 Diamond Electric Holdings Co. Ltd
- 6.4.6 Taiwan Ignition System Co. Ltd
- 6.4.7 BorgWarner Inc. (incl. Delphi Technologies)
- 6.4.8 Eldor Corporation
- 6.4.9 Valeo SA
- 6.4.10 Continental AG
- 6.4.11 Mitsubishi Electric Corporation
- 6.4.12 Standard Motor Products Inc.
- 6.4.13 Federal-Mogul (Tenneco)
- 6.4.14 Mahle GmbH
- 6.4.15 Walker Products Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


