

|
시장보고서
상품코드
2122964
합성 흑연 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Synthetic Graphite - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 합성 흑연 시장 규모는 2026년에 36억 4,000만 달러로 추정되고, 예측 기간(2026-2031년) CAGR 6.85%로 성장을 지속할 전망이며, 2031년까지 50억 7,000만 달러에 이를 전망입니다.
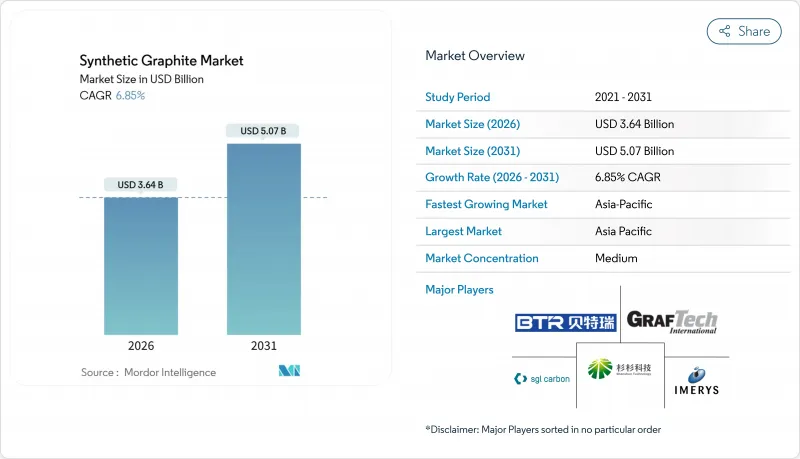
본 보고서는 제품 유형별(흑연 양극, 흑연 블록, 기타), 용도별(배터리, 야금, 기타), 최종 이용 산업별(자동차, 철강·금속, 에너지·발전, 기타), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러)과 수량(톤)으로 제시되어 있습니다.
세계의 합성 흑연 시장 동향 및 인사이트
전기차용 리튬 이온 배터리 수요 증가
배터리용 합성 흑연은 금속 불순물이 50ppm 이하, 입자 크기 분포가 10-20μm라는 순도 기준을 충족해야 하며, 이 기준을 충족하기 위해 코팅 및 정제 라인에 막대한 투자가 이루어지고 있습니다. 제너럴 모터스(GM)와 비아노드(Vianode) 간에 체결된 2024년 공급 계약에서는 온타리오주 기가팩토리에서 생산되는 양극재를 연간 15만 톤 확보하고 있으며,이는 OEM이 ‘우려 대상 외국 기업(FEOC)’의 규정 준수를 충족하기 위해 신규 생산 능력 확충에 자금을 지원할 의향을 나타내는 것입니다. 이미 발표된 북미 프로젝트의 총량은 2024-2026년 연간 약 20만 톤에 달하며, 2023년 이전까지 해당 지역의 생산 능력이 극히 미미했던 점을 고려하면 그 규모는 압도적입니다. NanoGraf의 ‘Onyx’와 같은 실리콘·흑연 복합재는 중량비 에너지 밀도를 30% 향상시키면서도 사이클 수명을 1,000 풀 에퀴벌런트 이상으로 유지하고 있어, 순수 흑연이 따라야 할 성능 기준을 높이고 있습니다. 가격 면에서는 여전히 양극화가 나타나고 있습니다. 급속 충전용 배터리 팩에 사용되는 코팅 처리된 고순도 등급은 톤당 1만 2,000-1만 5,000달러인 반면, 범용 소재는 톤당 8,000-9,000달러입니다. 미국 ‘인플레이션 억제법’에 규정된 함유율 기준(2025년 60%, 2027년 80%로 상향)에 따라, 해당 법을 준수하는 합성 흑연에 대한 지역적 수요가 더욱 증가하고 있습니다.
제강 분야의 초고출력(UHP) 전기 아크로(EAF) 활용 확대
초고출력(UHP) 전극은 탭 간격을 40분 이하로 단축할 수 있어 용광로당 흑연 소비량은 감소하지만, 처리 능력 향상으로 인해 연간 총 전극 수요는 여전히 증가하고 있습니다. 포스코가 2026년까지 연간 2만 톤의 300mm UHP 전극을 현지에서 생산할 계획인 것은 철강 제조업체들이 중국의 수출 불확실성과 운임 변동 위험에 대비하고 있음을 보여줍니다. 열팽창계수(CTE)가 1.0×10⁻⁶°C-1 이하인 니들 코크스의 인증 공급업체는 전 세계에서도 10개사 미만에 그치고 있어, 이러한 제약으로 인해 해당 부문에서 일정한 가격 결정력이 유지되고 있습니다. 인도의 2대 생산자인 Graphite India와 HEG는 합쳐서 연간 약 30만 톤을 공급하고 있지만, 가격이 15-20% 저렴한 중국산 수입품으로 인해 이익률은 계속해서 압박을 받고 있습니다. 규제 준수는 여전히 엄격하며, 일류 철강 제조업체들은 보편적으로 ISO 9001 및 ASTM C1028 인증을 요구하고 있습니다.
높은 제조 비용과 에너지 집약도
합성 흑연 제조에서는 2,800-3,000°C의 흑연화 공정을 통해 1톤당 10-15MWh의 전력을 소비합니다. 2024년 유럽의 산업용 전력 가격은 1MWh당 평균 150-180유로였기 때문에 에너지 비용은 현재 현금 비용의 40-45%를 차지하고 있으며, 중국의 25-30%에 비해 높은 수준입니다. SGL Carbon은 에너지 가격 급등과 고정 가격 계약을 이유로 2024년 이익률이 12% 하락했다고 보고했습니다. 설비 제조업체인 Imerys와 Mersen은 에너지 소비량을 15-20% 절감하는 유도 용광로의 시범 운영을 진행하고 있으나, 1만 톤 모듈당 5,000만-6,000만 유로에 달하는 설비 투자 비용이 도입의 걸림돌이 되고 있습니다. 원료 공급 부족도 여전히 지속되고 있으며, 규격을 충족하는 니들 코크스를 생산하는 정제소는 10곳 미만에 그치고 있어, 생산 능력 확대가 시장 수요보다 약 2년 뒤처져 있습니다. EU의 탄소 가격이 CO2 1톤당 80-90유로 수준이기 때문에 생산자가 이산화탄소 포집 솔루션을 보유하지 않은 경우 톤당 1,200-1,500달러의 추가 비용이 발생합니다.
부문별 분석
'기타' 부문은 원자력용, 반도체용, 연질 등급을 포괄하며, 장기적인 인증 주기에 힘입어 55.87%의 점유율을 차지했습니다. 흑연 양극은 2025년 매출의 약 25%를 차지했으며, 연평균 성장률(CAGR) 8.27%로 확대되어 제품 카테고리 중 가장 높은 성장률을 보이고 있습니다. 양극 공급업체는 코팅 등급에서 18-22%의 EBITDA 마진을 확보하고 있는 반면, 중국산 수입 압력으로 인해 전극 제조업체의 EBITDA 마진은 8-12%에 그치고 있습니다. Group14의 모세스레이크 공장에서 출하된 실리콘·흑연 복합재는 2025년에 4,000톤의 기존 양극재를 대체할 것으로 예상되며, 이는 고급 전기차 모델이 순수 흑연 수요를 잠식하고 있는 실태를 보여줍니다.
원자력용 흑연은 여전히 틈새 시장(연간 5,000톤 이하)에 머물러 있지만, 영국과 캐나다가 소형 모듈형 원자로(SMR) 프로그램을 추진하고 있어 높은 수익을 창출하고 있습니다. 다환 방향족 탄화수소에 관한 ASTM D7219 규격과 EU의 REACH 규정은 규정 준수 측면에서 장벽이 되고 있지만, 주요 생산자의 대부분은 이미 이러한 기준을 충족하고 있습니다.
지역별 분석
아시아태평양은 2025년에 매출의 55.58%를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 7.73%로 성장할 것으로 전망됩니다. 중국의 흑연 수출 허가 규제로 인해 전 세계 공급이 위축되었으나, 2024년 가동률은 여전히 50-60%에 그치고 있어 국내 과잉 생산 능력이 두드러지게 나타나고 있습니다. 일본과 한국은 양극재 생산 능력을 확대하고 있지만, 양국 모두 니들 코크스의 순수입국 지위를 유지하고 있어, 이러한 병목 현상이 중국의 업스트림 부문 우위를 지속시키고 있습니다. 인도의 전극 제조업체들은 중국산 수입품이 국내 가격보다 15-20% 저렴해짐에 따라 2024년에 반덤핑 제소를 제기했고, 두 회사 모두 수익성이 높은 특수 등급으로 전환할 수밖에 없었습니다. 현지 양극 공장은 동남아시아의 배터리 조립 시장의 급속한 성장 속도를 아직 따라잡지 못하고 있으며, 합성 흑연의 대부분은 여전히 수입에 의존하고 있습니다.
북미는 소비량의 상당 부분을 차지하고 있으며, ‘인플레이션 억제법’에 힘입어 수요가 증가하고 있습니다. Superior Graphite사의 아칸소주에 위치한 연산 2만 4,000톤 규모의 공장, NOVONIX의 채터누가 공장 확장, Syrah의 비달리아 생산 라인을 통해 2026년까지 연간 약 5만 톤의 생산 능력이 추가될 전망입니다. 캐나다의 Vianode는 32억 캐나다 달러를 투자하여 GM과의 장기 계약을 바탕으로 2028년까지 연간 15만 톤의 생산을 목표로 하고 있습니다. 2025년부터 시행되는 미국의 FEOC 규정에 따라 중국산 흑연이 7,500달러의 소비자 세금 공제 대상에서 제외됨에 따라, 국내 조달이 진행되고 있습니다.
유럽에서는 에너지 비용 급등이라는 역풍에도 불구하고 수요가 지속적으로 확대되고 있습니다. 독일의 SGL Carbon과 Graphit Kropfmuhl은 특수 등급에 주력하는 반면, Imerys와 Mersen은 원자력 및 화학 용도를 다루고 있습니다. 노르웨이의 수력 발전이라는 강점을 바탕으로, Vianode의 소규모 연산량 2만 톤 생산 라인에서는 탄소 발자국이 5kg CO2/kg 미만으로 유지되고 있습니다. 반면, 석탄을 연료로 사용하는 중국의 생산에서는 15-20kg에 달할 전망입니다. 2022년 제재 이후, 러시아의 니들 코크스 수출은 30-40% 감소하여 유럽의 원료 공급이 부족해지고 있습니다. 남미, 중동 및 아프리카에서는 각 지역의 산업화 진전, 특히 철강·자동차 산업의 확대에 힘입어 현저한 성장률이 예상됩니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the synthetic graphite market size is estimated at USD 3.64 billion in 2026, and is expected to reach USD 5.07 billion by 2031, at a CAGR of 6.85% during the forecast period (2026-2031).
This report is Segmented by Product Type (Graphite Anode, Graphite Block, and Other Types), Application (Batteries, Metallurgy, and More ), End-User Industry (Automotive, Steel and Metals, Energy and Power, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Tons).
Global Synthetic Graphite Market Trends and Insights
Increasing Demand for Electric-Vehicle Li-ion Batteries
Battery-grade synthetic graphite must meet purity below 50 ppm metallic impurities and particle-size distributions of 10-20 μm, standards that are drawing sizeable investment into coating and purification lines. General Motors' 2024 offtake agreement with Vianode locks in 150,000 t p.a. of anode material from the Ontario gigafactory, demonstrating OEM willingness to underwrite greenfield capacity for foreign-entity-of-concern (FEOC) compliance. Announced North American projects total roughly 200,000 t p.a. for 2024-2026, dwarfing the region's negligible pre-2023 capacity. Silicon-graphite composites such as NanoGraf's Onyx deliver 30% higher gravimetric energy density while keeping cycle life above 1,000 full equivalents, raising performance benchmarks that pure graphite must match. Pricing remains bifurcated: coated, high-purity grades used in fast-charging packs command USD 12,000-15,000 per tonne, versus USD 8,000-9,000 per tonne for commodity material. U.S. Inflation Reduction Act content thresholds-60% in 2025, rising to 80% in 2027-further amplify the regional pull for compliant synthetic graphite.
Growing Utilization of Ultra-High-Power EAFs in Steelmaking
UHP electrodes allow tap-to-tap times below 40 minutes, so even with lower graphite consumption intensity per heat, total annual electrode demand still climbs as throughput accelerates. POSCO's plan to localize 20,000 t p.a. of 300 mm UHP electrodes by 2026 illustrates how steelmakers are hedging against Chinese export uncertainties and freight volatility. Qualified suppliers of sub-1.0 X 10⁻⁶ °C-1 CTE needle coke remain fewer than ten globally, a constraint that preserves some pricing power in this segment. India's twin producers, Graphite India and HEG, together supply about 300,000 t p.a., yet Chinese imports priced 15-20% lower continue to squeeze margins. Compliance remains stringent; ISO 9001 and ASTM C1028 are universally demanded by tier-one steel producers.
High Manufacturing Cost and Energy Intensity
Synthetic graphite production consumes 10-15 MWh of electricity per tonne owing to graphitization at 2,800-3,000 °C. European industrial power averaged EUR 150-180 per MWh in 2024, so energy now absorbs 40-45% of cash costs versus 25-30% in China. SGL Carbon reported a 12% margin decline in 2024, citing energy inflation and fixed price contracts. Equipment makers Imerys and Mersen are piloting induction furnaces that cut energy by 15-20%, but the capital costs of EUR 50-60 million per 10,000 t module slow adoption. Feedstock tightness also persists; fewer than ten refineries produce qualifying needle coke, and expansions lag market demand by about two years. EU carbon prices near EUR 80-90 per t CO2 add another USD 1,200-1,500 per tonne if producers lack capture solutions.
Other drivers and restraints analyzed in the detailed report include:
- Faster-Charging Premium EV Models Requiring Ultra-High-Purity Anodes
- Government Incentives for Local Anode Material Gigafactories
- Price Gap with Natural Graphite Prompting Blended Anodes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The Others segment, covering nuclear-grade, semiconductor, and flexible grades, held a 55.87% share, anchored by lengthy qualification cycles. Graphite anode represented roughly 25% of 2025 revenue, is expanding at an 8.27% CAGR, the fastest among product categories. Anode suppliers are capturing 18-22% EBITDA margins on coated grades, whereas electrode makers posted only 8-12% amid Chinese import pressure. Silicon-graphite composites shipped from Group14's Moses Lake plant displaced 4,000 t of conventional anode during 2025, illustrating how premium EV models erode pure-graphite volumes.
Nuclear-grade graphite stays niche (<5,000 t p.a.) but commands higher revenue as the UK and Canada advance small-modular-reactor programs. ASTM D7219 and EU REACH rules on polycyclic aromatic hydrocarbons pose compliance hurdles, yet most major producers already meet these thresholds.
Complete Report Scope:
- By Product Type
- Graphite Anode
- Graphite Block
- Other Types
- By Application
- Batteries
- Metallurgy
- Parts and Components
- Nuclear
- Other Applications
- By End-Use Industry
- Automotive
- Steel and Metals
- Energy and Power
- Electronics and Electrical
- Chemical and Petrochemical
- Aerospace and Defense
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Indonesia
- Malaysia
- Thailand
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordics
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Nigeria
- Egypt
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific commanded 55.58% revenue in 2025 and is predicted to grow at a 7.73% CAGR through 2031. Chinese export-licensing on graphite tightened global supply, yet utilization still ran only 50-60% in 2024, revealing domestic overcapacity. Japan and South Korea are adding anode capacity, but both remain net importers of needle coke, a chokepoint that maintains China's upstream leverage. India's electrode makers filed anti-dumping petitions in 2024 after Chinese imports undercut domestic prices by 15-20%, pushing both firms toward higher-margin specialty grades. Local anode plants do not yet match Southeast Asia's cell-assembly boom, so most synthetic graphite is still imported.
North America accounts for significant consumption and is witnessing higher demand supported by the Inflation Reduction Act. Superior Graphite's 24,000 t Arkansas plant, NOVONIX's Chattanooga expansion, and Syrah's Vidalia line will add about 50,000 t p.a. by 2026. Canada's CAD 3.2 billion Vianode investment aims for 150,000 t p.a. by 2028, backed by a long-term General Motors agreement. U.S. FEOC rules beginning in 2025 exclude Chinese-origin graphite from the USD 7,500 consumer tax credit, accelerating domestic sourcing.
Europe is witnessing a continuously growing demand despite energy-cost headwinds. Germany's SGL Carbon and Graphit Kropfmuhl focus on specialty grades, while Imerys and Mersen cover nuclear and chemical uses. Norway's hydropower advantage gives Vianode's smaller 20,000 t line a carbon footprint below 5 kg CO2/kg, compared with 15-20 kg for coal-based Chinese output. Russian needle-coke exports fell 30-40% post-2022 sanctions, tightening European feedstock supply. South America, the Middle East, and Africa are expected to witness considerable growth rates supported by rising industrialization in the regions, mainly the expansion of the steel and automotive industry.
- Anovion LLC
- Asbury Carbons
- BTR New Material Group Co., Ltd.
- Fengda Carbon New Material Co., Ltd.
- GrafTech International
- Graphit Kropfmuhl GmbH
- Graphite India Limited
- HEG Limited
- Imerys
- Mersen
- Mitsubishi Chemical Group Corporation
- Nippon Carbon Co Ltd.
- NOVONIX Ltd.
- Resonac Holdings Corporation
- SEC CARBON, LIMITED.
- SGL Carbon
- Shanghai PTL New Energy Technology Co., Ltd.
- Shanghai Shanshan Technology Co., Ltd.
- Superior Graphite
- Tokai COBEX GmbH
- Vianode
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing demand for electric-vehicle Li-ion batteries
- 4.2.2 Growing utilization of ultra-high-power (UHP) EAFs in steelmaking
- 4.2.3 Faster-charging premium EV models requiring ultra-high-purity anodes
- 4.2.4 Government incentives for local anode material gigafactories
- 4.2.5 Silicon-graphite composite anodes scaling in next-gen batteries
- 4.3 Market Restraints
- 4.3.1 High manufacturing cost and energy intensity
- 4.3.2 Price gap with natural graphite prompting blended anodes
- 4.3.3 Early commercialisation of sodium-ion batteries reducing graphite demand
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Product Type
- 5.1.1 Graphite Anode
- 5.1.2 Graphite Block
- 5.1.3 Other Types
- 5.2 By Application
- 5.2.1 Batteries
- 5.2.2 Metallurgy
- 5.2.3 Parts and Components
- 5.2.4 Nuclear
- 5.2.5 Other Applications
- 5.3 By End-Use Industry
- 5.3.1 Automotive
- 5.3.2 Steel and Metals
- 5.3.3 Energy and Power
- 5.3.4 Electronics and Electrical
- 5.3.5 Chemical and Petrochemical
- 5.3.6 Aerospace and Defense
- 5.3.7 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Indonesia
- 5.4.1.6 Malaysia
- 5.4.1.7 Thailand
- 5.4.1.8 Vietnam
- 5.4.1.9 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Nordics
- 5.4.3.7 Russia
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 South Africa
- 5.4.5.4 Nigeria
- 5.4.5.5 Egypt
- 5.4.5.6 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Anovion LLC
- 6.4.2 Asbury Carbons
- 6.4.3 BTR New Material Group Co., Ltd.
- 6.4.4 Fengda Carbon New Material Co., Ltd.
- 6.4.5 GrafTech International
- 6.4.6 Graphit Kropfmuhl GmbH
- 6.4.7 Graphite India Limited
- 6.4.8 HEG Limited
- 6.4.9 Imerys
- 6.4.10 Mersen
- 6.4.11 Mitsubishi Chemical Group Corporation
- 6.4.12 Nippon Carbon Co Ltd.
- 6.4.13 NOVONIX Ltd.
- 6.4.14 Resonac Holdings Corporation
- 6.4.15 SEC CARBON, LIMITED.
- 6.4.16 SGL Carbon
- 6.4.17 Shanghai PTL New Energy Technology Co., Ltd.
- 6.4.18 Shanghai Shanshan Technology Co., Ltd.
- 6.4.19 Superior Graphite
- 6.4.20 Tokai COBEX GmbH
- 6.4.21 Vianode
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Bio-graphite as a Sustainable Resource for Battery Material


