

|
시장보고서
상품코드
2123364
산업용 모니터 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Industrial Monitor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
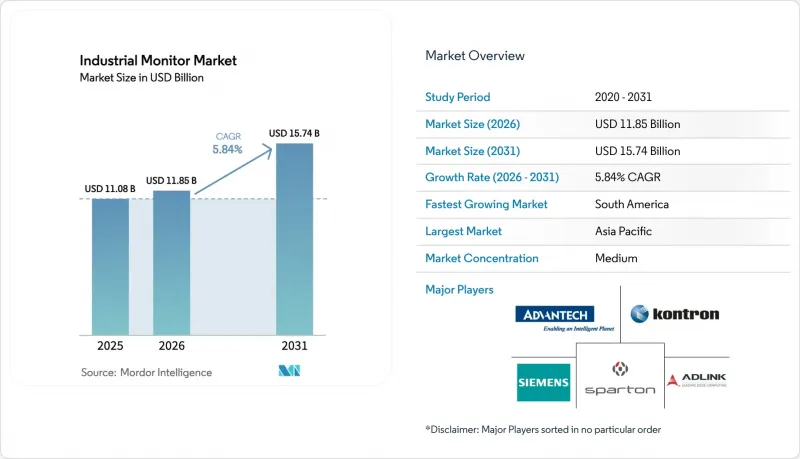
에 의하면, 산업용 모니터 시장 규모는 2025년에 110억 8,000만 달러, 2026년에 118억 5,000만 달러가 되어, 2031년까지 157억 4,000만 달러에 이르고, 2026년부터 2031년까지 CAGR 5.84%로 성장할 전망입니다.
본 보고서는 디스플레이 기술(LCD, LED, OLED, 전자 종이 등), 화면 크기(12인치 미만, 12-23인치, 기타), 설치 방식(패널 마운트, 랙 마운트 등), 최종 이용 산업(자동차 제조, 석유 및 가스,물류 및 운송, 의료 및 헬스케어 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 산업용 모니터 시장 동향 및 인사이트
스마트 팩토리로의 전환이 급증
중소규모 제조업체들은 교체용 자산을 구매하지 않고도 가동 중인 설비의 종합 효율(OEE) 데이터를 실시간으로 수집하기 위해 수명이 긴 기계에 새로운 인간-기계 인터페이스(HMI)를 통합하고 있습니다. Plattform Industrie 4.0의 보고서에 따르면, 독일 중소기업의 68%가 2024년부터 2025년 사이에 최소 1대의 네트워크 연결형 디스플레이를 추가했습니다. 지멘스는 2025년 레트로핏용 모니터 매출이 전년 대비 22% 증가했음을 확인했으며, 유럽 및 북미에서 신규 라인(그린필드)에 비해 레트로핏 프로젝트의 매출 비율이 3대 1이라고 지적했습니다. 리트로핏 구매자들은 설치에 따른 가동 중단 시간을 단축하기 위해 IP65 규격의 밀폐형 베젤, VESA 마운트 및 프로토콜에 구애받지 않는 이더넷을 사양으로 지정하고 있습니다. 이러한 추세에 따라 Profinet, EtherCAT, Modbus TCP 스택과 연동 가능한 모듈형 디스플레이를 제공하는 공급업체에 주문이 집중되고 있습니다.
엣지 AI를 활용한 외관 검사 수요 증가
현재 전자기기 및 자동차 조립 제조업체들은 소형 비전 센서를 인근의 산업용 모니터에 연결하고 있으며, 이를 통해 기술자들은 결함 표시를 실시간으로 확인할 수 있게 되었습니다. 코그넥스는 2025년에 120만 대의 In-Sight SnAPP 센서를 출하하여 2024년 대비 34% 증가했습니다. 이 중 61%는 아시아태평양의 배터리 및 전자기기 공장에 도입되었습니다. 테슬라의 베를린 기가팩토리에서는 2025년에 480개의 검사 셀이 도입되었습니다. 각 셀에는 23인치 터치스크린이 탑재되어 있어, 작업자는 현장에서 컨볼루션 네트워크의 재학습을 수행할 수 있습니다. 이러한 스테이션에는 60Hz의 주사율과 4K 해상도, 그리고 임베디드 그래픽 프로세서가 필요하며, 이로 인해 산업용 모니터 시장에서 고성능 패널에 대한 수요가 증가하고 있습니다.
산업용 TFT 유리 공급망의 지속적인 변동
-30°C에서 +80°C의 작동 사이클을 견딜 수 있는 알칼리 프리 유리를 공급하는 업체는 단 3곳에 불과하기 때문에 공급 중단이 발생하면 산업용 모니터 시장에 즉각적인 영향이 미칩니다. 코닝(Corning)은 2025년 4분기 ‘이글 XG(Eagle XG)’의 가동률이 94%에 달했다고 보고했으며, 리드타임은 18주까지 늘어 소비자용 유리의 2배가 되었습니다. 2025년 3월 AGC의 타카사고 공장 라인에서 발생한 화재로 인해 전 세계 생산 능력의 12%가 7개월간 중단되었으며, 모니터 제조업체들은 더 두꺼운 기판에 대응할 수 있도록 케이스를 재설계하거나 출하를 연기할 수밖에 없게 되었습니다. 2025년, 15인치 산업용 유리의 현물 가격은 42달러에서 68달러 사이에서 변동하며, 이미 낮아져 있던 매출 총이익률을 더욱 압박했습니다.
부문별 분석
2025년, LCD는 확립된 백라이트 공급망에 힘입어 61.21%의 점유율을 차지했습니다. 석유 및 가스 사업자들이 ATEX Zone 1 실내에서 고전압 인버터가 필요 없는 자발광형 픽셀을 선호함에 따라, OLED 패널 시장은 연평균 성장률(CAGR) 21.53%로 확대될 것으로 예측됩니다. LG디스플레이는 2025년 10월, 15.6인치 패널에 대한 IECEx 인증을 획득하여 해양 시설 및 정유시설 프로젝트에서 비즈니스 기회를 개척했습니다. LED 직접 뷰 어레이는 주변 조도가 50,000 룩스를 초과하는 실외 변전소에서 사용되고 있지만, 전자 종이는 저전력 피킹 스테이션을 위한 틈새 솔루션에 그치고 있습니다.
병원 수술실에서는 무한한 명암비 덕분에 희미한 조명 아래에서도 가시성이 향상됩니다. 지멘스 헬스인어즈는 2025년에 340개의 수술실에 27인치 유기EL 모니터를 도입했으며, 외과의사는 LCD 모델에 비해 18% 더 빠르게 이상을 감지할 수 있었습니다. 두께 6mm의 슬림한 디자인은 천장 붐에 쉽게 통합될 수 있으며, 무균 기류 요건도 충족합니다.
12-23인치 크기 대는 맞춤형 제조 분야와의 높은 친화성 덕분에 2025년에도 39.56%의 점유율을 유지했습니다. 32인치 이상의 디스플레이는 자동차 제조업체들이 수백 대의 프로그래머블 로직 컨트롤러(PLC)에서 데이터를 집계하는 비디오월을 도입함에 따라 연평균 20.66%의 성장이 예상됩니다. BMW의 스파르탄버그 공장에서는 2025년에 43인치 유닛을 도입하여 예기치 않은 가동 중단 시간을 23% 줄였습니다.
제약 업계의 사용자들은 무균실 내에 55인치 터치스크린을 설치하여 클린존을 벗어나지 않고도 배치 기록을 확인하고 있습니다. 머크의 다름슈타트 공장에서는 2025년에 56대의 대형 스크린을 도입한 결과, 처리 주기를 5일 단축했습니다. 12인치 미만의 견고한 패널은 전력 제한으로 인해 백라이트 와트수가 제한되는 모바일 로봇이나 휴대용 진단 기기에서 여전히 필수적입니다.
지역별 분석
아시아태평양은 중국의 로봇 도입 의무화 및 인도의 전자 산업 클러스터를 뒷받침하는 보조금 덕분에 2025년에 41.88%의 점유율을 차지했습니다. 한국의 첨단 반도체 제조 공장에서는 2025년에 극자외선 리소그래피용으로 1만 8,000대의 오픈 프레임 디스플레이가 도입되었으며, 일본 경제산업성의 보고에 따르면 중소기업의 코봇 도입률은 68%에 달했습니다. 이러한 프로젝트들은 산업용 모니터 시장에서 화학 미스트에 내성이 있는 고해상도 패널을 선호하여 채택하고 있습니다.
남미 시장은 브라질의 ‘Rota 2030’ 프로그램과 아르헨티나의 바카 무에르타 셰일가스 개발에 따른 방폭 모니터 수요에 힘입어 연평균 22.44%의 성장률이 예상됩니다. 페트로브라스는 2025년 말, 프레솔트층 플랫폼을 위해 이러한 유형의 모니터 2,400대에 대한 계약을 체결했습니다. 지역 유통업체은 ANATEL의 전자파 규정을 준수하는 현장 교정 서비스를 제공하는 상파울루 서비스 거점에 투자하고 있습니다.
북미 및 유럽에서는 한 자릿수 중반대의 성장률이 예상됩니다. 교체 주기가 주류를 이루고 있지만, ‘CHIPS and Science Act’ 및 EU의 ‘Net-Zero Industry Act’에 따른 생산 거점의 국내 복귀(리쇼어링)로 인해 4K 대형 디스플레이가 필요한 새로운 반도체 및 배터리 기가팩토리가 촉진되고 있습니다. 중동의 정유시설에서는 비디오월을 도입해 제어실을 업그레이드하고 있으며, 아프리카의 광업 부문에서는 광범위한 온도 범위를 지원하는 패널을 활용해 운영자 부스의 현대화를 추진하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the industrial monitor market size is USD 11.08 billion in 2025, USD 11.85 billion in 2026, and will reach USD 15.74 billion by 2031, growing at a CAGR of 5.84% from 2026 to 2031.
This report is Segmented by Display Technology (LCD, LED, OLED, E-Papers, and More), Screen Size (Less Than 12 Inch, 12-23 Inch, and More), Mounting Type (Panel-Mount, Rack-Mount, and More), End-Use Industry (Automotive Manufacturing, Oil and Gas, Logistics and Transportation, Medical and Healthcare, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Monitor Market Trends and Insights
Surge in Smart-Factory Retrofits
Small and medium manufacturers are grafting new human-machine interfaces onto long-lived machines to harvest live overall equipment effectiveness data without purchasing replacement assets. Plattform Industrie 4.0 reported that 68% of German SMEs added at least one networked display between 2024 and 2025. Siemens observed retrofit monitor revenue rising 22% year on year in 2025 and noted a three-to-one sales ratio favoring retrofits over greenfield lines in Europe and North America. Retrofit buyers specify IP65 sealed bezels, VESA mounts, and protocol-agnostic Ethernet to shorten installation downtime. The specification trend funnels orders toward suppliers offering modular displays that interface with Profinet, EtherCAT, and Modbus TCP stacks.
Expanding Edge-AI Vision Inspection Demand
Electronics and auto assemblers now link compact vision sensors to nearby industrial monitors, allowing technicians to validate defect flags in real-time. Cognex shipped 1.2 million In-Sight SnAPP sensors in 2025, up 34% over 2024, with 61% deployed in Asia-Pacific battery and electronics plants. Tesla's Gigafactory Berlin installed 480 inspection cells in 2025, each featuring a 23-inch touchscreen that lets operators retrain convolutional networks on the spot. These stations require 4K resolution at 60Hz refresh and embedded graphics processors, driving demand for higher-performance panels in the industrial monitor market.
Persistent Supply-Chain Volatility for Industrial-Grade TFT Glass
Only three vendors supply alkali-free glass that endures -30 °C to +80 °C duty cycles, so any outage hits the Industrial monitor market quickly. Corning reported 94% capacity utilization for Eagle XG in Q4 2025 and lead times ballooned to 18 weeks, double that for consumer glass. A March 2025 fire at AGC's Takasago line sidelined 12% of global capacity for seven months, forcing monitor makers to redesign housings for thicker substrates or delay shipments. Spot prices for 15-inch industrial sheets swung between USD 42 and USD 68 in 2025, compressing already thin gross margins.
Other drivers and restraints analyzed in the detailed report include:
- Tightening OSHA and EU Machinery Safety Rules
- Growth of Battery-Powered Autonomous Mobile Robots
- Rising Cybersecurity Certification Costs for IIoT-Ready Monitors
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Liquid-crystal displays held 61.21% share in 2025, underpinned by entrenched backlight supply chains. Organic light-emitting diode panels are forecast to climb at a 21.53% CAGR as oil and gas operators favor self-emissive pixels that remove high-voltage inverters in ATEX Zone 1 rooms. LG Display secured IECEx certification for a 15.6-inch panel in October 2025, thereby unlocking opportunities in offshore and refinery projects. Light-emitting diode direct-view arrays are used in outdoor substations where ambient light exceeds 50,000 lux, while e-paper remains a niche solution for low-power picking stations.
In hospital surgical suites, infinite contrast enhances visualization under dim lights. Siemens Healthineers rolled out 27-inch organic light-emitting diode monitors to 340 operating rooms in 2025 and surgeons flagged anomalies 18% faster than with liquid-crystal models. The slim 6 millimeter profile eases ceiling boom integration and supports sterile airflow requirements.
The 12-23 inch range maintained 39.56% share in 2025 owing to familiarity in discrete manufacturing. Displays above 32 inches are projected to grow at a rate of 20.66% annually as automakers deploy video walls that aggregate data from hundreds of programmable logic controllers. BMW's Spartanburg plant installed 43-inch units in 2025 and cut unplanned downtime by 23%.
Pharmaceutical users are installing 55-inch touchscreens in aseptic suites to review batch records without leaving clean zones. Merck's Darmstadt site shortened disposition cycles by five days after installing 56 large screens in 2025. Sub-12-inch rugged panels stay essential for mobile robots and handheld diagnostic devices where power budgets limit backlight wattage.
Complete Report Scope:
- By Display Technology
- LCD
- LED
- OLED
- E-papers and Others
- By Screen Size
- Less than 12 Inch
- 12- 23 Inch
- 23- 32 Inch
- Greater than 32-inch
- By Mounting Type
- Panel-mount
- Rack-mount
- VESA/Arm-mount
- Open-frame/Chassis
- By End-Use Industry
- Automotive Manufacturing
- Oil and Gas
- Logistics and Transportation
- Medical and Healthcare
- Metals and Mining
- Food and Beverage
- Semiconductors and Electronics
- Other End-Use Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific commanded 41.88% share in 2025 due to robotics mandates in China and subsidies in India that fuel electronics clusters. South Korea's advanced fabs installed 18,000 open-frame displays in 2025 for extreme-ultraviolet lithography, and Japan's Ministry of Economy, Trade, and Industry reported a 68% adoption rate of cobots among SMEs. These projects favor high-resolution panels that resist chemical mists in the industrial monitor market.
South America is forecast to grow at a rate of 22.44% annually, driven by the demand for explosion-proof monitors from Brazil's Rota 2030 program and Argentina's Vaca Muerta shale expansion. Petrobras awarded contracts for 2,400 such units in late 2025 for pre-salt platforms. Regional distributors are investing in Sao Paulo service hubs that offer on-site calibration compliant with ANATEL electromagnetic rules.
North America and Europe are expected to progress at mid-single-digit rates. Replacement cycles dominate but reshoring under the CHIPS and Science Act and the EU Net-Zero Industry Act promotes new semiconductor and battery gigafactories that need 4K large-format displays. Middle Eastern refineries are upgrading control rooms with video walls, while Africa's mining sector modernizes operator booths with wide-temperature panels.
- Advantech Co., Ltd.
- Kontron AG
- ADLINK Technology Inc.
- Sparton LLC
- Siemens AG
- Rockwell Automation, Inc.
- Hope Industrial Systems, Inc.
- Pepperl+Fuchs SE
- AAEON Technology Inc.
- Axiomtek Co., Ltd.
- National Instruments Corporation
- Mitsubishi Electric Corporation
- Schneider Electric SE
- Barco NV
- Winmate Inc.
- Red Lion Controls, Inc.
- EIZO Corporation
- Planar Systems, Inc.
- Beckhoff Automation GmbH & Co. KG
- Emerson Electric Co.
- General Electric Company
- Brainchild Electronics Co., Ltd.
- IEI Integration Corp.
- Phoenix Contact GmbH & Co. KG
- Omron Corporation
- Honeywell International Inc.
- GVision USA Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Smart- factory Retrofits
- 4.2.2 Expanding Edge-AI Vision Inspection Demand
- 4.2.3 Tightening OSHA and EU Machinery Safety Mandates
- 4.2.4 Growth of Battery- powered Autonomous Mobile Robots (AMRs)
- 4.2.5 Phasing-out of Cathode-ray and CCFL Monitors and Legacy Lines
- 4.2.6 OEM Bundling of Panel PCs with Industrial Monitors
- 4.3 Market Restraints
- 4.3.1 Persistent Supply-chain Volatility for Industrial-grade TFT Glass
- 4.3.2 High Capital Cost of IEC-Ex/ATEX-rated Displays
- 4.3.3 Margins Squeezed by Commoditization of Mid-size LCD Panels
- 4.3.4 Rising Cybersecurity Certification Costs for IIoT-ready Monitors
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Display Technology
- 5.1.1 LCD
- 5.1.2 LED
- 5.1.3 OLED
- 5.1.4 E-papers and Others
- 5.2 By Screen Size
- 5.2.1 Less than 12 Inch
- 5.2.2 12- 23 Inch
- 5.2.3 23- 32 Inch
- 5.2.4 Greater than 32-inch
- 5.3 By Mounting Type
- 5.3.1 Panel-mount
- 5.3.2 Rack-mount
- 5.3.3 VESA/Arm-mount
- 5.3.4 Open-frame/Chassis
- 5.4 By End-Use Industry
- 5.4.1 Automotive Manufacturing
- 5.4.2 Oil and Gas
- 5.4.3 Logistics and Transportation
- 5.4.4 Medical and Healthcare
- 5.4.5 Metals and Mining
- 5.4.6 Food and Beverage
- 5.4.7 Semiconductors and Electronics
- 5.4.8 Other End-Use Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Advantech Co., Ltd.
- 6.4.2 Kontron AG
- 6.4.3 ADLINK Technology Inc.
- 6.4.4 Sparton LLC
- 6.4.5 Siemens AG
- 6.4.6 Rockwell Automation, Inc.
- 6.4.7 Hope Industrial Systems, Inc.
- 6.4.8 Pepperl+Fuchs SE
- 6.4.9 AAEON Technology Inc.
- 6.4.10 Axiomtek Co., Ltd.
- 6.4.11 National Instruments Corporation
- 6.4.12 Mitsubishi Electric Corporation
- 6.4.13 Schneider Electric SE
- 6.4.14 Barco NV
- 6.4.15 Winmate Inc.
- 6.4.16 Red Lion Controls, Inc.
- 6.4.17 EIZO Corporation
- 6.4.18 Planar Systems, Inc.
- 6.4.19 Beckhoff Automation GmbH & Co. KG
- 6.4.20 Emerson Electric Co.
- 6.4.21 General Electric Company
- 6.4.22 Brainchild Electronics Co., Ltd.
- 6.4.23 IEI Integration Corp.
- 6.4.24 Phoenix Contact GmbH & Co. KG
- 6.4.25 Omron Corporation
- 6.4.26 Honeywell International Inc.
- 6.4.27 GVision USA Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


