

|
시장보고서
상품코드
2124105
유도 전동기 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Induction Motor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
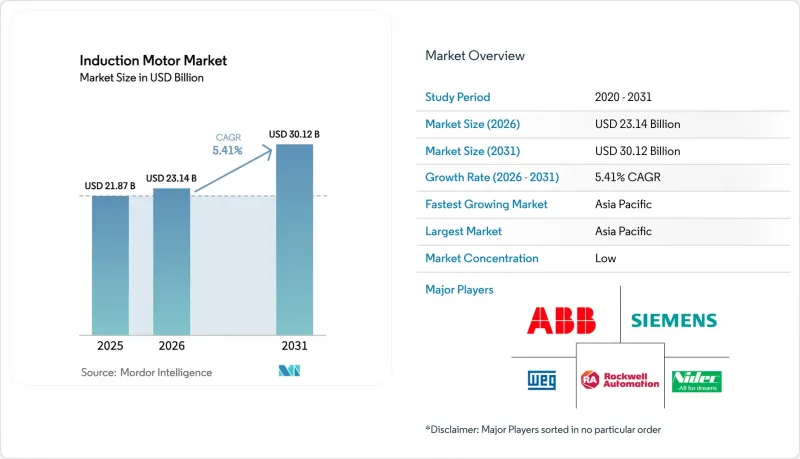
에 의하면, 유도 전동기 시장 규모는 2025년 218억 7,000만 달러로 평가되었고, 2026년에는 231억 4,000만 달러로 추정되고, 2031년까지 301억 2,000만 달러에 이를 것으로 예상되며, 2026-2031년 CAGR 5.41%로 성장할 전망입니다.
본 보고서는 로터 유형별(케이지형 유도 전동기 등), 상수별(단상 유도 전동기, 3상 유도 전동기), 효율 등급별(IE1 표준 효율 등), 용도별(펌프, 팬 및 송풍기 등), 최종 사용자 산업별(제조업, 석유 및 가스·화학 산업 등), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 유도 전동기 시장 동향 및 인사이트력
산업 시스템에서 고효율 모터 기준의 채택 확대
산업용 모터 시스템은 전력 소비의 큰 비중을 차지하고 있으며, 에너지 효율화 정책은 성능 향상 및 개조 주기에서 가장 강력한 추진력이 되고 있습니다. 유럽연합(EU)의 에코디자인 프레임워크에서는 2023년 중반부터 75-200kW의 3상 모터에 대해 IE4를 최저 기준으로 정하고 있습니다. 한편, 미국에서는 2024년 1월에 팬 및 송풍기 기준이 최종 확정되어, 상업용 및 산업용 공기 시스템 전반에 걸쳐 가변 속도 및 고효율 모터와 드라이브의 조합이 촉진되고 있습니다. 중국의 GB 18613-2020에서는 0.75-375 kW 용량의 모터 기준이 IE3로 상향 조정되어 지역 간 격차가 축소됨과 동시에, 프리미엄 효율 설계를 위한 기준이 확립되었습니다. 2025년에 공표된 유엔 주도의 모델 규정은 각국이 도입을 가속화하기 위한 지침이 되었으며, 시행 준비 상황이 다른 시장별로 단계적인 이행 경로가 마련되어 있습니다. 이러한 규제로 인해 구매 기준은 수명 주기 성능으로 전환되며, IE3 및 IE4 모터로의 업그레이드와 펌프 및 팬에 대한 VFD의 보다 광범위한 도입이 촉진될 것입니다. IEC 및 각국 기관에 의한 통일된 시험 프로토콜을 통해 기술적 모호성이 해소되어, 유도 전동기 시장이 표준화된 규정 준수를 통한 비용 절감 효과를 누릴 수 있게 될 것입니다.
산업 자동화 및 공정 최적화 프로그램의 가속화
공장의 현대화 및 디지털화가 진행됨에 따라 가변 부하 조건에서 효율적으로 작동하는 통합형 모터·드라이브 패키지에 대한 수요가 증가하고 있습니다. 가변 주파수 드라이브(VFD)는 가변 토크 응용 분야에서 에너지 소비를 줄여주며, HVAC(냉난방·환기),송수, 자재관리 분야의 현대화 프로그램에서 핵심적인 역할을 수행하고 있습니다. 미국의 팬 및 송풍기 설계 기준에는 규정 준수를 달성하기 위한 수단으로 가변 속도가 포함되어 있으며, 이는 신규 및 개조 프로젝트의 모터 선정 및 제어 전략에도 반영되고 있습니다. 각 OEM 업체들은 더 많은 축 수, 더 엄격한 안전 기능, 그리고 더 간단한 통합을 지원할 수 있도록 드라이브 플랫폼을 업데이트하고 있으며, 이를 통해 대규모 자동화 도입 시 총 소유 비용이 절감되고 있습니다. 3상 유도 전동기와 결합함으로써 드라이브는 부분 부하 시 효율을 향상시키고, 기계적 스트레스를 줄이며, 높은 듀티 사이클에서 수명을 연장합니다. 산업 사용자가 에너지 효율과 가동 시간 향상을 우선시함에 따라 이러한 추세는 계속해서 유도 전동기 시장을 뒷받침하고 있습니다.
영구자석 모터 및 동기 릴랙턴스 모터와 같은 대체 기술과의 경쟁
영구자석 모터는 많은 가동 사이클에서 효율 면에서 우위를 차지하며, 팬 및 송풍기와 관련된 최근 규정에서는 전자 정류 방식의 설계가 송풍 장비의 최고 기준으로서 인정받고 있습니다. 동기 릴랙턴스 모터는 자석을 사용하지 않고도 IE5 등급의 성능을 달성하고 있으며, 적합한 구동 장치와 결합함으로써 위험이 낮고 고효율적인 대안으로 자리 잡고 있습니다. 이러한 대체 제품들은 최고 성능이나 컴팩트한 형상을 우선시하는 부문에서 프리미엄 효율에 대한 수요를 잠식할 가능성이 있습니다. 하지만 이러한 모터는 가변 속도 제어가 필요하며, 직접 기동(DOL)으로 운전할 수 없기 때문에 정속 운전이나 가혹한 환경에서는 여전히 유도 전동기의 역할이 유지되고 있습니다. 영구 자석 설계의 경우, 자석 공급 집중 및 가격 변동이 계속해서 우려 사항으로 남아 있어, 총비용 및 위험의 관점에서 자석을 사용하지 않는 접근 방식의 매력은 여전히 유효합니다. 각 OEM 업체의 로드맵과 신제품 발표에는 이러한 균형이 반영되어 있으며, 기업들은 다양한 사용자의 요구에 부응하기 위해 유도 모터, SynRM, PM 등 각 제품 라인에 걸친 포트폴리오를 구축하고 있습니다.
부문 분석
케이지형 유도 전동기는 2025년에 유도 전동기 시장 점유율의 55%를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 7.34%로 성장할 것으로 전망됩니다. 이러한 선도적 지위는 브러쉬리스 로터 구조, 견고한 다이캐스팅 바 및 엔드 링, 그리고 가혹한 가동 주기 하에서도 유지보수가 적게 필요하다는 점에 힘입고 있습니다. 각 지역에서 IE3 및 IE4 준수가 진행됨에 따라, 권선, 베어링,절연이 최적화된 인버터 구동용 유도 전동기가 최신 드라이브와의 표준 조합으로 자리 잡았습니다. 구리 로터를 채택한 기종은 로터 손실을 줄이고 희토류 자석을 사용하지 않으면서도 효율 향상을 실현하고 있어, 프리미엄 부문에서의 채택을 촉진하고 있습니다. IEC의 시험 및 효율 분류 체계는 사인파 및 VFD 급전 조건에 걸친 비교 벤치마크를 제공하여, 조달 팀이 수명 주기 비용 절감 효과를 평가하는 데 도움을 주고 있습니다. 유도 전동기 시장에서는 산업 분야의 펌프, 팬, 컨베이어 및 범용 구동 장치에서 견고한 케이지형 설계가 여전히 선호되고 있습니다.
권선 로터 설계는 대형 호이스트나 슬러리 펌프 등 정밀한 토크 프로파일을 위해 외부 로터 저항이 필요한 틈새 용도로만 제한되어 있습니다. VFD 구동식 케이지형 로터 모터는 브러시나 슬립 링이 필요 없는 동적 제어를 실현함으로써, 많은 경우 권선형 로터 모터를 대체하고 있습니다. 이러한 전환으로 인해 유지보수가 줄어들고 수명이 연장되므로, 사업자의 장기적인 비용 결정에 영향을 미치고 있습니다. 각 OEM 업체들이 구리 로터공급 범위를 대형 프레임으로 확대함에 따라, 설치 기반은 동등한 설치 면적에서 더 높은 효율을 자랑하는 유도 전동기 플랫폼으로 전환될 것입니다. 브레이크 모터나 방폭형 유닛 등, 기존에는 적용 대상에서 제외되었던 모터 범주에 대한 IE3 및 IE4 규제로 인해, 나머지 설치 기반도 고효율 수준으로 끌어올려지고 있습니다. 이러한 기술적 및 규제적 동향이 유도 전동기 시장에서 케이지형 구조 시장 점유율 안정을 뒷받침하고 있습니다.
2025년에는 단상 모터가 주거용 및 소마력 용도를 중심으로 53%의 점유율을 차지했지만, 3상 모터는 2031년까지 연평균 성장률(CAGR) 6.76%로 확대될 것으로 예측됩니다. 3상 모터는 더 높은 토크 밀도, 더 부드러운 작동, 그리고 더 우수한 역률을 실현하기 때문에 산업용 및 상업시설에서 표준적인 선택지로 자리 잡고 있습니다. 가변 속도 드라이브(VFD)를 통해 유량과 압력을 정밀하게 제어할 수 있으므로 펌프나 팬과 같은 가변 토크 부하에서 에너지 절약 효과를 얻을 수 있습니다. 유럽연합(EU) 및 중국의 프리미엄 효율 기준 도입은 상업용 HVAC 및 경공업 분야에서 3상 모터로의 교체를 촉진하고 있습니다. 많은 개조 공사에서 VFD가 장착된 3상 모터로 전환하면 부분 부하 시 성능이 향상되고 기계적 마모가 감소합니다. 자동화와 에너지 효율이 설계상의 주요 목표가 되는 가운데, 이러한 추세는 유도 전동기 시장에서 3상 아키텍처의 채택을 뒷받침하고 있습니다.
산업용 배전 규격에서는 400V, 460V 또는 575V의 3상 전원이 권장되며, 이를 통해 고부하용 모터 선정이 간소화됩니다. 다양한 극수 구성과 프레임 크기를 갖춘 모듈형 제품군을 통해 가동 중단 시간을 최소화하는 드롭인 교체가 가능합니다. 디지털 명판과 단일 케이블 기술을 통한 통합 피드백 덕분에 최신 제어 시스템을 활용한 시운전이 신속하게 이루어집니다. 드라이브 및 게이트웨이에 내장된 예측 유지보수 도구는 정확한 진단을 위해 안정적인 3상 파형에 의존하며, 이는 신뢰성 목표를 보완합니다. 상업용 빌딩 및 공장에서 VFD가 장착된 3상 모터가 표준화됨에 따라, 운영자는 통일된 유지보수 절차의 이점을 누릴 수 있습니다. 유도 모터 시장에서는 일반적인 크기 범위에 걸친 카탈로그 제품 라인업 확충 및 인버터 대응 정격 제공 등을 통해 이러한 추세가 반영되고 있습니다.
지역별 분석
아시아태평양은 2025년에 62%의 점유율을 차지한 것으로 평가되었으며, 해당 지역의 생산 고도화와 최종 용도 수요가 상호 보완적 관계를 형성함에 따라 2031년까지 연평균 성장률(CAGR) 6.98%로 성장할 것으로 전망됩니다. 반도체 제조 공장(팹), 자동차 조립 및 수출 지향형 제조업이 모터 및 드라이브의 다년간 조달 파이프라인의 기반을 형성하고 있습니다. 또한, IE3 이상의 기준을 준수하는 지역 정책도 대형 프레임 크기의 프리미엄 효율 제품 채택을 뒷받침하고 있습니다. 주요 연안 시장에서는 수처리 및 고효율 HVAC가 우선시되고 있으며, 그 결과 3상·VFD 최적화 시스템에 대한 수주가 안정적으로 유입되고 있습니다. 현재 사이클을 통해 더 많은 팹 프로젝트가 예정되어 있어, 클린룸용 HVAC, 펌프 및 핸들링 시스템은 계속해서 견조한 수요원을 형성하고 있습니다. 이러한 요인들로 인해 유도 전동기 시장은 아시아태평양의 산업 발전에 있어 필수적인 공급원으로서의 입지를 확고히 하고 있습니다.
북미는 개보수 공사의 품질과 수명 주기 서비스를 중시하는 성숙한 시장으로서, 전 세계 활동의 18-20%를 지속적으로 차지하고 있습니다. 미국에서 팬 및 송풍기에 관한 규제가 제정됨에 따라 가변 속도가 규정 준수를 달성하는 수단으로 공식적으로 인정받게 되어, 고효율 모터 및 드라이브의 비즈니스 타당성이 강화되고 있습니다. 니어쇼어링의 진전에 따라, 자동차 및 전자제품 공급망을 뒷받침하는 멕시코 공장의 모터 수요가 증가하고 있습니다. 데이터센터 건설은 엄격한 가동률 목표 하에서 작동하는 고효율 HVAC 모터 및 정밀 시스템에 대한 수주를 지속적으로 견인하고 있습니다. 각 OEM 업체들은 첨단 HVAC 및 모션 제품에 대응하는 새로운 조립 및 시험 라인을 포함하여 미국 내 생산 능력에 투자하고 있습니다. 이러한 움직임은 에너지 기준과 인프라 투자가 지출 우선순위를 결정하는 가운데 유도 전동기 시장을 강화하고 있습니다.
유럽 시장 점유율은 15-17%이며, 엄격한 에코디자인 요건과 위험 구역, 해양, 중공업 분야의 프리미엄 용도 수요에 의해 형성되고 있습니다. 75-200kW 범위에서 IE4 의무화뿐만 아니라, 더 광범위한 대역에 걸친 IE3 적용 범위로 인해 사용자들은 계속해서 더 높은 효율 수준으로 전환하도록 유도되고 있습니다. 각 OEM 업체들은 IECEx 및 ATEX 인증을 충족하는 방폭 모터의 유럽 내 생산 능력을 확대되고 있습니다. 이 지역의 에너지 효율에 대한 집중으로 인해 IE4 및 통합형 구동 솔루션은 펌프 및 팬 분야에서 매력적인 선택지가 되고 있습니다. 이러한 요인들이 일관된 규정 준수 및 추적 가능한 성능이 요구되는 EU 전 산업 분야의 유도 전동기 시장을 뒷받침하고 있습니다. 지역 내 생산 및 서비스 체계에 대한 투자를 통해 복잡한 프로젝트에 신속하게 대응할 수 있게 되었습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the induction motor market size is expected to increase from USD 21.87 billion in 2025 to USD 23.14 billion in 2026 and reach USD 30.12 billion by 2031, growing at a CAGR of 5.41% over 2026-2031.
This report is Segmented by Rotor Type (Squirrel-Cage Induction Motors, and More), Phase (Single-Phase Induction Motors, Three-Phase Induction Motors), Efficiency Class (IE1 Standard Efficiency, and More), Application (Pumps, Fans and Blowers, and More), End-User Industry (Manufacturing, Oil and Gas and Chemicals, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Induction Motor Market Trends and Insights
Rising Adoption of Energy-Efficient Motor Standards in Industrial Systems
Industrial motor systems account for a significant share of electricity use, making energy-efficiency policies the single strongest lever for performance upgrades and retrofit cycles. The European Union's Ecodesign framework set IE4 as the minimum for 75-200 kW three-phase motors from mid-2023. Meanwhile, the United States finalized fan and blower standards in January 2024, which promote variable speed and high-efficiency motor-drive pairings across commercial and industrial air systems. China's GB 18613-2020 has moved the baseline to IE3 for motors with a capacity of 0.75-375 kW, narrowing regional gaps and creating a scale for premium-efficiency designs. UN-led model regulations, published in 2025, provide a template for countries to accelerate adoption, with differentiated pathways for markets at varying levels of enforcement readiness. These rules shift purchase criteria toward lifecycle performance, which supports upgrades to IE3 and IE4 motors and broader deployment of VFDs in pumps and fans. Harmonized test protocols from IEC and national bodies reduce technical ambiguity and help the induction motors market capture savings from standardized compliance.
Acceleration of Industrial Automation and Process Optimization Programs
Factory modernization and digital operations are increasing demand for integrated motor-drive packages that operate efficiently at variable load. Variable frequency drives reduce energy consumption in variable torque applications and are central to modernization programs in HVAC, water pumping, and materials handling. Design standards for fans and blowers in the United States embed variable speed as a pathway to compliance, which filters through to motor selection and control strategies in new and retrofit projects. OEMs have updated drive platforms to support higher axis counts, tighter safety functions, and simpler integration, which lowers total cost of ownership for large-scale automation deployments. When paired with three-phase induction motors, drives improve part-load efficiency and reduce mechanical stress, extending service life in high-duty cycles. These dynamics continue to support the induction motors market as industrial users prioritize energy and uptime gains.
Competition from Permanent-Magnet and Synchronous-Reluctance Motor Alternatives
Permanent-magnet machines hold an efficiency edge in many duty cycles, and recent rules for fans and blowers acknowledge electronically commutated designs as the top-tier benchmark in air-moving equipment. Synchronous reluctance motors achieve IE5-class performance without magnets and are being positioned as lower-risk, high-efficiency options when paired with matched drives. These alternatives can divert premium-efficiency demand in segments that prioritize peak performance and compact form factors. That said, they require variable speed control and cannot operate direct-on-line, which preserves the role of induction motors in fixed-speed and rugged environments. Magnet supply concentration and price swings remain a concern for permanent-magnet designs, which keeps magnet-free approaches attractive on total cost and risk grounds. OEM roadmaps and product launches reflect this balance as companies hedge portfolios across induction, SynRM, and PM lines to meet diverse user needs.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Water and Wastewater Infrastructure Requiring Pumping Capacity
- Manufacturing Capacity Additions in Asia-Pacific and Supply Chain Reconfiguration
- Magnet-Free Design Preference Amid Rare-Earth Supply Risk in High-Power Drives
- Advances in Cast-Copper Rotor and Inverter-Duty Designs Improving Efficiency
- Volatility in Copper and Aluminum Prices Pressuring Motor BOM Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Squirrel-cage induction motors held 55% of the induction motors market share in 2025 and are forecast to grow at a 7.34% CAGR through 2031. This leadership rests on brushless rotor construction, robust die-cast bars and end rings, and low maintenance in harsh duty cycles. As compliance moved to IE3 and IE4 across regions, inverter-duty induction motors with optimized windings, bearings, and insulation became a standard pairing with modern drives. Copper-rotor variants have reduced rotor losses, enabling efficiency gains without rare-earth magnets, supporting adoption in premium tiers. IEC test and efficiency classification frameworks provide comparative benchmarks across sinusoidal and VFD-fed conditions, helping procurement teams evaluate lifecycle savings. The induction motors market continues to see specification preferences for rugged squirrel-cage designs in pumps, fans, conveyors, and general-purpose drives in industry.
Wound-rotor designs remain in niche roles that require external rotor resistance for precise torque profiles, including large hoists and slurry pumps. VFD-driven squirrel-cage alternatives have displaced wound-rotor options in many cases by offering dynamic control without brushes or slip rings. This shift reduces maintenance and extends service life, which influences long-term cost decisions for operators. As OEMs extend copper-rotor availability to larger frames, the installed base will shift toward more efficient induction platforms at similar footprint. IE3 and IE4 rules for previously exempt motor categories, such as brake motors and explosion-proof units, are pulling the rest of the base toward premium tiers. These technical and regulatory trends support share stability for squirrel-cage configurations in the induction motors market.
Single-phase motors held 53% share in 2025, centered in residential and fractional-HP uses, while three-phase motors are forecast to expand at a 6.76% CAGR through 2031. Three-phase machines deliver higher torque density, smoother operation, and better power factor, which makes them the default choice in industrial and commercial installations. Variable speed drives allow precise control of flow and pressure, which unlocks energy savings in variable torque loads like pumps and fans. The move toward premium efficiency standards in both the European Union and China incentivizes three-phase upgrades in commercial HVAC and light industrial settings. In many retrofits, swapping to three-phase motors with VFDs improves part-load performance and reduces mechanical wear. These dynamics reinforce adoption of three-phase architectures in the induction motors market as automation and energy efficiency become core design goals.
Industrial distribution standards favor three-phase power at 400 V, 460 V, or 575 V, which simplifies motor selection for larger loads. Modular product families with multiple pole configurations and frame sizes support drop-in replacements that minimize downtime. Digital nameplates and integrated feedback via single-cable technologies make commissioning faster with modern controls. Predictive monitoring tools built into drives and gateways rely on stable three-phase waveforms for accurate diagnostics, which complements reliability goals. As commercial buildings and factories standardize on three-phase motors with VFDs, operators benefit from unified maintenance practices. The induction motors market reflects these preferences with broader catalog coverage and inverter-duty ratings across common size ranges.
Complete Report Scope:
- By Rotor Type
- Squirrel-Cage Induction Motors
- Wound-Rotor Induction Motors
- By Phase
- Single-Phase Induction Motors
- Three-Phase Induction Motors
- By Efficiency Class
- IE1 Standard Efficiency Induction Motors
- IE2 High Efficiency Induction Motors
- IE3 Premium Efficiency Induction Motors
- IE4 Super Premium Efficiency Induction Motors
- IE5 Ultra Premium Efficiency Induction Motors
- By Application
- Pumps
- Fans and Blowers
- Compressors
- Conveyors and Material Handling
- Elevators and Cranes
- HVAC Equipment
- Other Applications
- By End-User Industry
- Manufacturing
- Oil and Gas and Chemicals
- Power Generation and Utilities
- Water and Wastewater
- Mining and Metals
- Commercial and Buildings
- Transportation
- Residential
- Other End-User Industry
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Israel
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
The Asia-Pacific region held a 62% share in 2025 and is projected to grow at a 6.98% CAGR through 2031, as production depth and end-use demand reinforce each other in the region. Fabs, automotive assembly, and export-oriented manufacturing anchor multi-year procurement pipelines for motors and drives. Regional policy alignment with IE3 and above also supports the adoption of premium efficiency in larger frame sizes. Major coastal markets prioritize water treatment and high-efficiency HVAC, resulting in a steady order flow for three-phase, VFD-optimized systems. With more fab projects scheduled through the current cycle, cleanroom HVAC, pumps, and handling systems remain a reliable pull. These factors support the induction motor market as a critical supplier to APAC industrial development.
North America maintains an 18-20% range of global activity as a mature base that emphasizes retrofit quality and lifecycle services. The United States rulemaking for fans and blowers formalizes variable speed as a compliance pathway and strengthens the business case for high-efficiency motors and drives. Nearshoring has increased demand for motors in Mexican plants serving automotive and electronics supply chains. Data-center construction continues to drive orders for high-efficiency HVAC motors and precision systems that operate within strict uptime targets. OEMs invest in U.S. capacity, including new assembly and testing lines that are aligned with advanced HVAC and motion products. These actions strengthen the induction motors market as energy standards and infrastructure investments guide spending priorities.
Europe's share is 15-17% and is shaped by strict Ecodesign requirements and premium application demand in hazardous areas, offshore, and heavy industry. IE4 mandates in the 75-200 kW range, along with IE3 coverage across broader bands, continue to encourage users to move to higher tiers. OEMs have expanded European capacity for explosion-proof motors that meet IECEx and ATEX certifications. The region's focus on energy efficiency makes IE4 and integrated drive solutions attractive in pumps and fans. These drivers sustain the induction motors market across EU industries that demand consistent compliance and traceable performance. Investments in regional production and service capabilities support fast turnaround for complex projects.
- ABB Ltd.
- Siemens AG
- WEG S.A.
- Nidec Corporation
- Wolong Electric Group Co., Ltd.
- Regal Rexnord Corporation
- TECO Electric and Machinery Co., Ltd.
- Toshiba Corporation
- Toshiba Mitsubishi-Electric Industrial Systems Corporation
- Getriebebau NORD GmbH & Co. KG
- SEW-EURODRIVE GmbH & Co KG
- CG Power and Industrial Solutions Limited
- Kirloskar Electric Company Limited
- Rockwell Automation Inc.
- Hitachi, Ltd.
- Yaskawa Electric Corporation
- Oriental Motor Co., Ltd.
- Bonfiglioli Riduttori S.p.A.
- Sumitomo Heavy Industries, Ltd.
- Brook Crompton UK Limited
- Hyundai Electric and Energy Systems Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Adoption of Energy-Efficient Motor Standards in Industrial Systems
- 4.2.2 Acceleration of Industrial Automation and Process Optimization Programs
- 4.2.3 Expansion of Water and Wastewater Infrastructure Requiring Pumping Capacity
- 4.2.4 Manufacturing Capacity Additions in Asia-Pacific and Supply Chain Reconfiguration
- 4.2.5 Magnet-Free Design Preference Amid Rare-Earth Supply Risk in High-Power Drives
- 4.2.6 Advances in Cast-Copper Rotor and Inverter-Duty Designs Improving Efficiency
- 4.3 Market Restraints
- 4.3.1 Competition from Permanent-Magnet and Synchronous-Reluctance Motor Alternatives
- 4.3.2 Upfront Price Premium of Premium-Efficiency Motors and VFD Retrofits
- 4.3.3 Volatility in Copper and Aluminum Prices Pressuring Motor BOM Costs
- 4.3.4 EC Fan Adoption in HVAC Displacing Traditional Induction Motors in Buildings
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value / Supply-Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (Value)
- 5.1 By Rotor Type
- 5.1.1 Squirrel-Cage Induction Motors
- 5.1.2 Wound-Rotor Induction Motors
- 5.2 By Phase
- 5.2.1 Single-Phase Induction Motors
- 5.2.2 Three-Phase Induction Motors
- 5.3 By Efficiency Class
- 5.3.1 IE1 Standard Efficiency Induction Motors
- 5.3.2 IE2 High Efficiency Induction Motors
- 5.3.3 IE3 Premium Efficiency Induction Motors
- 5.3.4 IE4 Super Premium Efficiency Induction Motors
- 5.3.5 IE5 Ultra Premium Efficiency Induction Motors
- 5.4 By Application
- 5.4.1 Pumps
- 5.4.2 Fans and Blowers
- 5.4.3 Compressors
- 5.4.4 Conveyors and Material Handling
- 5.4.5 Elevators and Cranes
- 5.4.6 HVAC Equipment
- 5.4.7 Other Applications
- 5.5 By End-User Industry
- 5.5.1 Manufacturing
- 5.5.2 Oil and Gas and Chemicals
- 5.5.3 Power Generation and Utilities
- 5.5.4 Water and Wastewater
- 5.5.5 Mining and Metals
- 5.5.6 Commercial and Buildings
- 5.5.7 Transportation
- 5.5.8 Residential
- 5.5.9 Other End-User Industry
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.1.4 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 Israel
- 5.6.5.5 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Egypt
- 5.6.6.3 Nigeria
- 5.6.6.4 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 ABB Ltd.
- 6.4.2 Siemens AG
- 6.4.3 WEG S.A.
- 6.4.4 Nidec Corporation
- 6.4.5 Wolong Electric Group Co., Ltd.
- 6.4.6 Regal Rexnord Corporation
- 6.4.7 TECO Electric and Machinery Co., Ltd.
- 6.4.8 Toshiba Corporation
- 6.4.9 Toshiba Mitsubishi-Electric Industrial Systems Corporation
- 6.4.10 Getriebebau NORD GmbH & Co. KG
- 6.4.11 SEW-EURODRIVE GmbH & Co KG
- 6.4.12 CG Power and Industrial Solutions Limited
- 6.4.13 Kirloskar Electric Company Limited
- 6.4.14 Rockwell Automation Inc.
- 6.4.15 Hitachi, Ltd.
- 6.4.16 Yaskawa Electric Corporation
- 6.4.17 Oriental Motor Co., Ltd.
- 6.4.18 Bonfiglioli Riduttori S.p.A.
- 6.4.19 Sumitomo Heavy Industries, Ltd.
- 6.4.20 Brook Crompton UK Limited
- 6.4.21 Hyundai Electric and Energy Systems Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


