

|
시장보고서
상품코드
2124122
플로트 유리 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Float Glass - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 플로트 유리 시장 규모는 7,686만 톤으로 추정되고 있어 2025년 7,427만 톤으로부터 확대해, 2031년에는 9,118만 톤에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 3.48%를 나타낼 전망입니다.
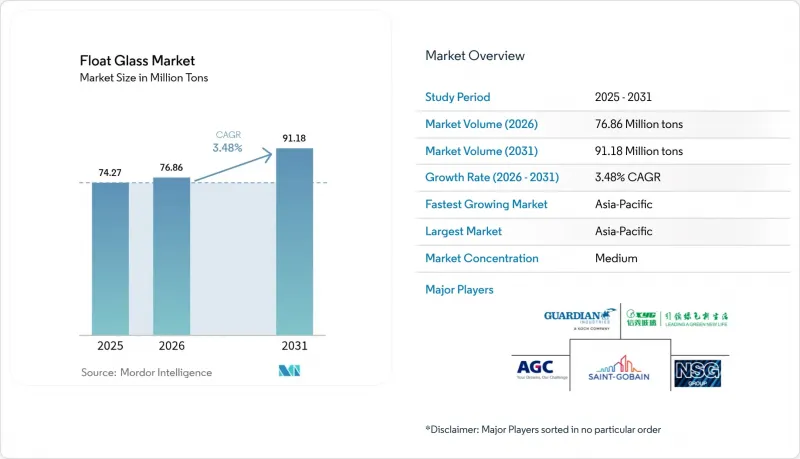
본 보고서는 제품 유형(투명, 착색, 무늬가 있는 와이어가 포함된, 초투명/저철분), 용도(건축 및 건설, 자동차, 태양광 유리, 기타 용도) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 수량(톤) 단위로 제시됩니다.
세계 플로트 유리 시장 동향 및 인사이트
신흥 경제국의 건설 부문 확대
교통, 주택, 산업 회랑에 대한 공공 부문의 과감한 지출이 남아시아 및 동남아시아 전역에서 건축용 유리의 지속적인 구매를 뒷받침하고 있습니다. 인도의 건설 파이프라인은 해당 부문의 연간 영업 수익의 3.5배에 달할 전망입니다. 태국의 동부 경제 회랑에서는 인력 부족으로 인해 프로젝트 진행이 둔화되고 있음에도 불구하고, 여전히 대량의 플로트 유리가 소비되고 있습니다. 이 지역의 플로트 유리 생산 라인 가동률은 이미 80% 미만으로 떨어졌기 때문에 이러한 수요 거점 근처에 위치한 제조업체들은 새로운 투자를 하지 않고도 신속하게 출하량을 확대할 수 있습니다. 그 결과, 플로트 유리 시장은 성숙한 서유럽 국가들의 소비 정체를 상쇄하기 위해 급성장하는 신흥 경제국에 의존하게 될 것입니다.
자동차 경량화로 인해 차량 1대당 유리 사용 면적이 증가
전동화 의무화로 인해 중량은 자동차 제조업체에게 가장 중요한 KPI(핵심 성과 지표)가 되었지만, 한편으로는 첨단 운전자 보조 시스템(ADAS), 파노라믹 루프, 몰입형 인포테인먼트 스크린으로 인해 차량당 유리 표면적은 확대되고 있습니다. 이러한 역설이 플로트 유리 시장의 구조적 상승을 뒷받침하고 있으며, OEM 각사는 안테나, 히터, 헤드업 디스플레이(HUD) 코팅을 통합한 더 얇고 더 큰 접합 유리나 강화 유리를 지정하고 있기 때문입니다. 푸야오 글래스가 전동화 차량 플랫폼 전용 신규 플로트 유리 생산 라인에 58억 위안(8억 400만 달러)을 투자하기로 결정한 것은 이 시장의 기회 규모를 여실히 보여줍니다. 그 결과 요구되는 광학적 투명성과 전자파 투과성은 프리미엄 가격 책정을 뒷받침하며, 기술력을 갖춘 공급업체의 경우 판매량 증가가 매출 및 이익률 확대로 직결될 것임을 보장합니다.
안전 유리의 폴리머 및 폴리카보네이트 대체재
자동차 및 건축 기준에서는 접합 유리와 동등한 내충격성을 유지하면서 무게를 40-50% 경감할 수 있는 폴리카보네이트 소재 솔루션이 인정되고 있습니다. 따라서 경량화를 중시하는 각 OEM 업체들은 폴리머 재질의 루프와 리어 윈도우를 도입하려고 시도하고 있지만, 내스크래치성, 자외선 안정성, 광학적 왜곡과 같은 과제로 인해 그 사용은 여전히 틈새 용도로 제한되어 있습니다. 이에 반해, 유리 제조업체들은 이스트먼(Eastman)사의 유럽 내 생산 능력 확대가 보여주듯이, 첨단 PVB 중간막을 사용한 더 얇고 가벼운 접합 유리를 제안하고 있습니다. 이러한 소재 경쟁은 플로트 유리 시장의 연평균 성장률(CAGR)을 억제하는 한편, 혁신을 촉진하고 제품의 적용 범위를 넓히며 시장 진입 장벽을 높이고 있습니다.
부문 분석
2025년 시점에서 클리어 시트는 플로트 유리 시장 점유율의 62.70%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 3.79%라는 가장 높은 성장률을 기록할 전망입니다. 이러한 압도적인 우위는 타의 추종을 불허하는 범용성을 반영합니다. 파사드용 유리, 자동차 앞유리, 저철분 태양광 커버 등 모두 착색이나 무늬가 들어간 제품으로는 달성할 수 없는 수준의 투명성이 요구되기 때문입니다. 각 제조업체는 기포 함유량과 잔류 철분을 억제하는 정제 기술 및 용융 균질화 기술에 연구개발 예산을 투입하고 있으며, 이를 통해 상품화(commoditization)로 인한 역풍을 상쇄할 수 있는 이익률을 확보하고 있습니다. 착색 유리나 무늬가 들어간 유리는 디자인 주도형 틈새 시장으로 존속하고 있지만, 그 보급은 구조적인 기술 혁신이라기보다는 건축 동향의 주기적인 변동에 좌우되고 있습니다.
초투명 저철분 등급은 태양광 발전 붐에 따른 경제성과 고급스러운 외관의 미관에 힘입어 프리미엄 시장의 정점에 위치하고 있습니다. NSG사의 ‘Pilkington Mirai(TM)’와 Xinyi사의 2.0mm 유리 제품 라인은 탄소 배출량 감축과 초박형화에 모두 중점을 두고 있음을 여실히 보여줍니다. N형 태양전지 모듈이 생산 라인을 잇달아 통과함에 따라 유리의 불량률은 상승하고 있지만, 역설적으로 설치된 1기가와트당 투명 유리의 사용량은 증가하고 있습니다. 따라서 통합된 모래 채석장과 실시간 불순물 스캐너는 플로트 유리 시장 전체에서 중요한 경쟁 우위를 차지하고 있습니다.
지역별 분석
플로트 유리 시장은 아시아태평양이 주도하고 있으며, 2025년에는 세계 생산량의 62.65%를 공급하고, 2031년까지 연평균 성장률(CAGR) 3.92%로 성장할 전망입니다. 중국은 메가 스케일의 가마 집적지를 기반으로 시장을 뒷받침하고 있는 반면, 인도는 전례 없는 1조 5,000억 달러 규모의 건설 붐을 타고 주거용 고층 건물 및 물류 단지를 위한 대형 유리를 대량으로 흡수하고 있습니다. 태국의 ‘동부 경제 회랑’ 주변에 대한 인프라 투자는 주택 시장의 둔화에 따른 지역적 수요 감소를 완화하고 있습니다. 그러나 아시아의 수출업체들은 운임 급등과 임박한 CBAM(탄소국경조정조치) 과세에 대응해야 하는 상황에 직면해 있으며, 출하 톤당 CO2 배출량을 줄이기 위해 하이브리드 용광로 및 옥상 태양광 발전에 대한 시범적인 투자가 진행되고 있습니다.
역사적으로 플로트 유리의 혁신 발상지였던 유럽은 이제 저탄소 제조의 시금석이 되고 있습니다. 상고반의 ‘ORAE’ 시리즈는 높은 재활용 소재 함유율과 ‘크래들 투 크래들(C2C)’ 인증을 모두 갖추고 있는 반면, AGC 인터파네는 독일과 오스트리아에서의 설비 갱신을 통해 주택 착공 건수의 부진에도 불구하고 생산 라인의 효율을 높이고 있습니다.
북미에서는 니어쇼어링 동향과 청정 에너지 인센티브를 활용하여, 푸야오(Fuyao)사가 일리노이주의 플로트 유리 공장에 4억 달러를 투자해 중서부에 위치한 전기차(EV) 공장에 대한 적시(JIT) 공급을 확보하고 있습니다. ‘인플레이션 억제법’에 따른 제조 세액 공제와 맞물려, 이러한 움직임으로 인해 수입 의존에서 국내에서 용해된 시트 유리로의 전환이 진행되어 리드타임과 탄소 발자국 감축으로 이어지고 있습니다. 남미, 중동 및 아프리카에서는 경기장 건설, 해수 담수화 프로젝트, 스마트 시티 구축을 통해 생산량이 점차 증가하고 있지만, 현지 생산 능력이 제한적이어서 1인당 소비량은 성숙 시장의 기준에 미치지 못하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, float glass market size in 2026 is estimated at 76.86 million tons, growing from 2025 value of 74.27 million tons with 2031 projections showing 91.18 million tons, growing at 3.48% CAGR over 2026-2031.
This report is Segmented by Product Type (Clear, Tinted, Patterned, Wired, and Extra Clear/Low Ferrous), Application (Building and Construction, Automotive, Solar Glass, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Float Glass Market Trends and Insights
Construction-Sector Expansion in Emerging Economies
Decisive public-sector outlays on transport, housing, and industrial corridors are fueling sustained purchases of architectural glass across South and Southeast Asia. India's construction pipeline equals 3.5 times the sector's annual operating revenue. Thailand's Eastern Economic Corridor continues to absorb large sheet volumes even as labor shortages slow project execution. With regional float lines already running at utilization rates below 80%, producers situated near these demand hubs can ramp shipments swiftly without green-field investments. As a result, the float glass market will rely on fast-growing emerging economies to offset plateauing consumption in mature Western countries.
Automotive Lightweighting Raises Glazing M2 Per Vehicle
Electrification mandates have made weight a premium KPI for automakers, yet advanced driver-assistance systems, panoramic roofs, and immersive infotainment screens are simultaneously expanding the glass surface area per car. This paradox underpins a structural upswing for the float glass market, as OEMs specify thinner yet larger laminated or tempered panes that integrate antennas, heaters, and head-up-display coatings. Fuyao's decision to inject CNY 5.8 billion (USD 804 million) into new float lines dedicated to electrified vehicle platforms illustrates the scale of the opportunity. The resulting requirement for optical clarity and electromagnetic transparency supports premium pricing, ensuring that volume growth feeds directly into revenue and margin expansion for technologically capable suppliers.
Polymer and Polycarbonate Substitutes in Safety Glazing
Automotive and architectural standards permit polycarbonate solutions that weigh 40-50% less than laminated glass while matching impact resistance. Weight-sensitive OEMs therefore experiment with polymer roofs and rear windows; however, scratch performance, UV stability, and optical distortion issues still confine usage to niche placements. Glass makers answer with thinner, lighter laminates using advanced PVB interlayers, as evidenced by Eastman's European capacity expansion. The resulting material joust moderates the float glass market CAGR but also catalyzes innovation, widening the product envelope and raising entry barriers.
Other drivers and restraints analyzed in the detailed report include:
- Utility-Scale Solar Build-Outs Boost Demand for Low-Iron Float Glass
- BIPV Facade Regulations Spur Ultra-Clear Low-Iron Substrates
- EU Carbon Border Adjustment Mechanism Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Clear sheet controlled 62.70% of the float glass market share in 2025 and will register the highest 3.79% CAGR through 2031. This dominance reflects unrivaled versatility: facade glazing, automotive windscreens, and low-iron solar covers all demand transparency levels unattainable by tinted or patterned variants. Manufacturers channel research and development budgets into purification and melt-homogeneity technologies that suppress bubble content and iron residue, securing margins that offset commodity headwinds. Tinted and patterned sheets persist as design-driven niches, yet their uptake follows cyclical architectural trends rather than structural technology shifts.
Extra-clear low-ferrous grades sit at the premium apex, powered by solar boom economics and luxury facade aesthetics. NSG's Pilkington Mirai(TM) and Xinyi's 2.0 mm glass lines exemplify the emphasis on both embodied-carbon cuts and extreme thinness. As N-type solar modules cascade through production lines, sheet rejection rates rise, paradoxically lifting clear-glass tonnage per installed gigawatt. Integrated sand quarries and real-time impurity scanners thus become critical competitive assets across the float glass market.
Complete Report Scope:
- By Product Type
- Clear
- Tinted
- Patterned
- Wired
- Extra Clear/Low Ferrous Floated Glass
- By Application
- Building and Construction
- Automotive
- Solar Glass
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Vietnam
- Thailand
- Indonesia
- Malaysia
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Nordic Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- Nigeria
- Qatar
- United Arab Emirates
- Egypt
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific dominates the float glass market, supplying 62.65% of global output in 2025 and advancing at a 3.92% CAGR to 2031. China anchors the base with mega-scale kiln clusters, while India rides an unprecedented USD 1.5 trillion construction upcycle that absorbs large sheets for residential towers and logistics parks. Thailand's infrastructure spend around the Eastern Economic Corridor cushions regional demand dips tied to residential slowdowns. Yet Asian exporters must navigate rising freight charges and looming CBAM levies, prompting pilot investments in hybrid furnaces and rooftop solar to reduce shipped-ton CO2.
Europe, historically the cradle of float innovation, is now the crucible for low-carbon manufacturing. Saint-Gobain's ORAE series combines high recycled content with cradle-to-cradle certification, while AGC Interpane's upgrades in Germany and Austria elevate line efficiencies despite weak housing starts.
North America capitalizes on nearshoring dynamics and clean-energy incentives. Fuyao's USD 400 million boost to its Illinois float facility ensures just-in-time supply for Midwest EV plants. Combined with the Inflation Reduction Act's manufacturing tax credits, these moves shift import reliance toward domestically melted sheets, narrowing latency and carbon footprints. South America and the Middle East and Africa deliver incremental tonnage via stadium builds, desalination projects, and smart-city launches, but limited local capacity keeps per-capita consumption below mature-market norms.
- AGC Inc.
- BG
- CARDINAL GLASS INDUSTRIES, INC
- China Glass Holding
- China Luoyang Float Glass Group Co., Ltd.
- Flat Glass Group Co., Ltd
- Fuyao Group
- Guardian Industries Holdings
- Kibing Group
- Nippon Sheet Glass Co., Ltd
- PRESS GLASS Holding SA
- PT Mulia Industrindo Tbk
- Saint-Gobain
- SCHOTT
- Sisecam
- Taiwan Glass Ind. Corp.
- Vitro
- Xinyi Glass Holdings Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Construction Sector Expansion in Emerging Economies
- 4.2.2 Automotive Lightweighting Raises Glazing M2 Per Vehicle
- 4.2.3 Utility-Scale Solar Buildouts Boost Demand for Low-Iron Float Glass
- 4.2.4 Urban Regeneration Mandates Energy-Efficient Facades
- 4.2.5 BIPV Facade Regulations Spur Ultra-Clear Low-Iron Substrates
- 4.3 Market Restraints
- 4.3.1 Volatile Soda-Ash and Natural-Gas Prices
- 4.3.2 Polymer and Polycarbonate Substitutes in Safety Glazing
- 4.3.3 EU Carbon Border Adjustment Mechanism Compliance Costs (under-radar)
- 4.4 Value Chain Analysis
- 4.5 Raw Material Analysis
- 4.5.1 Sand
- 4.5.2 Limestone
- 4.5.3 Soda Ash
- 4.5.4 Dolomite
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Degree of Competition
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Product Type
- 5.1.1 Clear
- 5.1.2 Tinted
- 5.1.3 Patterned
- 5.1.4 Wired
- 5.1.5 Extra Clear/Low Ferrous Floated Glass
- 5.2 By Application
- 5.2.1 Building and Construction
- 5.2.2 Automotive
- 5.2.3 Solar Glass
- 5.2.4 Other Applications
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Vietnam
- 5.3.1.6 Thailand
- 5.3.1.7 Indonesia
- 5.3.1.8 Malaysia
- 5.3.1.9 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Nordic Countries
- 5.3.3.8 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 Nigeria
- 5.3.5.3 Qatar
- 5.3.5.4 United Arab Emirates
- 5.3.5.5 Egypt
- 5.3.5.6 South Africa
- 5.3.5.7 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 AGC Inc.
- 6.4.2 BG
- 6.4.3 CARDINAL GLASS INDUSTRIES, INC
- 6.4.4 China Glass Holding
- 6.4.5 China Luoyang Float Glass Group Co., Ltd.
- 6.4.6 Flat Glass Group Co., Ltd
- 6.4.7 Fuyao Group
- 6.4.8 Guardian Industries Holdings
- 6.4.9 Kibing Group
- 6.4.10 Nippon Sheet Glass Co., Ltd
- 6.4.11 PRESS GLASS Holding SA
- 6.4.12 PT Mulia Industrindo Tbk
- 6.4.13 Saint-Gobain
- 6.4.14 SCHOTT
- 6.4.15 Sisecam
- 6.4.16 Taiwan Glass Ind. Corp.
- 6.4.17 Vitro
- 6.4.18 Xinyi Glass Holdings Limited
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


