

|
시장보고서
상품코드
2124336
클라우드 공급망 관리 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cloud Supply Chain Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
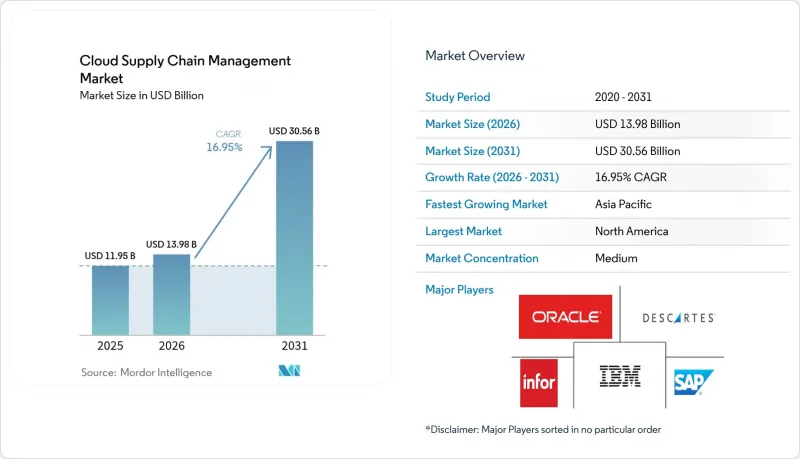
에 의하면, 클라우드 공급망 관리 시장 규모는 2025년 119억 5,000만 달러로 평가되었고, 2026년에는 139억 8,000만 달러로 추정되고, 2026-2031년 CAGR 16.95%로 성장을 지속할 전망이며, 2031년에는 305억 6,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 솔루션별( 수요 계획 및 예측 등), 도입 형태별(하이브리드 클라우드, 퍼블릭 클라우드, 프라이빗 클라우드), 기업 규모별(대기업, 중소기업), 최종 사용자 산업별(소매, 식품 및 음료 등), 지역별(북미, 남미 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 클라우드 공급망 관리 시장 동향 및 인사이트
수요 계획 분야에서 클라우드 기반 솔루션의 급속한 확산
스프레드시트에서 클라우드 네이티브 예측 도구로 전환한 조직에서는 POS 데이터, 기상 API, 소셜 미디어의 감정 분석 정보 등을 활용하여 수요 신호를 1시간마다 업데이트할 수 있게 되었습니다. 생성형 AI의 등장으로 기획자는 자연어로 예측을 분석하고 판촉 효과 시뮬레이션을 수행할 수 있게 되었습니다. 정확도가 약간만 향상되어도 안전 재고를 두 자릿수 비율로 줄일 수 있어 운전 자본을 확보할 수 있습니다. 소매 및 소비재 업계의 선도 기업들이 선구적으로 도입을 추진해 왔으나, 클라우드 데이터 레이크가 머신러닝 및 훈련을 위한 안전하고 테넌트별로 격리된 모델을 지원함에 따라 그 도입 범위는 점차 확대되고 있습니다.
전자상거래의 확장이 요구하는 민첩한 공급망
2024년까지 전자상거래 침투율이 소매 매출의 21%를 나타낼 것으로 예측되는 가운데, 각 브랜드는 당일 배송 약속을 이행하기 위해 분산된 재고를 통합적으로 관리해야 합니다. 클라우드 기반 공급망 관리 플랫폼은 주문을 가장 가까운 거점으로 배정함으로써 분할 배송을 최소화합니다. 사전 구축된 커넥터가 풀필먼트 센터, 택배 업체, 통관 업체를 연결하여 수십 개의 관할 구역에 걸친 배송비 계산 및 반품 처리를 자동화합니다. 이 기능은 50달러 미만의 장바구니를 취급하는 크로스보더 판매업체에게 매우 중요합니다.
보안 및 데이터 개인정보 보호에 대한 우려 증가
다중 테넌트형 아키텍처에서는 기밀성이 높은 가격, 예측, 출하 데이터가 한곳에 집약됩니다. 2024년에 발생한 한 물류 소프트웨어 제공업체의 정보 유출 사건에서는 4만 개 고객사의 화물 목록이 유출되었습니다. 이로 인해 암호화, 접근 제어 및 데이터 소재지에 관한 규정 준수 감시가 강화되고 있습니다. 유럽연합(EU)의 GDPR(EU 개인정보보호규정)과 중국의 ‘개인정보 보호법’으로 인해 국경을 넘는 데이터 전송이 복잡해지고 있으며, 일부 기업은 프라이빗 리전이나 고객 관리형 키(CMK)를 채택하고 있습니다. 이러한 추가적인 통제 조치는 공급업체의 비용을 증가시켜 클라우드 기반 공급망 관리 도입을 지연시킬 가능성이 있습니다.
부문 분석
운송 및 물류 관리는 클라우드 공급망 관리 시장에서 가장 큰 점유율을 차지하며, 2025년에는 매출의 27.12%를 차지한 것으로 평가되었습니다. 화주들은 업무 최적화를 위해 실시간 도착 예정 시간(ETA), 동적 경로 최적화 및 운송업체 성과 대시보드에 의존하고 있습니다. 북미의 전자 기록 장치(ELD) 의무화 및 유럽의 타코그래프 규제로 인해 텔레매틱스 데이터가 제공되며, 예측 ETA의 정확도가 향상되고 있습니다. 디지털 화물 마켓플레이스는 오픈 API를 통해 연동되어 있어, 기획자는 수동으로 입찰할 필요 없이 다양한 운송 수단을 가로질러 운임을 비교 검토할 수 있습니다. 소매업체들이 날씨나 소셜 센티먼트와 같은 외부 변수를 통합하여 과잉 재고를 최소화하기 위해 노력함에 따라, 수요 계획 및 수요 예측의 중요성이 커지고 있습니다. 재고 및 창고 관리에는 주기적 재고 조사(Cycle Count)를 위한 컴퓨터 비전이 통합되어, 회전율이 높은 물류 센터(DC)의 인건비가 절감되고 있습니다. 제품 수명 주기 관리(PLM) 모듈은 프로세스 산업으로도 확대되어, 레시피 개정과 규정 준수 기록을 연계하고 있습니다. 판매·운영 계획(S&OP)에는 재무 연계 기능이 통합되어, 판매 수량과 수익 예측을 단일 대시보드에서 대조할 수 있게 되었습니다. 조달 모듈에는 재무 건전성, ESG 평가, 지정학적 리스크를 종합하여 산출된 공급업체 리스크 점수가 포함되어 있습니다. 수주 관리 엔진은 충전률, 이익률, 납기 보장 로직을 활용하여 멀티 채널에서의 주문 이행을 조정합니다. 제품 마스터 데이터 관리에서는 블록체인을 활용하여 변조가 불가능한 원산지 추적 체인을 구축하는 움직임이 점점 더 확산되고 있습니다.
연평균 성장률(CAGR) 21.25%로 확대되고 있는 ‘디지털 트윈을 활용한 계획’은 가장 성장세가 두드러지는 솔루션 하위 부문입니다. 제약, 반도체, 중공업 기업들은 다단계 자재명세서(BOM) 전반에 걸친 혼란을 시뮬레이션하는 네트워크 그래프를 구축하고 있습니다. 기획 담당자는 재고를 확보하기 전에 대체 조달이나 완충 재고의 이동을 가상으로 테스트할 수 있습니다. 그래프 데이터베이스는 단일 고장 지점이 되는 공급업체를 식별하고, 클라우드 컴퓨팅은 시간당 수천 건의 몬테카를로 시나리오를 실행합니다. 이 기능은 2024년 부품 부족으로 전 세계 조립 라인이 중단되면서 기업들이 시나리오 주도형 운영 모델을 채택하게 된 계기로 주목받기 시작했습니다.
2025년, 퍼블릭 클라우드는 클라우드 공급망 관리 시장의 60.58%를 차지했습니다. 기업들은 벤더 관리형 인프라와 신속한 도입을 중시하며, 6-12개월이 소요되는 온프레미스 프로젝트를 피하고 있습니다. 30개국 이상에 걸쳐 있는 지역 데이터센터는 데이터 상주 요건을 충족하고, 운영 워크플로우에서 10밀리초 미만의 지연 시간을 보장합니다. 프라이빗 클라우드는 여전히 국방 및 에너지 관련 기업들 사이에서 활용되고 있으며, 기밀 도면이나 지진 데이터를 보호하고 있습니다. 이러한 환경에서는 하이퍼바이저와 OpenStack 레이어를 활용하여 기업 방화벽 내에서 탄력적인 확장을 시뮬레이션하고 있습니다.
연평균 성장률(CAGR) 19.05%가 예상되는 하이브리드 클라우드는 거버넌스와 민첩성 간의 균형을 맞추고 있습니다. 제약 기업은 임상시험 프로토콜 및 환자 데이터를 GCP(적정 임상시험 실시 기준)에 따라 검증된 프라이빗 노드에 저장하는 한편, 분기별 S&OP 사이클에서는 분석 워크로드를 퍼블릭 테넌트로 오프로드하고 있습니다. AWS Outposts 및 Azure Stack과 같은 서비스는 온프레미스 관리형 서비스를 확장하여 일관된 도구 환경을 구현합니다. 이 모델에서는 이벤트 스트림 통합을 활용하여 데이터가 오래되지 않도록 마스터 데이터를 동기화합니다. ISO 27001 및 SOC 2에 기반한 인증된 관리 체제는 감사 대응의 기반이 되며, 도입 선택에 영향을 미칩니다.
지역별 분석
북미는 2025년 매출의 34.41%를 차지했습니다. 미국 세관·국경보호청(CBP)의 ‘Automated Commercial Environment(ACE)’ API는 통관 신고서 작성을 자동화하여 수입업체의 통관 대행 비용을 절감합니다. 하이퍼스케일러에 의한 조기 인프라 구축을 통해, 시간적 제약이 엄격한 컨트롤 타워 및 화물 가시화 대시보드에 대한 저지연 접근이 보장되고 있습니다. 캐나다의 ‘캐나다인을 위한 안전한 식품 규정(Safe Food for Canadians Regulations)’에 따라 농식품 수출업체들은 ‘농장에서 식탁까지’의 추적 가능성 확립을 요구받고 있으며, 이는 클라우드 투자를 촉진하고 있습니다. 멕시코의 니어쇼어링 동향에 따라, 전자기기 및 자동차 조립 제조업체들은 태평양 항로의 운송 위험을 회피하기 위해 공급업체와의 협력을 디지털화하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 18.05%로, 이 지역 내에서 가장 빠른 성장이 예상됩니다. 중국, 인도, 베트남의 수탁 제조업체들은 세계 브랜드가 설정한 적시 생산(JIT) 마일스톤을 달성하기 위해 2차 및 3차 파트너의 디지털화를 추진하고 있습니다. 중국의 ‘일대일로’ 철도 회랑으로 인해 복합 운송 경로 최적화의 필요성이 높아지고 있습니다. 인도의 완전 디지털화된 상품 및 서비스세(GST) 전자 청구서는 세무상 채무를 실시간으로 대조하는 클라우드 시스템과 연동되어 있습니다. 일본에서는 운전자의 고령화를 배경으로 AI를 활용한 경로 통합이 도입되고 있는 반면, 호주의 자원 수출업체들은 선박 예약을 신속하게 처리하기 위해 수출 서류의 자동화를 추진하고 있습니다.
유럽에서는 GDPR(EU 개인정보보호규정)(일반 데이터 보호 규정) 및 ‘기업 지속가능성 보고에 관한 지침’에 따라 공급업체에 대한 RFP(제안 요청서)에 규정 준수 기능이 포함되어 있어 도입이 크게 진전되고 있습니다. 독일 자동차 업계에서는 제약 조건에 기반한 계획 기법을 채택하여 다단계 생산 능력을 관리하고 있습니다. 영국에서는 브렉시트 이후의 규제로 인해 자동 관세 분류 도입이 가속화되고 있습니다. 프랑스의 명품 부문에서는 짧은 시즌 주기에 대응하여 수요 예측을 활용해 할인 폭을 대폭 줄이고 있습니다. 러시아의 데이터 현지화법은 여전히 장벽으로 작용하고 있어, 기업들은 국내 클라우드 서비스로 전환할 수밖에 없으며, 그 결과 세계 파트너들에게는 지연이 발생하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the cloud supply chain management market size is expected to grow from USD 11.95 billion in 2025 to USD 13.98 billion in 2026 and is forecast to reach USD 30.56 billion by 2031 at 16.95% CAGR over 2026-2031.
This report is Segmented by Solution (Demand Planning and Forecasting, and More), Deployment Type (Hybrid Cloud, Public Cloud, and Private Cloud), Organization Size (Large Enterprises, and Small and Medium Enterprises), End-User Industry (Retail, Food and Beverage, and More), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Cloud Supply Chain Management Market Trends and Insights
Rapid Adoption of Cloud-Based Solutions for Demand Planning
Organizations replacing spreadsheets with cloud-native forecasting gain hourly demand-signal refreshes, fed by point-of-sale feeds, weather APIs, and social media sentiment. Generative AI now lets planners interrogate forecasts in natural language and simulate promotional lifts. Even minor accuracy gains cut safety stock by double-digit percentages, releasing working capital. Retail and consumer-goods leaders paved the way, but adoption is broadening as cloud data lakes support a secure, tenant-isolated model for machine learning and training.
Expansion of E Commerce Requiring Agile Supply Networks
With e-commerce penetration expected to reach 21% of retail sales by 2024, brands must orchestrate distributed inventory to meet same-day commitments. Cloud supply chain management market platforms route orders to the closest node, minimizing split shipments. Pre-built connectors link fulfillment centers, parcel carriers, and customs brokers, automating landed-cost calculations and returns processing across dozens of jurisdictions. The capability is critical for cross-border sellers managing baskets under USD 50.
Heightened Security and Data Privacy Concerns
Multi-tenant architectures concentrate sensitive pricing, forecast, and shipment data. A 2024 breach at a logistics software provider exposed manifests for 40,000 customers, elevating scrutiny on encryption, access controls, and data-residency compliance. The European Union's GDPR and China's Personal Information Protection Law complicate cross-border transfers, prompting some firms to opt for private regions or customer-managed keys. Added controls increase vendor costs and can slow the deployment of cloud supply chain management.
Other drivers and restraints analyzed in the detailed report include:
- Cost Efficiency and Scalability Driving Migration from On-Premise SCM
- Integration of Digital Twins for Real-Time Supply Chain Simulation
- Complex Legacy Systems Hindering Cloud Migration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Transportation and Logistics Management contributed the largest slice of the cloud supply chain management market, holding 27.12% of the revenue in 2025. Shippers rely on real-time estimated arrival times, dynamic route optimization, and carrier performance dashboards to optimize their operations. Electronic logging device mandates in North America and tachograph rules in Europe feed telematics data that elevates predictive ETAs. Digital freight marketplaces interface through open APIs, letting planners benchmark rates across modes without manual tenders. Demand Planning and forecasting are on the rise as retailers integrate external variables, such as weather and social sentiment, to minimize excess stock. Inventory and Warehouse Management now embeds computer vision for cycle counting, reducing labor in high-velocity DCs. Product Lifecycle Management (PLM) modules have expanded into process industries, linking recipe revisions to compliance records. Sales and Operations Planning integrates finance links, allowing volume and revenue forecasts to be reconciled in a single cockpit. Procurement modules inject supplier risk scores that mix financial health, ESG ratings, and geopolitical exposure. Order Management engines orchestrate multichannel fulfillment using fill-rate, margin, and delivery-promise logic. Product Master Data Management increasingly leverages blockchain to build immutable provenance chains.
Digital Twin Enabled Planning, advancing at a 21.25% CAGR, is the fastest-growing solution subsegment. Pharmaceutical, semiconductor, and heavy-industrial firms construct network graphs that simulate disruptions across multi-tier bills of material. Planners can test alternate sourcing or buffer stock moves virtually before committing inventory. Graph databases spotlight single-point-of-failure suppliers, while cloud compute executes thousands of Monte Carlo scenarios hourly. The capability gained prominence after 2024 component shortages halted assembly lines worldwide, prompting firms to adopt scenario-driven operating models.
Public Cloud held 60.58% of the cloud supply chain management market in 2025. Organizations prize the vendor-managed infrastructure and speed of activation, avoiding 6-12 month on-premise projects. Regional data centers spread across more than 30 countries ensure data residency and sub-10 ms latency for operational workflows. Private Cloud persists among defense and energy firms, protecting classified diagrams or seismic data. These environments utilize hypervisor or OpenStack layers to simulate elastic scaling within corporate firewalls.
Hybrid Cloud, projected to grow 19.05% CAGR, balances governance and agility. Pharmaceutical companies store clinical trial protocols and patient data on private nodes validated under Good Clinical Practice, while offloading analytics workloads to public tenants during quarterly S&OP cycles. Offerings such as AWS Outposts and Azure Stack extend managed services on-premise, enabling consistent tooling. The model depends on event-stream integration to synchronize master data without stale reads. Certified controls under ISO 27001 and SOC 2 underpin audit readiness and influence deployment choices.
Complete Report Scope:
- By Solution
- Demand Planning and Forecasting
- Inventory and Warehouse Management
- Product Lifecycle Management
- Transportation and Logistics Management
- Sales and Operations Planning
- Procurement and Sourcing
- Order Management
- Product Master Data Management
- By Deployment Type
- Hybrid Cloud
- Public Cloud
- Private Cloud
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises
- By End-User Industry
- Retail
- Food and Beverage
- Manufacturing
- Automotive
- Oil and Gas
- Healthcare
- Consumer Electronics
- Aerospace and Defense
- Pharmaceuticals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America delivered 34.41% of 2025 revenue. U.S. Customs and Border Protection's Automated Commercial Environment APIs automate customs entry creation, lowering brokerage costs for importers. Early hyperscaler buildouts ensure low-latency access for time-sensitive control towers and freight visibility dashboards. Canada's Safe Food for Canadians Regulations push agri-food exporters to establish farm-to-fork traceability, spurring cloud investments. Mexico's near-shoring trend has electronics and auto assemblers digitizing supplier collaboration to bypass Pacific shipping risks.
The Asia Pacific is poised for the fastest regional growth, with an 18.05% CAGR. Contract manufacturers in China, India, and Vietnam digitize tier-2 and tier-3 partners to meet just-in-time milestones set by global brands. China's Belt and Road rail corridors heighten the need for multi-modal route optimization. India's fully digital Goods and Services Tax e-invoicing feeds cloud systems that reconcile tax liabilities in real time. Japan's aging driver population fuels the adoption of AI-powered route consolidation, while Australia's commodity exporters automate export documentation to speed vessel bookings.
Europe maintains a significant uptake, owing to the GDPR and the Corporate Sustainability Reporting Directive, which embeds compliance functionality into vendor RFPs. Germany's automotive sector employs constraint-based planning to manage multi-tier capacity. The United Kingdom's post-Brexit rules accelerate the adoption of automated tariff classification. France's luxury segment relies on short seasonal calendars and uses demand sensing to slash markdowns. Russia's data-localization law remains a barrier, steering companies to domestic cloud alternatives that add latency for global partners.
- SAP SE
- Oracle Corporation
- Infor Inc.
- The Descartes Systems Group Inc.
- International Business Machines Corporation
- Blue Yonder Group Inc.
- Manhattan Associates Inc.
- Logility Inc.
- Kinaxis Inc.
- Korber Supply Chain Software GmbH
- CloudLogix Inc.
- Tecsys Inc.
- E2open Parent Holdings Inc.
- One Network Enterprises Inc.
- MercuryGate International Inc.
- Freightos Limited
- Project44 Holdings Inc.
- Llamasoft Inc. (Coupa Software Inc.)
- o9 Solutions Inc.
- Elementum SCM Inc.
- ClearMetal Inc.
- Verusen Inc.
- Cognizant Technology Solutions Corporation
- Amazon Web Services Inc. (AWS Supply Chain)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Adoption of Cloud Based Solutions for Demand Planning
- 4.2.2 Expansion of E Commerce Requiring Agile Supply Networks
- 4.2.3 Cost Efficiency and Scalability Driving Migration from On Premise SCM
- 4.2.4 Integration of Digital Twins for Real Time Supply Chain Simulation
- 4.2.5 Rising Carbon Accounting Mandates Promoting Cloud Visibility Platforms
- 4.2.6 Vendor Transition to Composable Microservices Accelerating Upgrades
- 4.3 Market Restraints
- 4.3.1 Heightened Security and Data Privacy Concerns
- 4.3.2 Complex Legacy Systems Hindering Cloud Migration
- 4.3.3 Shortage of Cloud Native Supply Chain Talent
- 4.3.4 Increasing Sovereign Cloud Requirements Fragmenting Deployments
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Technological Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Intensity of Competitive Rivalry
- 4.8.5 Threat of Substitutes
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution
- 5.1.1 Demand Planning and Forecasting
- 5.1.2 Inventory and Warehouse Management
- 5.1.3 Product Lifecycle Management
- 5.1.4 Transportation and Logistics Management
- 5.1.5 Sales and Operations Planning
- 5.1.6 Procurement and Sourcing
- 5.1.7 Order Management
- 5.1.8 Product Master Data Management
- 5.2 By Deployment Type
- 5.2.1 Hybrid Cloud
- 5.2.2 Public Cloud
- 5.2.3 Private Cloud
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises
- 5.4 By End-User Industry
- 5.4.1 Retail
- 5.4.2 Food and Beverage
- 5.4.3 Manufacturing
- 5.4.4 Automotive
- 5.4.5 Oil and Gas
- 5.4.6 Healthcare
- 5.4.7 Consumer Electronics
- 5.4.8 Aerospace and Defense
- 5.4.9 Pharmaceuticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Egypt
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 SAP SE
- 6.4.2 Oracle Corporation
- 6.4.3 Infor Inc.
- 6.4.4 The Descartes Systems Group Inc.
- 6.4.5 International Business Machines Corporation
- 6.4.6 Blue Yonder Group Inc.
- 6.4.7 Manhattan Associates Inc.
- 6.4.8 Logility Inc.
- 6.4.9 Kinaxis Inc.
- 6.4.10 Korber Supply Chain Software GmbH
- 6.4.11 CloudLogix Inc.
- 6.4.12 Tecsys Inc.
- 6.4.13 E2open Parent Holdings Inc.
- 6.4.14 One Network Enterprises Inc.
- 6.4.15 MercuryGate International Inc.
- 6.4.16 Freightos Limited
- 6.4.17 Project44 Holdings Inc.
- 6.4.18 Llamasoft Inc. (Coupa Software Inc.)
- 6.4.19 o9 Solutions Inc.
- 6.4.20 Elementum SCM Inc.
- 6.4.21 ClearMetal Inc.
- 6.4.22 Verusen Inc.
- 6.4.23 Cognizant Technology Solutions Corporation
- 6.4.24 Amazon Web Services Inc. (AWS Supply Chain)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


