

|
시장보고서
상품코드
2124347
클라우드 엔드포인트 보호 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cloud Endpoint Protection - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
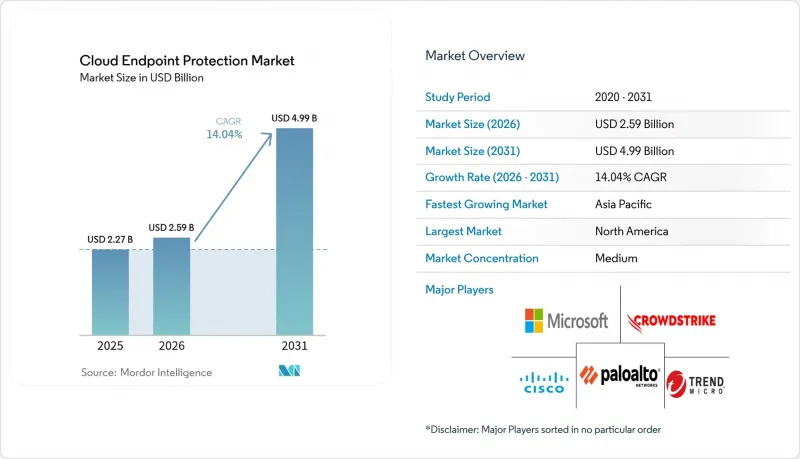
에 의하면, 2026년 클라우드 엔드포인트 보호 시장 규모는 25억 9,000만 달러로 추정되며, 2025년 22억 7,000만 달러에서 성장하여 2031년에는 49억 9,000만 달러에 달할 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 14.04%를 나타낼 것으로 전망됩니다.
본 보고서는 구성 요소별(솔루션, 서비스), 기업 규모별(중소기업, 대기업), 도입 형태별(프라이빗 클라우드, 퍼블릭 클라우드 등), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), 정부 기관, 의료 등), 보안 유형별(안티바이러스/안티멀웨어 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 클라우드 엔드포인트 보호 시장 동향 및 인사이트
원격 근무 및 BYOD의 보급
하이브리드 근무 형태의 정착으로 인해 기존의 네트워크 경계는 사라졌으며, 보안 팀은 기업 LAN에 거의 연결되지 않는 기기를 보호할 수밖에 없게 되었습니다. 마이크로소프트의 ‘Secure Future Initiative’는 하이퍼스케일러가 전체 클라우드 자산에 보호 기능을 통합하여 어디서나 엔드포인트를 보호하는 방법을 제시하고 있습니다. 시스코의 ‘제로 트러스트 아키텍처 가이드’는 BYOD(Bring-Your-Own-Device) 환경에서 기기 수준의 검증을 강조하고 있습니다. 그 결과, 엔드포인트 보호, 신원 관리, 원격 액세스 기능을 통합한 플랫폼으로의 결정적인 전환이 진행되고 있으며, 이에 따라 클라우드 엔드포인트 보호 시장이 확대되고 있습니다.
고도화된 사이버 공격과 데이터 침해의 급증
AI를 활용하는 공격자들은 딥페이크를 이용한 유인, 기존 리소스를 악용하는 페이로드, 다단계 랜섬웨어 등을 사용하고 있습니다. Proofpoint의 조사에 따르면, 2024년 아시아태평양(APAC)에서 딥페이크 사기와 관련된 트래픽이 600% 급증했습니다. 중국과 관련된 공격자들은 패치가 적용되지 않은 엣지 기기를 표적으로 삼은 5년에 걸친 은밀한 캠페인을 지속했습니다. 각 벤더들은 엔드포인트와 클라우드 워크로드 간의 텔레메트리 데이터를 통합하여 트리아지를 자동화하는 AI 기반 XDR로 이에 대응하고 있으며, 이는 클라우드를 통해 제공되는 엔드포인트 보안에 대한 구매자의 선호도를 확고히 하고 있습니다.
사이버 보안 인력 부족이 서비스 비용을 상승시키고 있습니다.
세계적으로 유능한 보안 전문가가 부족하여 사고 대응 및 관리형 서비스의 단가가 상승하고 있으며, 위협의 양이 증가하는 가운데 예산이 압박받고 있습니다. 마이크로소프트는 이러한 긴박한 상황을 완화하기 위해 2025년까지 미국에서 25만 명의 실무자를 양성하겠다고 약속했습니다. 인건비 급등은 지출의 탄력성을 억제하여 클라우드 엔드포인트 보호 시장의 단기적 성장을 둔화시키고 있습니다.
부문 분석
솔루션은 클라우드 엔드포인트 보호 시장에서 가장 큰 점유율을 차지하며 매출의 62.15%를 차지했습니다. 핵심적인 감지, 대응 및 멀웨어 방지 엔진은 여전히 필수적인 구성 요소이지만, 구매자들은 현재 AI를 최우선으로 하는 관점에서 이를 평가했습니다. 엔드포인트 감지 및 대응(EDR) 모듈은 빠르게 진화하고 있으며, CrowdStrike는 분석가의 선별 작업을 가속화하는 워크플로 자동화에 대한 특허를 취득했습니다. 대조적으로, 관리형 서비스는 인력 부족과 연중무휴 24시간 대응을 요구하는 규제 감사로 인해 조직이 어려움을 겪고 있는 상황에서 14.72%라는 가장 높은 연평균 성장률(CAGR)을 기록했습니다.
이 서비스 시장의 급속한 성장은 턴키 방식의 MDR, 통합 및 교육 제공에 의해 뒷받침되고 있습니다. LevelBlue의 MSSP 전환 로드맵은 채널 파트너가 원격 SOC 운영을 통해 지속적인 수익을 창출하는 방법을 보여줍니다. 각 벤더는 정책 조정, 제로 트러스트 로드맵 수립, 규정 준수 보고와 같은 자문 서비스를 묶어 제공함으로써 평생 가치를 극대화하고, 클라우드 엔드포인트 보호 시장에서 서비스를 구조적인 촉진요인으로 확고히 자리매김하고 있습니다.
2025년, 대기업은 클라우드 엔드포인트 보호 시장 점유율의 57.45%를 차지했습니다. 이는 수백만 달러 규모의 보안 예산과 초기 단계의 혁신에 대한 의지에 힘입은 결과입니다. 대기업의 시범 도입은 특히 AI를 활용한 위협 사냥 분야에서 벤더의 제품 로드맵을 형성하는 요인이 되고 있습니다. 한편, 중소기업(SME)은 연평균 성장률(CAGR) 16.65%를 기록하며, SaaS 가격 정책과 SOC 아웃소싱을 통해 고도화된 방어 수단이 널리 보급되고 있음을 입증하고 있습니다. 소닉월(SonicWall)은 과거 ‘대형 은행 전용’으로 여겨졌던 EDR 기능의 중소기업 내 도입이 확대되고 있음을 확인하고 있습니다.
비용의 예측 가능성과 신속한 도입 덕분에 구독 모델은 자금에 제약이 있는 기업에게 매력적인 선택지가 되고 있습니다. 한편, 클라우드 콘솔에 통합된 규정 준수 자동화 기능은 감사에 대한 우려를 완화합니다. 그 결과, 중소기업 부문은 클라우드 엔드포인트 보호 시장 전체 시장 진출 전략을 재구성하고 있으며, 각 벤더들은 사용량에 따른 과금과 엄선된 플레이북을 갖춘 원클릭 패키지 제공에 나서고 있습니다.
지역별 분석
북미는 성숙한 규제 체계와 클라우드 보안에 대한 다년간의 투자 덕분에 2025년 매출의 40.35%를 차지했습니다. 연방 정부의 제로 트러스트 청사진과 대규모 SaaS 도입으로 인해 갱신 주기가 활발하게 유지되고 있습니다. 이 지역의 기업들은 AI 기반 XDR 플랫폼을 조기에 도입하고, 기능 로드맵을 수립하며, 차세대 엔드포인트 제품군에 대한 지출을 정착시키고 있습니다. 벤처 캐피털을 통한 자금 조달과 사이버 보안 스타트업의 집적이 혁신을 더욱 촉진하여, 클라우드 엔드포인트 보호 시장에서 북미의 입지를 강화하고 있습니다.
아시아태평양은 가장 빠르게 성장하는 시장으로, 연평균 성장률(CAGR) 14.88%로 확대되고 있습니다. 이 지역은 마이크로소프트의 22억 달러 규모 말레이시아 AI 허브, 아마존의 127억 달러 규모 인도 거점 확충, 구글의 67억 달러 규모 싱가포르 사업 확장 등 하이퍼스케일러로부터의 자본 유입 혜택을 받고 있습니다. 랜섬웨어와 딥페이크 사기의 급격한 증가로 인해 기업들은 고급 EDR 및 XDR 기능 도입을 피할 수 없게 되었으며, 이로 인해 아시아태평양은 클라우드 엔드포인트 보호 시장의 차세대 성장 동력이 되고 있습니다.
유럽에서는 NIS2 지침에 따른 엄격한 처벌을 배경으로 꾸준한 성장이 예상됩니다. 독일, 영국, 프랑스는 ‘최첨단’ 규정 준수 기준을 충족하기 위해 AI 중심의 엔드포인트 기술 도입을 주도하고 있습니다. 데이터 주권에 대한 우려로 인해 텔레메트리 현지화 및 데이터 거주성 보장을 유지할 수 있는 벤더에 대한 수요가 증가하고 있으며, 이 지역은 클라우드 엔드포인트 보호 시장에서 전략적으로 중요한 위치를 계속 차지하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측(금액 기준)
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, cloud endpoint protection market size in 2026 is estimated at USD 2.59 billion, growing from 2025 value of USD 2.27 billion with 2031 projections showing USD 4.99 billion, growing at 14.04% CAGR over 2026-2031.

This report is Segmented Into by Component (Solutions, Services), Enterprise Size (Small and Medium Enterprises, Large Enterprises), Deployment Mode (Private Cloud, Public Cloud, and More), End-User Industry (BFSI, Government, Healthcare, and More), by Security Type (Antivirus / Anti-Malware and More) and Geography. The Market Forecasts are Provided in Terms of Value (USD)
Global Cloud Endpoint Protection Market Trends and Insights
Proliferation of remote work & BYOD
The normalization of hybrid schedules has erased the traditional network perimeter, forcing security teams to protect devices that rarely touch the corporate LAN. Microsoft's Secure Future Initiative demonstrates how hyperscalers embed protection across cloud assets to secure any endpoint, anywhere . Cisco's Zero Trust Architecture Guide stresses device-level verification in Bring-Your-Own-Device environments. The outcome is a decisive shift toward unified platforms that merge endpoint protection, identity, and remote access functions, thereby enlarging the cloud endpoint protection market.
Surge in sophisticated cyber-attacks & data breaches
AI-enabled adversaries employ deep-fake lures, living-off-the-land payloads, and multistage ransomware. Proofpoint logged a 600% spike in deep-fake scam chatter in APAC during 2024. China-linked actors sustained five years of clandestine campaigns targeting unpatched edge devices. Vendors answer with AI-driven XDR that stitches telemetry across endpoints and cloud workloads to automate triage, cementing buyer preference for cloud-delivered endpoint security.
Cyber-talent shortage inflates service costs
The worldwide shortfall of qualified defenders raises billable rates for incident response and managed services, squeezing budgets even as threat volumes climb. Microsoft pledged to train 250,000 U.S. practitioners by 2025 to alleviate the pinch. Elevated labor pricing curbs spending elasticity, moderating near-term growth within the cloud endpoint protection market.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory mandates for data protection & privacy
- Cost-saving scalability of SaaS-based security models
- Deployment complexity in multi-cloud estates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions generated the largest slice of the cloud endpoint protection market translating into 62.15% revenue share. Core detection, response, and anti-malware engines remain indispensable building blocks, yet buyers now evaluate them through an AI-first lens. Endpoint Detection and Response modules are evolving rapidly, with CrowdStrike patenting workflow automation that speeds analyst triage. Managed services, by contrast, posted the steepest 14.72% CAGR as organizations grapple with talent shortages and regulatory audits that demand 24X7 coverage.
The services boom is anchored by turnkey MDR, integration, and training offerings. LevelBlue's MSSP transition blueprint exemplifies how channel partners monetize recurring revenue via remote SOC operations. Vendors are bundling advisory services-policy tuning, Zero Trust road-mapping, compliance reporting-to maximize lifetime value, thereby cementing services as a structural driver within the cloud endpoint protection market.
Large enterprises contributed 57.45% of the cloud endpoint protection market share in 2025, underpinned by multi-million-dollar security budgets and appetites for early-stage innovation. Their pilots often shape vendor product-roadmaps, especially around AI-assisted threat hunting. Yet SMEs scored a 16.65% CAGR, proving that SaaS pricing and outsourced SOCs democratize sophisticated defenses. SonicWall confirms heightened SMB uptake of EDR capabilities once considered "big-bank only".
Cost predictability and rapid onboarding make subscription models appealing to finance-constrained firms. Meanwhile, compliance automation embedded in cloud consoles eases audit anxiety. Hence the SME segment is reshaping go-to-market tactics across the cloud endpoint protection market, prompting vendors to launch one-click packages with usage-based billing and curated playbooks.
Complete Report Scope:
- By Component
- Solutions
- Antivirus / Anti-malware
- Endpoint Detection and Response (EDR)
- Firewall
- Application / Device Control
- Services
- Managed Services
- Consulting and Integration
- Training and Support
- Solutions
- By Enterprise Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
- By Security Type
- Antivirus / Anti-malware
- Endpoint Detection and Response
- Firewall
- Device Control
- Anti-phishing
- Application Control
- Others
- By End-user Industry
- Banking, Financial Services and Insurance (BFSI)
- Government
- Healthcare
- Energy and Power
- Retail and E-commerce
- IT and Telecom
- Manufacturing
- Education
- Media and Entertainment
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia
- China
- India
- Japan
- South Korea
- Southeast Asia
- Rest of Asia
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 40.35% of 2025 revenue owing to mature regulatory regimes and long-standing investments in cloud security. Federal Zero Trust blueprints and large-scale SaaS adoption keep refresh cycles brisk. The region's enterprises adopted AI-driven XDR platforms early, shaping feature roadmaps and anchoring spend on next-generation endpoint suites. Venture capital funding and cybersecurity start-up density further fertilize innovation, strengthening North America's position within the cloud endpoint protection market.
Asia-Pacific is the fastest-growing theatre, expanding at a 14.88% CAGR. The region benefits from hyperscaler capital flows such as Microsoft's USD 2.2 billion Malaysian AI hub, Amazon's USD 12.7 billion India build-out, and Google's USD 6.7 billion Singapore expansion. A pronounced spike in ransomware and deep-fake scams compels enterprises to adopt advanced EDR and XDR capabilities, making APAC the next frontier for the cloud endpoint protection market.
Europe commands steady growth underpinned by the NIS2 Directive's stringent penalties. Germany, the United Kingdom, and France spearhead adoption of AI-centric endpoint technologies to meet "state-of-the-art" compliance thresholds. Data-sovereignty sensitivities drive demand for vendors that can localize telemetry and sustain residency assurances, ensuring the region remains strategically salient in the cloud endpoint protection market.
- Bitdefender
- CrowdStrike
- Microsoft
- SentinelOne
- Kaspersky
- Sophos
- VMware
- Cisco
- McAfee
- Trend Micro
- Fortinet
- Broadcom (Symantec)
- Avast
- Palo Alto Networks
- Check Point Software
- Carbon Black
- ESET
- Cybereason
- Malwarebytes
- Trellix
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of remote work and BYOD
- 4.2.2 Surge in sophisticated cyber-attacks & data breaches
- 4.2.3 Regulatory mandates for data protection & privacy
- 4.2.4 Cost-saving scalability of SaaS-based security models
- 4.2.5 Integration of XDR & AI-driven automation boosts ROI
- 4.2.6 Zero-trust adoption accelerates endpoint upgrades
- 4.3 Market Restraints
- 4.3.1 Cyber-talent shortage inflates service costs
- 4.3.2 Deployment complexity in multi-cloud estates
- 4.3.3 Price sensitivity among SMEs
- 4.3.4 Scrutiny of telemetry-data privacy in security tools
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE )
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.1.1 Antivirus / Anti-malware
- 5.1.1.2 Endpoint Detection and Response (EDR)
- 5.1.1.3 Firewall
- 5.1.1.4 Application / Device Control
- 5.1.2 Services
- 5.1.2.1 Managed Services
- 5.1.2.2 Consulting and Integration
- 5.1.2.3 Training and Support
- 5.1.1 Solutions
- 5.2 By Enterprise Size
- 5.2.1 Small and Medium Enterprises (SMEs)
- 5.2.2 Large Enterprises
- 5.3 By Deployment Model
- 5.3.1 Public Cloud
- 5.3.2 Private Cloud
- 5.3.3 Hybrid Cloud
- 5.4 By Security Type
- 5.4.1 Antivirus / Anti-malware
- 5.4.2 Endpoint Detection and Response
- 5.4.3 Firewall
- 5.4.4 Device Control
- 5.4.5 Anti-phishing
- 5.4.6 Application Control
- 5.4.7 Others
- 5.5 By End-user Industry
- 5.5.1 Banking, Financial Services and Insurance (BFSI)
- 5.5.2 Government
- 5.5.3 Healthcare
- 5.5.4 Energy and Power
- 5.5.5 Retail and E-commerce
- 5.5.6 IT and Telecom
- 5.5.7 Manufacturing
- 5.5.8 Education
- 5.5.9 Media and Entertainment
- 5.5.10 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Southeast Asia
- 5.6.4.6 Rest of Asia
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Bitdefender
- 6.4.2 CrowdStrike
- 6.4.3 Microsoft
- 6.4.4 SentinelOne
- 6.4.5 Kaspersky
- 6.4.6 Sophos
- 6.4.7 VMware
- 6.4.8 Cisco
- 6.4.9 McAfee
- 6.4.10 Trend Micro
- 6.4.11 Fortinet
- 6.4.12 Broadcom (Symantec)
- 6.4.13 Avast
- 6.4.14 Palo Alto Networks
- 6.4.15 Check Point Software
- 6.4.16 Carbon Black
- 6.4.17 ESET
- 6.4.18 Cybereason
- 6.4.19 Malwarebytes
- 6.4.20 Trellix
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


