

|
시장보고서
상품코드
2124379
십자인대 재건술 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Cruciate Ligament Repair Procedures - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 십자인대 재건술 시장 규모는 2025년 160억 9,000만 달러, 2026년 174억 4,000만 달러에서 2031년까지 261억 2,000만 달러로 확대되어 2026-2031년까지 CAGR 8.41%를 나타낼 것으로 예측됩니다.
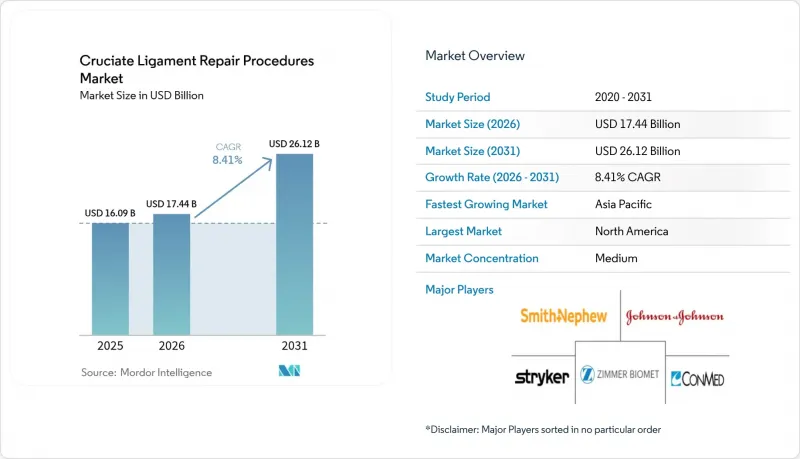
본 보고서는 시술별(전방십자인대(ACL) 재건술, 기타), 이식편 유형별(자가 이식편, 기타), 고정 장치별(간섭 나사, 기타), 최종 사용자별(병원, 외래수술센터(ASC), 기타),지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 십자인대 재건술 시장 동향 및 인사이트
무릎 인대 손상 발생률 증가
미국에서 전방십자인대(ACL) 파열의 발생률은 10만 인년당 75.19건으로, 이로 인해 연간 10만-20만 건의 신규 사례가 발생하고 있습니다. 여성 운동선수는 해부학적 요인과 호르몬적 요인으로 인해 남성에 비해 파열률이 2배에서 8배 더 높습니다. 또한, 16세에서 39세 연령대에서 가장 많은 외상이 발생합니다. 2010년 이후 연간 부상 건수는 감소 추세를 보이고 있지만, 보험사의 보상 범위 확대와 환자들로부터 스포츠 복귀 기간 단축에 대한 요구가 높아짐에 따라 외과적 재건 수술 건수는 연간 2.15%의 속도로 계속 증가하고 있습니다. 이러한 경향은 관절경 수술에 대한 제3자 보험 적용이 조기 수술 결정을 뒷받침하고 있는 북미와 서유럽에서 특히 두드러집니다.
저침습 정형외과 수술에 대한 관심 증가
현재, 경골 터널의 출구 부위를 피하여 수술 후 통증을 경감시킬 수 있는 ‘올 인사이드(All-Inside)’ 관절경 수술법이 주류를 이루고 있습니다. 유럽의 조사에 따르면, 2016년부터 2023년까지 수술 건수가 많은 외과의사들 사이에서 경골 관통법(transtibial drilling)의 시행률은 14.3%에서 3.6%로 감소한 반면, 전내측 접근법과 올인사이드 접근법의 비율은 증가했습니다. 슬개건(무릎뼈 힘줄)을 보존하는 대퇴사두근 건 채취는 기증 부위의 합병증을 더욱 경감시킵니다. Arthrex는 2023년, TightRope 조절식 루프 버튼을 소아 ACL 재건술로도 적용 범위를 확대하여, 성장판을 보호하는 전체 골단 고정이 가능하게 했습니다.
수술 총비용의 급등과 보험 적용 범위의 제한
미국의 무보험 환자는 2만-5만 달러의 청구액에 직면하는 반면, 보험에 가입된 환자라도 본인 부담금으로 2,000-6,000달러를 지불하는 경우가 많습니다. 2010년부터 2022년까지 사춘기 환자의 의료비는 70% 상승했으며, 이에 따라 사전 승인 지침이 엄격해졌습니다. 메디케어의 CPT 27429에 대한 지급 상한액은 1,172달러이지만, 많은 외래 진료 센터는 이를 원가보다 낮은 금액으로 간주하고 있습니다. Cigna의 2024년 8월 기준 보험 규정에 따르면, 1차 ACL 재건술은 여전히 ‘임상시험 단계’로 분류되어 있으며, BEAR 스캐폴드에 대한 보험 적용이 제한되어 있습니다.
부문 분석
2025년, 전방십자인대(ACL) 재건술은 십자인대 재건술 시장에서 54.84%의 점유율을 유지했습니다. 그러나 BEAR 스캐폴드의 적응증 확대에 따라 ACL 복원술은 2031년까지 연평균 성장률(CAGR) 10.53%를 나타낼 것으로 예측됩니다. 2025년 3월 이후 5,000건 이상의 BEAR 수술이 시행되었으며, 초기 데이터에 따르면 2년 후 재파열률은 15%로 자가 이식편과 동등한 것으로 나타났습니다. 그 결과, 특히 햄스트링 보존 및 조기 재활을 중시하는 젊은 층에서 2031년까지 이 재건술이 첫 수술 건수의 15%-20%를 차지할 가능성이 있습니다. 후방 십자인대(PCL) 수술 건수는 PCL 손상이 무릎 외상 전체의 불과 3%-5%에 불과하기 때문에 총 수술 건수의 10% 미만에 그치고 있습니다. 재건술은 이식편의 노화 및 재발성 손상을 배경으로, 안정적이면서도 성장하고 있는 틈새 시장입니다.
2025년에는 자가 이식 조직이 매출의 46.76%를 차지했습니다. 이는 25세 미만의 실패율이 9.6%인 골-슬개건-골 및 햄스트링 이식편에 의해 뒷받침되고 있습니다. 스미스 앤 네퓨(Smith & Nephew)사의 QUADTRAC 가이드를 사용하여 상용화된 대퇴사두근 힘줄을 이용한 방법은 1년 후 재수술률이 2.4%로 가장 낮습니다. 동종 이식편은 젊은 운동선수에게서 25%의 실패율을 보임에도 불구하고, 고령 환자나 재수술 사례에서는 여전히 선호되고 있습니다. 그 이유 중 하나는 수술 시간을 15-20분 단축할 수 있다는 점에 있습니다. CAGR 10.87%로 가장 빠르게 성장하고 있는 부문인 생체 유래 스캐폴드는 BEAR 임플란트의 승인 범위 확대와 스트라이커(Stryker)사의 합성 재료와의 통합을 통해 성장세를 더하고 있습니다. 차세대 합성 이식편은 내구성이 자가 이식편과 동등하다면, 2031년까지 5%-8% 시장 점유율에 도달할 가능성이 있습니다.
지역별 분석
북미는 2025년에 전 세계 매출의 42.65%를 차지하며, 연간 10만-20만 건의 전방십자인대(ACL) 수술이 시행되고 있지만, 발병률이 감소하고 수술 건수가 정체되어 있어 성장이 둔화되고 있습니다. 유럽은 매출의 약 4분의 1을 차지하고 있으며, 해부학적 터널법이나 외측 관절외 보강법으로의 전환이 진행되고 있습니다. 아시아태평양은 2031년까지 9.54%의 성장이 예상되며, 중국의 82% 가격 인하가 이를 뒷받침하고 있습니다. 이러한 가격 인하는 공급업체의 이익률을 압박하는 한편, 지방 지역의 접근성을 확대시켰습니다. 일본과 한국은 높은 병상 밀도를 활용해 수술 시행률 1위를 유지하고 있는 반면, 인도에서는 보험 적용 범위가 세분화되어 있어 보급이 억제되고 있습니다. 중동 및 아프리카와 남미는 매출의 약 12%-15%를 차지하고 있으며, 걸프 국가들의 스포츠 의료에 대한 투자와 브라질의 의료기기 승인 절차 신속화가 추가 성장을 뒷받침하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the cruciate ligament repair procedures market size is projected to expand from USD 16.09 billion in 2025 and USD 17.44 billion in 2026 to USD 26.12 billion by 2031, registering a CAGR of 8.41% between 2026 to 2031.
This report is Segmented by Procedure (ACL Repair, and More), Graft Type (Autograft, and More), Fixation Device (Interference Screws, and More), End User (Hospitals, Ambulatory Surgical Centers, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Cruciate Ligament Repair Procedures Market Trends and Insights
Increasing Incidence of Knee Ligament Injuries
ACL tears occur at a rate of 75.19 per 100,000 person-years in the United States, resulting in 100,000-200,000 new cases annually. Female athletes experience rupture rates two- to eight-fold higher than males because of anatomic and hormonal factors, while the 16-to-39-year bracket sees the most trauma. Although annual injury counts eased after 2010, surgical reconstruction volumes continued to climb by 2.15% per year as payers expanded reimbursement and patients demanded quicker return-to-sport timelines. The shift is most visible in North America and Western Europe, where third-party coverage for arthroscopy encourages early surgical decision-making.
Rising Preference for Minimally Invasive Orthopedic Procedures
All-inside arthroscopic techniques now dominate because they avoid tibial tunnel exit points and reduce postoperative pain. European surveys show transtibial drilling fell from 14.3% to 3.6% of high-volume surgeons between 2016 and 2023, while anteromedial and all-inside portals increased. Quadriceps-tendon harvests, which spare the patellar tendon, further improve donor-site morbidity. Arthrex extended its TightRope adjustable-loop button to pediatric ACL reconstruction in 2023, allowing all-epiphyseal fixation that protects the growth plate.
Elevated Total Procedure Cost and Limited Payer Coverage
Uninsured U.S. patients face bills of USD 20,000-50,000, while insured patients often pay USD 2,000-6,000 out of pocket. Adolescent charges climbed 70% between 2010 and 2022, prompting stricter prior-authorization guidelines. Medicare's allowable for CPT 27429 is USD 1,172, which many ambulatory centers consider below cost. Cigna's August 2024 policy still classifies primary ACL repair as investigational, curbing reimbursement for the BEAR scaffold.
Other drivers and restraints analyzed in the detailed report include:
- Advancements In Biologic and Synthetic Graft Technologies
- Integration of Artificial Intelligence into Surgical Planning & Navigation
- Risk of Surgical Failure and Need for Revision Procedures
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
ACL reconstruction maintained a 54.84% share of the cruciate ligament repair procedures market in 2025. However, ACL repair is forecast to grow at a 10.53% CAGR through 2031 as the BEAR scaffold expands indications. More than 5,000 BEAR procedures have been performed since March 2025, with early data showing a 15% two-year re-tear rate comparable to that of autograft. As a result, repair could capture 15%-20% of primary cases by 2031, especially in younger cohorts that value hamstring preservation and faster rehabilitation. Posterior cruciate ligament (PCL) work accounts for less than 10% of volume because PCL injuries represent only 3%-5% of knee trauma. Revision reconstruction is a stable but growing niche, driven by aging grafts and repeat injuries.
Autograft tissue generated 46.76% revenue in 2025, supported by bone-patellar tendon-bone and hamstring grafts, which show a 9.6% failure rate under 25 years. Quadriceps-tendon options, commercialized with Smith & Nephew's QUADTRAC guide, deliver the lowest 2.4% one-year reoperation rate. Allografts remain preferred for older or revision cases despite their 25% failure in young athletes, partly because they shave 15-20 minutes off operating time. Biologic scaffolds, the fastest-growing segment at 10.87% CAGR, are riding the BEAR implant's expanded clearances and Stryker's synthetic integrations. Next-generation synthetic grafts may reach a 5%-8% share by 2031 if their durability matches that of autografts.
Complete Report Scope:
- By Procedure
- ACL Repair
- ACL Reconstruction
- PCL Repair
- PCL Reconstruction
- Revision Procedures
- By Graft Type
- Autograft
- Allograft
- Synthetic Graft
- Biologic Scaffolds
- By Fixation Device
- Interference Screws
- Cortical Buttons
- Suture Anchors
- Other Fixation Devices
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Orthopedic & Sports Medicine Clinics
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 42.65% of global revenue in 2025, performing 100,000-200,000 ACL procedures annually, but growth is moderating as incidence declines while intervention rates plateau. Europe held roughly one-quarter of revenue, transitioning to anatomic tunnel placement and lateral extra-articular augmentation. Asia-Pacific is set to grow 9.54% through 2031, lifted by China's 82% price cuts that widened rural access even as they pressured supplier margins. Japan and South Korea leverage high bed density to maintain leading procedure rates, whereas India's fragmented coverage restrains uptake. The Middle East & Africa and South America share about 12%-15% of revenue; investment in Gulf sports medicine and Brazil's faster device approvals support incremental gains.
- Acuitive Technologies (Arthrosurface)
- Arthrex
- Bioretec
- Cayenne Medical
- Conmed
- Enovis (Mathys)
- Exactech
- Integra LifeSciences
- Johnson & Johnson
- Karl Storz
- Medtronic
- Miach Orthopaedics
- Orthocell
- Parcus Medical
- RTI Surgical
- Smiths Group
- Stryker
- Tissue Regenix
- Xiros Ltd (Neoligaments)
- Zimmer Biomet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope Of The Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Incidence of Knee Ligament Injuries
- 4.2.2 Rising Preference for Minimally Invasive Orthopedic Procedures
- 4.2.3 Growing Availability of Outpatient Ambulatory Surgery Centers
- 4.2.4 Advancements in Biologic and Synthetic Graft Technologies
- 4.2.5 Expanding Sports Medicine Physician Workforce in Emerging Markets
- 4.2.6 Integration of Artificial Intelligence into Surgical Planning & Navigation
- 4.3 Market Restraints
- 4.3.1 Elevated Total Procedure Cost and Limited Payer Coverage
- 4.3.2 Risk of Surgical Failure and Need For Revision Procedures
- 4.3.3 Stringent Regulatory Pathways for Novel Biologic Implants
- 4.3.4 Skill Gap Among Surgeons in Emerging Economies
- 4.4 Technological Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power Of Buyers/Consumers
- 4.5.2 Bargaining Power Of Suppliers
- 4.5.3 Threat Of New Entrants
- 4.5.4 Threat Of Substitute Products
- 4.5.5 Intensity Of Competitive Rivalry
- 4.6 Value / Supply-Chain Analysis
- 4.7 Regulatory Landscape
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Procedure
- 5.1.1 ACL Repair
- 5.1.2 ACL Reconstruction
- 5.1.3 PCL Repair
- 5.1.4 PCL Reconstruction
- 5.1.5 Revision Procedures
- 5.2 By Graft Type
- 5.2.1 Autograft
- 5.2.2 Allograft
- 5.2.3 Synthetic Graft
- 5.2.4 Biologic Scaffolds
- 5.3 By Fixation Device
- 5.3.1 Interference Screws
- 5.3.2 Cortical Buttons
- 5.3.3 Suture Anchors
- 5.3.4 Other Fixation Devices
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Ambulatory Surgical Centers
- 5.4.3 Orthopedic & Sports Medicine Clinics
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)}
- 6.3.1 Acuitive Technologies (Arthrosurface)
- 6.3.2 Arthrex
- 6.3.3 Bioretec
- 6.3.4 Cayenne Medical
- 6.3.5 CONMED Corporation
- 6.3.6 Enovis (Mathys)
- 6.3.7 Exactech
- 6.3.8 Integra LifeSciences
- 6.3.9 Johnson & Johnson (DePuy Synthes)
- 6.3.10 Karl Storz SE & Co. KG
- 6.3.11 Medtronic
- 6.3.12 Miach Orthopaedics
- 6.3.13 Orthocell
- 6.3.14 Parcus Medical
- 6.3.15 RTI Surgical
- 6.3.16 Smith & Nephew
- 6.3.17 Stryker Corporation
- 6.3.18 Tissue Regenix
- 6.3.19 Xiros Ltd (Neoligaments)
- 6.3.20 Zimmer Biomet
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


