

|
시장보고서
상품코드
2124586
동물 안과 케어 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Veterinary Eye Care - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
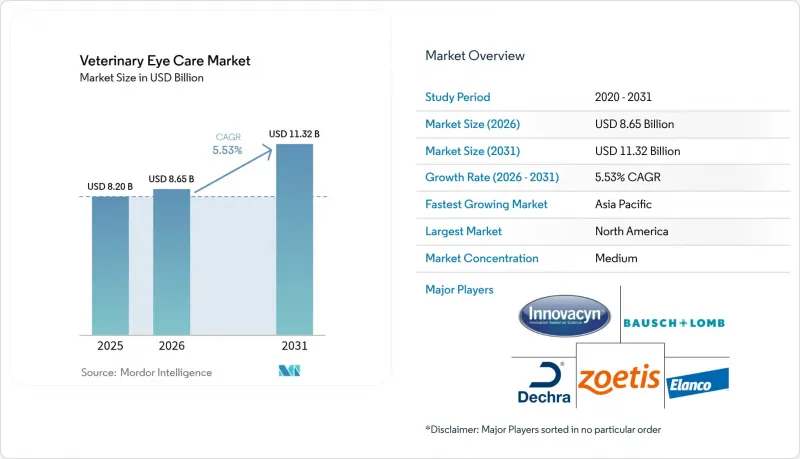
에 의하면, 동물 안과 케어 시장 규모는 2025년에 82억 달러로 평가되었고, 2026년 86억 5,000만 달러에서 2031년까지 113억 2,000만 달러에 이를 것으로 예측되며, 2026-2031년 연평균 복합 성장률(CAGR)은 5.53%를 기록할 전망입니다.
본 보고서는 제품 및 서비스(제품 및 서비스), 용도(개, 고양이, 말, 기타 동물), 용도(건성 각결막염, 결막염 등), 최종 사용자(동물병원, 동물진료소, 학술·연구 기관), 지역(북미, 유럽, 아시아태평양 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 동물 안과 케어 시장 동향 및 인사이트
반려동물 사육 마릿수 증가와 첨단 수의의료에 대한 지출 확대
2025년, 미국 가정에서는 8,730만 마리의 개와 7,630만 마리의 고양이가 사육되고 있으며, 개 1마리당 및 고양이 1마리당 연간 평균 지출액은 각각 598달러 및 529달러에 달했습니다. 정기 건강검진을 위한 내원 건수는 감소한 반면, 안과로 의뢰되는 건수는 증가하여 삶의 질(QOL)을 눈에 띄게 향상시키는 치료로 전환되고 있음이 분명해졌습니다. 조사 대상인 반려인들은 비용 문제와 예약의 어려움을 주요 장벽으로 꼽았으나, 시력 저하로 인해 활동 수준이 위협받을 경우 37%는 여전히 안과 수술을 우선시하고 있습니다. 밀레니얼 세대와 Z세대는 반려동물을 가족의 일원으로 여기기 때문에 전문적인 치료에 대한 관심도가 특히 높습니다. 2023년부터 2024년에 걸쳐 수의학 총 지출은 4% 감소했으나, 신속한 임상적 개선 효과를 입증하고 있는 동물병원에서는 여전히 높은 진료비를 유지하고 있습니다.
반려동물의 안과 질환 유병률 증가
2021년부터 2024년에 걸쳐 실시된 다년간의 연구에 따르면, 개의 2.77%에서 안과 질환이 확인되었으며, 그 주요 질환은 백내장, 각막 궤양, 결막염이었습니다. 견종의 선택은 위험을 증가시킵니다. 프렌치 불독과 핀셔는 유전적 문제를 조장하는 좁은 유전자 풀을 공유하고 있기 때문입니다. ACVO 블루북은 현재 200종 이상의 견종과 관련된 안구 결함을 추적하며, 브리더의 조기 검사를 지원하고 있지만, 상업적 인센티브로 인해 여전히 인기 있는 단두종 혈통이 선호되고 있습니다. 말의 재발성 포도막염은 일부 지역에서 말의 최대 25%에 영향을 미치고 있어, 지속형 임플란트에 대한 새로운 수요를 창출하고 있습니다. 유전자 검사의 보급으로 무증상 병변이 조기에 발견됨에 따라, 치료 대상이 되는 환자 수는 계속 증가하고 있습니다.
부문 분석
서비스 부문은 급속한 성장세를 보이며 2026-2031년 연평균 성장률(CAGR) 6.85%로 증가할 것으로 예상되는 반면, 제품 부문은 2025년 기준 매출에서 75.55%의 점유율을 유지했습니다. 진료소에서는 진단, 수술, 경과 관찰을 제품 판매와 분리하는 경향이 강해지고 있으며, 이를 통해 지속적인 서비스 수익이 창출되고 있습니다. 원격 안과 진료 세션을 통해 일반 개업의는 복잡한 각막 궤양을 전문의에게 의뢰하기 전에 결막염이나 안구건조증의 초기 진단을 내릴 수 있게 되었습니다. 현재로서는 검증 기준을 충족하는 AI 플랫폼은 존재하지 않지만, 원격 지도를 통해 이미 의뢰 대기 시간이 단축되고 있습니다. 이러한 추세를 고려할 때, 수의안과 치료 시장은 시술과 경과 관찰을 결합한 패키지형 서비스로 계속해서 전환될 것으로 보입니다.
의약품은 여전히 수익의 주축이며, 21 CFR Part 524에 따라 등록된 사이클로스포린 연고와 3제 복합 항생제 젤이 핵심을 이루고 있습니다. 데클라(Decla)사가 2024년에 출시한 재생의료용 젤은 각막 회복을 촉진하고 수술률을 낮추는 프리미엄급 제품으로 시장에 진입했습니다. 기구 및 임플란트는 여전히 틈새 시장이지만, 정밀한 기술이 요구되기 때문에 고가 대에서 거래되고 있습니다. 리바운드식 안압계 등의 진단 기기는 현재 주류 동물병원 접수처에 상비되어, 소개 환자의 유입 경로는 좁아지는 반면, 1차 진료 시설 내에서의 시술 수행률은 향상되고 있습니다.
2025년 매출액 중 개가 50.53%를 차지하고 있는데, 이는 개가 동물 인구의 대부분을 차지할 뿐만 아니라 백내장이나 KCS(건성 각결막증)에 대한 유전적 소인이 있음을 반영합니다. 그러나 가장 빠른 성장세를 보이고 있는 것은 말 관련 증례로, 이 분야에서는 초맥락막 사이클로스포린 임플란트가 한쪽 눈당 2,000달러 이상의 가격에 판매되고 있습니다. 경주마 소유주들은 사랑하는 말의 경주 경력을 유지하기 위해 이러한 비용을 아끼지 않습니다. 고양이는 바이러스성 결막염과 각막 낭종증으로 인해 진료 건수가 증가하고 있지만, 단가가 낮기 때문에 이 부문의 수익 가치는 제한적입니다. 니치 시장인 이국적인 동물(토끼나 조류) 분야는 도시 지역의 동물병원이 소동물 진료 서비스 라인을 추가함에 따라 완만하게 성장하고 있습니다.
개는 여전히 대중 시장에서 중요한 위치를 차지할 것이지만, 말은 건당 진료비에서 상대적으로 큰 비중을 차지하고 있습니다. 줄기세포 연구가 성숙해짐에 따라, 고가의 치료법은 우선 말 전문 진료에 도입된 후, 점차 개 진료로도 확산될 가능성이 있습니다. 다종 동물 진료에 대한 전문 지식을 구축한 동물병원은 단일 동물 종 수요 변동에 대한 리스크 헤지를 확보할 수 있습니다.
지역별 분석
북미는 밀집된 전문 진료 네트워크와 25% 이상의 반려동물 보험 보급률에 힘입어 2025년 전 세계 매출의 38.62%를 차지했습니다. 미국에서 개 1마리당 평균 진료비는 598달러에 달했으나, 반려인들이 정기 검진을 자제하는 한편 시력 유지를 위한 수술은 받게 함에 따라 전체 수의 의료비는 4% 감소했습니다. 2024년에 도입된 FDA의 무균성 관련 규제로 인해, 미국의 의약품 기준은 전 세계적으로 막대한 영향력을 행사하게 되었습니다. 캐나다와 멕시코는 꾸준히 성장하고 있지만, 지방 지역의 전문의 부족은 미국의 농업 지대에서 볼 수 있는 상황과 유사합니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 6.22%로 가장 높은 성장세를 기록하고 있습니다. 중국에서는 도시 지역의 독신자나 고령자가 반려동물 사육을 주도하고 있지만, 돌봄은 여전히 도시 지역에 집중되어 있습니다. 일본의 고령화 사회에서는 반려동물과의 유대감이 중요시되며, 관련 지출은 고도의 수술에 집중되고 있습니다. 호주는 높은 보험 가입률과 수입 의료기기에 대한 EU 기준에 부합하는 원활한 규제의 혜택을 받고 있습니다. 인도와 한국은 사모펀드 자금을 유치하여 안과 진료실을 병설한 다점포 체인을 구축하고 있습니다. 인증된 안과 전문의는 여전히 희소하기 때문에 간소화된 레이저 치료와 원격 지도가 보급되고 있습니다.
유럽에서는 수요가 성숙 단계에 접어들었으며, 독일, 영국, 프랑스가 전문 의료 기관 밀도 면에서 선두를 달리고 있습니다. 유럽의약품청(EMA)은 국경을 초월한 승인 절차를 효율화하고 있지만, 동유럽에서는 인력 부족에 직면해 있습니다. 영국에서는 평생형과 기간 한정형 보험 플랜이 혼재되어 있어 보험 급여의 일관성에 영향을 미치고 있습니다. 중동 및 아프리카에서는 아랍에미리트와 남아프리카공화국에만 대규모 의뢰 의료기관이 존재하는 반면, 라틴아메리카의 브라질과 아르헨티나는 성장세를 보이고 있으나 통화 및 수입 관세 변동으로 어려움을 겪고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the veterinary eye care market size was valued at USD 8.20 billion in 2025 and estimated to grow from USD 8.65 billion in 2026 to reach USD 11.32 billion by 2031, at a CAGR of 5.53% during 2026-2031.
This report is Segmented by Products & Services (Products and Services), Application (Dog, Cat, Horses, and Other Animals), Application (Keratoconjunctivitis Sicca, Conjunctivitis, and More), End-User (Veterinary Hospitals, Veterinary Clinics, and Academic & Research Institutes) and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Veterinary Eye Care Market Trends and Insights
Growing Pet Ownership & Spend on Advanced Veterinary Care
United States households kept 87.3 million dogs and 76.3 million cats in 2025, and the average annual spend per dog and per cat reached USD 598 and USD 529, respectively. Routine wellness traffic fell, yet ophthalmology referrals rose, revealing a shift toward interventions that deliver a visible quality-of-life lift. Surveyed owners cite affordability and appointment scarcity as primary barriers, yet 37% still prioritize eye surgery when vision loss threatens activity levels. Millennials and Generation Z over-index on specialty procedures because they view pets as family. Although total veterinary expenditures dipped 4% between 2023 and 2024, clinics that prove rapid clinical gains continue to defend premium fees.
Rising Prevalence of Ocular Disorders in Companion Animals
A multi-year study covering 2021-2024 found ocular disease in 2.77% of dogs, led by cataracts, corneal ulcers, and conjunctivitis. Breed selection amplifies risk as French Bulldogs and Pinschers share narrow gene pools that magnify hereditary problems. The ACVO Blue Book now tracks more than 200 breed-linked eye defects, helping breeders test early, yet commercial incentives still favor popular brachycephalic lines. Equine recurrent uveitis affects up to 25% of horses in some regions, creating new demand for long-acting implants. Wider use of genetic screens uncovers subclinical lesions sooner, so the addressable population keeps rising.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Portfolio of Topical Ophthalmic Drugs & Ointments
- Demand for Minimally Invasive Ophthalmic Surgeries
- High Cost of Advanced Ocular Equipment & Surgery
- Limited Insurance Reimbursement for Veterinary Eye Care
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services generated rapid momentum, increasing at a 6.85% CAGR for 2026-2031, while products preserved a 75.55% revenue lead in 2025. Clinics increasingly unbundle diagnostics, surgery, and follow-up care from product sales, creating recurring service revenue. Tele-ophthalmology sessions let general practitioners triage conjunctivitis or dry eye before escalating complex ulcers. Even though no AI platform meets validation standards today, remote guidance already reduces referral wait times. The trajectory suggests that the Veterinary Eye Care market will continue to shift toward bundled procedure-plus-monitoring packages.
Drugs remain the backbone of revenue, anchored by cyclosporine ointment and triple-antibiotic gels registered under 21 CFR Part 524. Dechra's 2024 regenerative gel added a premium tier that accelerates corneal recovery and lowers surgery rates. Instruments and implants remain niche but command high prices due to precision engineering. Diagnostic devices such as rebound tonometers now occupy reception desks in mainstream clinics, narrowing the referral funnel and lifting procedure capture rates inside primary practices.
Dogs accounted for 50.53% of 2025 revenue, reflecting both population dominance and a genetic predisposition to cataracts and KCS. Yet the fastest growth lies in equine cases, where suprachoroidal cyclosporine implants fetch above USD 2,000 per eye. Owners of performance horses accept these costs to preserve their sport careers. Cats add volume with viral conjunctivitis and corneal sequestrum, but lower price points limit category value. Niche exotic rabbits and birds grow slowly as urban clinics add small-mammal service lines.
Dogs will retain mass-market importance, yet horses add disproportionate dollars per procedure. As stem-cell research matures, premium therapies may first migrate to equine referrals, then trickle into canine practice. Clinics that build mixed-animal expertise gain a hedge against demand swings inside any single species pool.
Complete Report Scope:
- By Products & Services
- Product
- Ophthalmic Drugs
- Surgical Instruments
- Diagnostic Devices & Imaging
- Ocular Implants & Disposables
- Services
- Ophthalmic Surgical Services
- Diagnostic Imaging Services
- Tele-Ophthalmology & Consultation
- Post-operative Care Services
- Product
- By Animal Type
- Dogs
- Cats
- Horses
- Other Animals
- By Application
- Keratoconjunctivitis Sicca (Dry Eye)
- Conjunctivitis
- Corneal Ulcers & Injuries
- Glaucoma
- Uveitis & Retinal Disorders
- Others
- By End-user
- Veterinary Hospitals
- Veterinary Clinics
- Academic & Research Institutes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 38.62% of 2025 global revenue, driven by dense specialty networks and 25%-plus pet insurance penetration. Average U.S. spend per dog touched USD 598 while overall vet spending slipped 4% as owners skipped routine checks but not sight-saving surgery. FDA sterility rules rolled out in 2024 give U.S. drug standards outsized global influence. Canada and Mexico expand steadily, though rural shortages of specialists mirror those in the U.S. farm belt.
Asia-Pacific records the quickest 6.22% CAGR through 2031. China's urban singles and seniors drive companion adoption, yet care remains city-centric. Japan's aging society values pet companionship, channeling spending into advanced surgery. Australia benefits from high insurance uptake and seamless EU-aligned regulation for imported devices. India and South Korea attract private equity to build multi-location chains that embed ophthalmology suites. Board-certified ophthalmologists remain rare, so simplified lasers and remote mentoring gain traction.
Europe offers mature demand, with Germany, the United Kingdom, and France leading specialty density. The EMA streamlines cross-border approvals, yet Eastern Europe faces staffing gaps. The United Kingdom's mix of lifetime and time-limited insurance plans affects reimbursement consistency. In the Middle East and Africa, only the United Arab Emirates and South Africa host sizeable referral centers, while Latin America's Brazil and Argentina grow but wrestle with currency and import duty volatility.
- Alcon
- Bausch + Lomb Corporation
- BOVA UK
- Ceva Sante Animale S.A.
- Covetrus
- Dechra Pharmaceuticals
- Eickemeyer Veterinary Equipment
- Elanco Animal Health Inc.
- Epicur Pharma
- I-Med Animal Health
- Innovacyn
- Merck & Co., Inc. (MSD Animal Health)
- Neogen
- OCuSOFT Inc.
- Santicare LLC
- Tarsus Pharmaceuticals Inc.
- Topcon
- Vetoquinol S.A.
- Zoetis
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Pet Ownership & Spend on Advanced Veterinary Care
- 4.2.2 Rising Prevalence of Ocular Disorders in Companion Animals
- 4.2.3 Expanding Portfolio of Topical Ophthalmic Drugs & Ointments
- 4.2.4 Demand for Minimally Invasive Ophthalmic Surgeries
- 4.2.5 AI-Enabled Imaging & Tele-Ophthalmology Adoption
- 4.2.6 Stem-Cell and Other Regenerative Corneal-Repair Therapies
- 4.3 Market Restraints
- 4.3.1 High Cost of Advanced Ocular Equipment & Surgery
- 4.3.2 Limited Insurance Reimbursement for Veterinary Eye Care
- 4.3.3 Stringent Regulatory Approval Timelines for Veterinary Drugs
- 4.3.4 Shortage of Board-Certified Veterinary Ophthalmologists
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Products & Services
- 5.1.1 Product
- 5.1.1.1 Ophthalmic Drugs
- 5.1.1.2 Surgical Instruments
- 5.1.1.3 Diagnostic Devices & Imaging
- 5.1.1.4 Ocular Implants & Disposables
- 5.1.2 Services
- 5.1.2.1 Ophthalmic Surgical Services
- 5.1.2.2 Diagnostic Imaging Services
- 5.1.2.3 Tele-Ophthalmology & Consultation
- 5.1.2.4 Post-operative Care Services
- 5.1.1 Product
- 5.2 By Animal Type
- 5.2.1 Dogs
- 5.2.2 Cats
- 5.2.3 Horses
- 5.2.4 Other Animals
- 5.3 By Application
- 5.3.1 Keratoconjunctivitis Sicca (Dry Eye)
- 5.3.2 Conjunctivitis
- 5.3.3 Corneal Ulcers & Injuries
- 5.3.4 Glaucoma
- 5.3.5 Uveitis & Retinal Disorders
- 5.3.6 Others
- 5.4 By End-user
- 5.4.1 Veterinary Hospitals
- 5.4.2 Veterinary Clinics
- 5.4.3 Academic & Research Institutes
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Alcon Inc.
- 6.3.2 Bausch + Lomb Corporation
- 6.3.3 BOVA UK
- 6.3.4 Ceva Sante Animale S.A.
- 6.3.5 Covetrus, Inc.
- 6.3.6 Dechra Pharmaceuticals PLC
- 6.3.7 Eickemeyer Veterinary Equipment
- 6.3.8 Elanco Animal Health Inc.
- 6.3.9 Epicur Pharma
- 6.3.10 I-Med Animal Health
- 6.3.11 Innovacyn Inc.
- 6.3.12 Merck & Co., Inc. (MSD Animal Health)
- 6.3.13 Neogen Corporation
- 6.3.14 OCuSOFT Inc.
- 6.3.15 Santicare LLC
- 6.3.16 Tarsus Pharmaceuticals Inc.
- 6.3.17 Topcon Corporation
- 6.3.18 Vetoquinol S.A.
- 6.3.19 Zoetis Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


