

|
시장보고서
상품코드
2124612
초음파 젤 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Ultrasound Gel - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
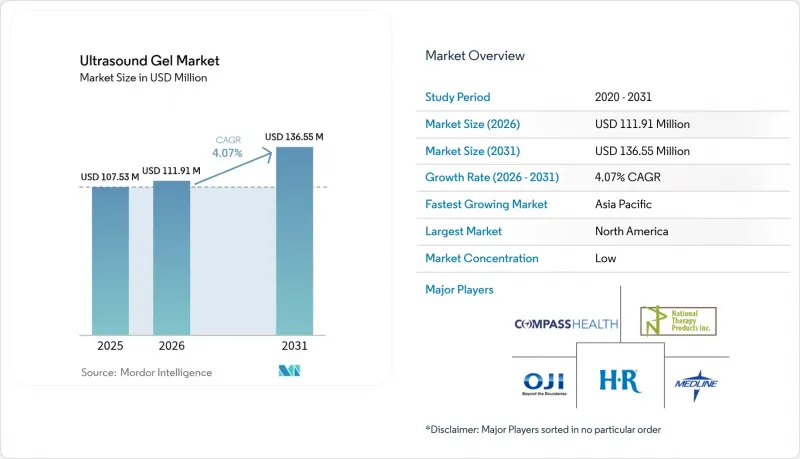
에 의하면, 초음파 젤 시장 규모는 2025년 1억 753만 달러로 평가되었습니다. 2026년에는 1억 1,191만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 4.07%로 성장을 지속하여, 2031년에는 1억 3,655만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품 유형(비멸균, 멸균), 용도(진단용 영상 진단, 치료용 초음파 및 물리치료, 미용·피부과 시술), 최종 사용자(병원 및 클리닉, 진단용 영상 진단센터 등), 지역(북미, 유럽,아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 초음파 젤 시장 동향 및 인사이트
응급 의료 및 1차 진료 분야에서 포인트 오브 케어 초음파(POCUS) 도입 확대
POCUS 기기의 보급으로 일상적인 영상 진단이 방사선과에서 트리아지실 및 지역 진료소로 이동하고 있으며, 이에 따라 일회용 젤의 사용자층이 대폭 확대되고 있습니다. WONCA는 2024년, POCUS를 가정의에게 필수적인 진단 도구로 공식 인정함으로써, 1차 진료 제공업체들 사이에서 그 수요가 확고하게 자리 잡았음을 입증했습니다. Vscan Air, Mindray TE Air, Lumify, Butterfly iQ+ 등의 핸드헬드 프로브 시장 침투는 휴대용 하드웨어와 젤 소비량 증가 사이에 명확한 상관관계가 있음을 보여줍니다. 멸균 처리된 소형 파우치는 환자 간 기기 이동 시 교차 오염을 최소화하며, 감염 관리 프로토콜을 준수합니다. POCUS가 구급차나 원격 의료 현장에서 일상화됨에 따라, 각 제조업체는 신속한 폐기가 가능한 포켓 사이즈의 소포장을 개발하고 있습니다. 이러한 도입 추세로 인해 성숙한 병원 시장에서도 기준 판매량 증가가 예상됩니다.
산부인과 초음파 검사 건수의 급격한 증가
의과대학에서는 산부인과 초음파 검사의 숙련도를 빠르게 높일 수 있는 시뮬레이터를 활용한 연수 프로그램이 도입되고 있습니다. 숙련된 초음파 검사 기사의 졸업률이 높아짐에 따라 시설당 검사 건수가 증가하여 안정적인 젤 수요로 이어집니다. 또한, 방사선 피폭 없이 태아의 건강 상태를 확인할 수 있는 초음파 검사로 인해, 민간 불임 치료 클리닉이나 조산원에서도 검사 건수가 증가하고 있습니다. 아시아태평양, 특히 인도와 중국에서는 산전 선별 검사 프로그램이 급속히 성장하고 있어, 비용 효율이 뛰어난 비멸균 병의 지역적 소비를 뒷받침하고 있습니다. 제품 혁신 측면에서는 융모 채취 시 가시성을 향상시키는 착색 젤이 등장하면서 틈새 처방의 필요성이 부각되고 있습니다.
젤이 필요 없는 드라이 트랜스듀서 및 막 결합 기술의 부상
조사 그룹은 커플링 젤을 사용하지 않고 캐비테이션 포켓을 형성하는 피부에 밀착되는 초음파 패치를 실증했으며, 전임상시험에서 유효 성분의 경피 전달률을 26.2배 높이는 데 성공했습니다. 피부과 진료 현장에서도 젤 도포를 신속하게 대체할 수 있는 수단으로, 물이 채워진 장갑이나 일회용 멤브레인에 대한 실험이 진행되고 있습니다. 상용화는 아직 초기 단계이지만, 드라이 인터페이스가 비용 면에서 동등한 수준에 도달한다면 기관 구매자들은 정책을 전환할 가능성이 있어, 장기적인 판매량 성장에 구조적인 위협이 될 우려가 있습니다. 이에 대응해 젤 공급업체들은 얇은 하이드로겔 층과 일회용 멤브레인을 결합한 하이브리드 제품으로 대응하고 있으며, 젤을 전혀 필요로 하지 않는 시스템의 보급을 늦추는 것을 목표로 하고 있습니다.
부문별 분석
2025년, 비멸균 겔은 매출 점유율 70.84%를 유지했습니다. 이는 일상적인 방사선 검사 및 물리치료 세션이 합쳐져 일일 사용량의 상당 부분을 차지하기 때문입니다. 초음파 젤 시장에서 비멸균 병 제품 시장 규모는 멸균 소포장으로의 단위 전환이 진행되고 있음에도 불구하고 꾸준히 성장할 것으로 예측됩니다. 병원이 여전히 주요 구매자이지만, 스포츠 의학 클리닉과 학술 연구소도 안정적인 2차 판매 경로를 형성하고 있습니다. 각 공급업체들은 검사 건수가 많은 날에 역류로 인한 오염을 억제하는 펌프식 패키지에 중점을 두고 있습니다.
멸균 제제는 절대값으로는 작지만, 2031년까지 연평균 성장률(CAGR) 8.18%를 나타낼 것으로 예측되며, 이는 제품 부문 중 가장 높은 성장률입니다. 이러한 성장 추세의 배경에는 중재적 방사선학실 및 중환자실의 엄격한 감염 관리 프로토콜이 있습니다. 침습적 시술에서 대용량 병에서 일회용 파우치로 전환이 진행됨에 따라, 초음파 젤 시장 내 멸균된 파우치의 점유율은 상승할 것으로 예측됩니다. 각 제조업체는 검증된 무균 보증 수준을 달성하면서도 유변학적 특성을 유지하기 위해 감마선 조사 및 전자선 멸균을 활용하고 있습니다.
지역별 분석
2025년, 북미는 전 세계 매출의 38.92%를 차지했습니다. 높은 검사 실시 빈도, 유리한 보험 환급 제도, 그리고 POCUS의 조기 도입이 이러한 선도적 지위를 뒷받침하고 있습니다. 병원에서는 침습적 용도를 위한 멸균 파우치 사용이 점점 표준화되고 있어 프리미엄 부문의 성장을 뒷받침하고 있습니다. 또한, 의료 서비스 제공업체들은 젤이 필요 없는 패치의 시범 도입도 진행하고 있어, 이 지역이 ‘ 수요의 중심’인 동시에 ‘혁신의 시험장’이라는 이중적인 역할을 수행하고 있음을 보여줍니다. 학술 연구비 지원을 통해 생분해성 패키지에 대한 연구가 자금 지원을 받고 있어, 식물 유래 소포를 제공하는 공급업체에게 새로운 기회가 열리고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 8.54%로 가장 빠르게 성장하는 지역입니다. 건강보험 적용 범위가 확대됨에 따라 중국과 인도의 중규모 도시 병원들이 휴대용 초음파 카트를 도입할 수 있게 되었으며, 그 결과 연간 스캔 건수가 증가하고 있습니다. 현지 제조업체들은 비용을 최적화한 비멸균 젤로 가격에 민감한 시장에 진출하고 있지만, 특수 멸균 제품 분야에서는 여전히 다국적 기업들이 지배적입니다. 도시 지역 소비자들은 가정에서 받는 미용 시술을 점점 더 선호하고 있어 소매 수요를 뒷받침하고 있습니다. 산모 및 태아 건강에 관한 정부 주도의 검진 캠페인 또한 판매량을 더욱 끌어올리고 있습니다.
유럽은 여전히 큰 시장 규모를 유지하고 있지만, 아시아태평양에 비해 성장세는 완만합니다. 엄격한 방부제 관련 지침으로 인해 지속적인 성분 변경이 요구되고 있어, 규정 준수 비용은 상승하고 있지만 프리미엄 제품의 차별화에도 기여하고 있습니다. 지속가능성에 대한 요구로 인해 PLA 및 PHA를 사용한 소포장 소재에 대한 실험이 촉진되고 있으며, 독일과 북유럽 국가에서는 시범 프로그램이 진행 중입니다. 병원에서는 노인 돌봄을 위한 원격 초음파 검사 서비스가 도입되어, 간접적으로 일회용 소포장 제품의 소비를 늘리고 있습니다.
중동, 아프리카 및 남미는 시장 점유율은 작지만 그 비중은 증가 추세에 있습니다. GCC 국가들은 고급 진단센터에 투자하고 있으며, 수입된 초음파 진단 장비를 보완하는 멸균 팩을 선호하여 채택하고 있습니다. 브라질의 산부인과 진료소에서는 정기적인 산전 초음파 검사가 확대되고 있는 반면, 아르헨티나 대도시권의 민간 클리닉에서는 미용 목적의 초음파 검사가 도입되고 있습니다. 현지 유통업체은 공급의 지속성을 확보하기 위해 파커 래버러토리즈, HR 파마슈티컬스, 메드라인과 독점 계약을 체결했습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the ultrasound gel market size is expected to grow from USD 107.53 million in 2025 to USD 111.91 million in 2026 and is forecast to reach USD 136.55 million by 2031 at 4.07% CAGR over 2026-2031.
This report is Segmented by Product Type (Non-Sterile, Sterile), Application (Diagnostic Imaging, Therapeutic Ultrasound & Physiotherapy, Aesthetic & Dermatology Procedures), End User (Hospitals & Clinics, Diagnostic Imaging Centers, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Ultrasound Gel Market Trends and Insights
Rising Adoption of Point-of-Care Ultrasound (POCUS) in Emergency & Primary Care
POCUS devices are moving routine imaging from radiology suites to triage rooms and community clinics, sharply widening the user base for single-use gels. WONCA formally recognized POCUS as a core diagnostic tool for family physicians in 2024, validating demand among primary-care providers. Market penetration of handheld probes such as Vscan Air, Mindray TE Air, Lumify, and Butterfly iQ+ demonstrates a clear link between portable hardware and incremental gel consumption. Sterile packettes minimize cross-contamination when devices travel between patients, aligning with infection-control protocols. As POCUS becomes routine in ambulances and telehealth visits, manufacturers are developing pocket-sized sachets designed for quick disposal. This adoption trend is expected to lift baseline unit volumes even in mature hospital markets.
Rapid Procedure Growth in Obstetric & Gynecologic Ultrasound
Medical schools are incorporating simulator-based training programs that accelerate proficiency in obstetric and gynecologic scanning. Higher graduation rates of skilled sonographers translate into more scans per facility, raising steady-state gel demand. Procedure volumes are also expanding in private fertility clinics and midwifery practices, where ultrasound confirms fetal well-being without radiation exposure. Asia-Pacific markets, especially India and China, show steep growth in ante-natal screening programs, reinforcing regional consumption of cost-efficient non-sterile bottles. Product innovations now include color-tinted gels that improve visualization during chorionic-villus sampling, underscoring the need for niche formulations.
Emergence of Gel-Free Dry Transducer & Membrane-Coupling Technologies
Research groups have demonstrated conformable ultrasound patches that create cavitation pockets without coupling gel, achieving 26.2-fold transdermal delivery of active ingredients in pre-clinical trials. Dermatology practices also experiment with water-filled gloves and disposable membranes as quick alternatives to gel coatings. While commercialization remains early, institutional buyers may pivot once dry interfaces reach cost parity, posing a structural threat to long-range volume growth. Gel suppliers are responding with hybrid products that pair thin hydrogel layers with disposable membranes, aiming to slow adoption of fully gel-free systems.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward High-Frequency Linear Transducers Requiring Low-Viscosity, Air-Bubble-Free Gels
- Expansion of Home-Based Physiotherapy & Aesthetic Ultrasound Treatments
- Regulatory Scrutiny of Preservatives Elevating Reformulation Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Non-sterile gels retained a 70.84% revenue share in 2025, driven by routine radiology and physiotherapy sessions that collectively absorb high daily volumes. The ultrasound gel market size for non-sterile bottles is projected to grow steadily despite increasing unit conversion to sterile packettes. Hospitals remain primary buyers, but sports-medicine clinics and academic labs constitute a stable secondary channel. Vendors emphasize pump-style packaging that limits backflow contamination during high-throughput scanning days.
Sterile formulations, although smaller in absolute terms, are projected to post an 8.18% CAGR through 2031, the fastest within product segmentation. Stringent infection-control protocols in interventional radiology suites and intensive-care units underpin this trajectory. The ultrasound gel market share for sterile packettes is expected to climb as disposable sachets replace bulk bottles in invasive procedures. Manufacturers are leveraging gamma-irradiation and e-beam sterilization to preserve rheology while achieving validated sterility assurance levels.
Complete Report Scope:
- By Product Type
- Non-Sterile
- Sterile
- By Application
- Diagnostic Imaging
- Therapeutic Ultrasound & Physiotherapy
- Aesthetic & Dermatology Procedures
- By End User
- Hospitals & Clinics
- Diagnostic Imaging Centers
- Physiotherapy/Sports Medicine Centers
- Home-Care & Retail Consumers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 38.92% of global revenue in 2025. High procedure density, favorable reimbursement, and early adoption of POCUS underpin this leadership. Hospitals increasingly standardize on sterile packettes for invasive use, bolstering premium segment growth. Providers also pilot gel-free patches, illustrating the region's dual role as volume anchor and innovation testbed. Academic grants fund biodegradable-packaging research, opening doors for suppliers offering plant-based sachets.
Asia-Pacific is the fastest-growing territory with an 8.54% CAGR. Expanding health-insurance coverage enables mid-tier city hospitals in China and India to procure portable ultrasound carts, thereby uplifting annual scan counts. Local manufacturers penetrate price-sensitive markets with cost-optimized non-sterile gels, but multinationals still dominate specialty sterile products. Urban consumers increasingly seek at-home aesthetic treatments, feeding retail demand. Government screening campaigns for maternal-fetal health further propel volume.
Europe maintains a sizeable footprint, although growth is modest relative to Asia-Pacific. Strict preservative guidelines compel continuous reformulation, raising compliance costs but also differentiating premium offerings. Sustainability mandates spur experimentation with PLA and PHA sachet materials, with pilot programs underway in Germany and the Nordics. Hospitals embrace tele-ultrasound services for geriatric care, indirectly boosting single-use packette consumption.
Middle East & Africa and South America contribute smaller but rising shares. GCC nations invest in high-end diagnostic centers, favoring sterile packettes that complement imported ultrasound consoles. Brazilian obstetric practices ramp up routine prenatal scans, while Argentina's private clinics adopt aesthetic ultrasound in metropolitan areas. Local distributors form exclusive agreements with Parker Laboratories, HR Pharmaceuticals, and Medline to secure supply continuity.
- Parker Laboratories
- HR Pharmaceuticals Inc.
- Medline Industries
- Compass Health
- National Therapy Products
- Sonogel Vertriebs
- Ultragel Medical
- Besmed Health Business
- Scrip
- Sonofax
- Eco-Med Diagnostic Imaging
- Phyto Performance Italia
- OrthoCanada
- RehabMedic S.L.
- Dynarex
- Roscoe Medical
- L&R USA Inc.
- Geltek-Medica Ltd.
- Zeyco
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Adoption of Point-of-Care Ultrasound (POCUS) in Emergency & Primary Care, Boosting Gel Consumption
- 4.2.2 Rapid Procedure Growth in Obstetric & Gynecologic Ultrasound
- 4.2.3 Shift Toward High-Frequency Linear Transducers Requiring Low-Viscosity, Air-Bubble-Free Gels
- 4.2.4 Expansion of Home-based Physiotherapy & Aesthetic Ultrasound Treatments Stimulating Retail/E-commerce Sales
- 4.2.5 Proliferation of Handheld & Wireless Ultrasound Devices
- 4.2.6 Growing Use of Ultrasound in Sports Medicine
- 4.3 Market Restraints
- 4.3.1 Emergence of Gel-Free Dry Transducer & Membrane-Coupling Technologies
- 4.3.2 Regulatory Scrutiny of Preservatives Elevating Reformulation Costs
- 4.3.3 Disposal Challenges for Single-Use Plastic Sachets in Sustainability-Focused Regions
- 4.3.4 Temperature Sensitivity & Patient Discomfort
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers/Consumers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitute Products
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product Type
- 5.1.1 Non-Sterile
- 5.1.2 Sterile
- 5.2 By Application
- 5.2.1 Diagnostic Imaging
- 5.2.2 Therapeutic Ultrasound & Physiotherapy
- 5.2.3 Aesthetic & Dermatology Procedures
- 5.3 By End User
- 5.3.1 Hospitals & Clinics
- 5.3.2 Diagnostic Imaging Centers
- 5.3.3 Physiotherapy/Sports Medicine Centers
- 5.3.4 Home-Care & Retail Consumers
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Parker Laboratories Inc.
- 6.3.2 HR Pharmaceuticals Inc.
- 6.3.3 Medline Industries LP
- 6.3.4 Compass Health Brands
- 6.3.5 National Therapy Products Inc.
- 6.3.6 Sonogel Vertriebs GmbH
- 6.3.7 Ultragel Medical
- 6.3.8 Besmed Health Business Corp.
- 6.3.9 Scrip Inc.
- 6.3.10 Sonofax
- 6.3.11 Eco-Med Diagnostic Imaging
- 6.3.12 Phyto Performance Italia
- 6.3.13 OrthoCanada
- 6.3.14 RehabMedic S.L.
- 6.3.15 Dynarex Corporation
- 6.3.16 Roscoe Medical
- 6.3.17 L&R USA Inc.
- 6.3.18 Geltek-Medica Ltd.
- 6.3.19 Zeyco
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


