

|
시장보고서
상품코드
2124954
중국의 스마트 빌딩 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)China Smart Building - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
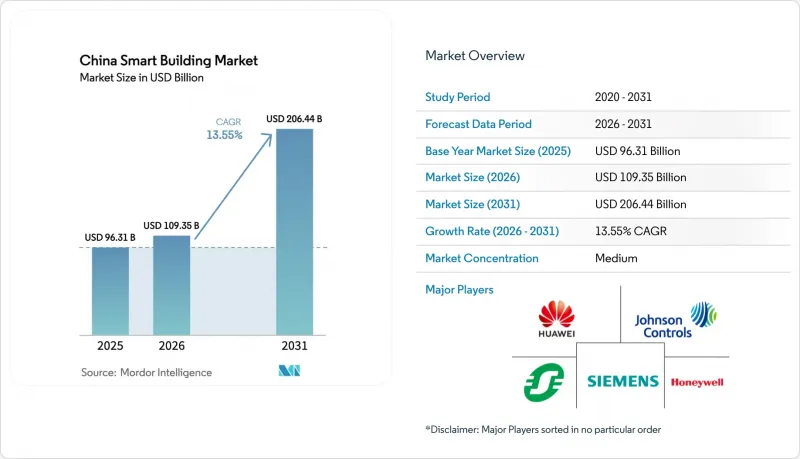
에 의하면, 중국의 스마트 빌딩 시장 규모는 2025년 963억 1,000만 달러에서 2026년에는 1,093억 5,000만 달러에 이르고, 2026-2031년 CAGR 13.55%로 성장을 지속하여 2031년에는 2,064억 4,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 솔루션별(빌딩 에너지 관리 시스템, 인프라 관리 시스템, 지능형 보안 시스템, 통합 업무 공간 관리 플랫폼 등), 구성 요소별(하드웨어, 소프트웨어, 서비스), 연결 방식별(유선, 무선), 건물 유형별(주거, 상업, 산업) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
중국의 스마트 빌딩 시장 동향 및 인사이트
확대되는 정부의 스마트 시티 구상
베이징시의 2024년 지침에 따르면, 2027년까지 1조 2,000억 위안(1,650억 달러)을 투자하여 시정 서비스의 디지털화를 추진하고, 스마트 빌딩을 5G 및 데이터센터와 어깨를 나란히 하는 핵심 인프라로 자리매김하고 있습니다. 이 지침은 16개 모델 지구를 대상으로 하며, 2026년까지 연면적 1만 제곱미터를 초과하는 신규 공공 건축물이 시 데이터 플랫폼과 연동하도록 의무화하고 있습니다. 이러한 준수 기한으로 인해 턴키 프로젝트가 급증하고 있으며, 자동화, 보안, 에너지 관련 모듈을 단일 아키텍처로 통합할 수 있는 공급업체가 유리한 입장에 서 있습니다. 지방 자치 단체는 주택도시농촌건설부가 정한 2024년 스마트 빌딩 기술 사양을 준수하는 것을 보조금 수령 조건으로 삼고 있어, 사실상 시장 진입 장벽을 높이고 있습니다. 그 결과, 중국의 스마트 빌딩 시장은 부동산 시장 전체가 변동하는 상황 속에서도 정책에 뒷받침된 수요의 확실성을 누리고 있습니다.
기존 건축물의 에너지 절약 개보수 수요 증가
중국 건축물 재고의 약 60%는 2010년 에너지 기준 이전에 건설된 것으로, 200억제곱미터 이상에 달하는 개보수의 잠재력을 지니고 있습니다. 탄소 배출 정점 달성 계획에서는 2030년까지 운영 단계에서의 배출량을 15% 감축하는 것을 목표로 하고 있으며, 그 감축량의 절반을 개보수가 차지하게 됩니다. 중국인민은행은 탄소 감축 대출 대상을 건축물의 에너지 관리 프로젝트로 확대하고, 금리를 1.75%로 설정함으로써 소유주의 투자 회수 기간을 단축했습니다. 현재 14개 성에서 임대 계약 갱신 시 에너지 성능 공개가 의무화되어 있으며, 스마트 기능을 갖춘 부동산에는 임대료 프리미엄이 발생하고 있습니다. 상하이에서는 2024년에 자동화 건물의 임대료가 8-12% 상승했습니다. 이러한 인센티브 덕분에 에너지 시스템은 비용 센터에서 수익 증대 요인으로 전환되었으며, 중국의 스마트 빌딩 시장 전체에서 두 자릿수 도입 확대가 지속되고 있습니다.
중소기업에 대한 막대한 초기 투자
종합적인 스마트화 개보수에는 1제곱미터당 최대 200달러의 비용이 소요되며, 이는 상업용 연면적의 40%를 차지하는 임대 수익률이 고작 4-6%에 그치는 중소기업에게는 장벽이 되고 있습니다. 4.5-6.0%에 달하는 상업용 대출 금리는 국영 개발업자를 위해 마련된 중앙은행의 우대 대출 한도의 효과를 상쇄하여 투자 회수 기간을 8-12년으로 연장시키고 있습니다. 저장성과 광둥성에서는 비용의 20-30%를 보조하는 제도를 통해 부담이 경감되고 있지만, 그 대상은 여전히 시범 사업 예산 범위 내로 제한되어 있습니다. 그 결과, 중국의 스마트 빌딩 시장에서는 양극화가 나타나고 있습니다. Tier 1 포트폴리오의 디지털화는 급속히 진행되는 반면, 분산된 중소기업의 자산은 뒤처지고 있습니다. 각 벤더들은 모듈식 키트, 단계적 도입, 수익 분배형 에너지 계약 등을 제공하며 대응하고 있지만, 자본 측면의 마찰은 여전히 전국적인 보급을 저해하는 구조적인 걸림돌로 작용하고 있습니다.
부문 분석
2025년, 중국의 스마트 빌딩 시장에서 빌딩 에너지 관리 시스템(BEMS)은 37.62%의 점유율을 차지했습니다. 이는 연면적 20,000 m²를 초과하는 건물에 대한 정보 공개 규정에 힘입은 결과입니다. 각 벤더사는 공조(HVAC), 조명, 태양광 발전 설비를 알고리즘에 통합하고 기상 및 이용 현황 패턴을 추적함으로써 이 부문을 성과 연계형 계약으로 이끌고 있습니다. 하드웨어의 이익률 하락은 에너지 절약을 보장하는 구독 모델로의 전환을 촉진하고 있습니다. 통합형 업무 공간 관리는 규모는 작지만, 하이브리드 근무의 동향과 실시간 공간 분석을 원하는 부동산 소유주 수요에 힘입어 연평균 성장률(CAGR) 15.12%로 확대되고 있습니다. 중국자원토지는 2024년에 280만 제곱미터에 걸쳐 워크플레이스 대시보드를 도입하고, 임차인의 공간을 최대 20%까지 줄임으로써 이 부문의 가치 제안을 입증했습니다.
에너지, 보안, 업무 공간 각 모듈은 단일 데이터 계층에서 점점 더 통합되고 있습니다. 인프라 관리 시스템은 신축 건물 건설량에 연동되어 완만하지만 꾸준한 성장을 보이고 있습니다. 방문자 추적에 관한 규정 준수 요구 사항이 높아지는 가운데, 보안은 여전히 필수적이지만, 개인정보 보호 규제로 인해 주택 단지에서의 얼굴 인식 기술 활용은 제한되고 있습니다. 조명 제어는 에너지 플랫폼에 통합되었으며, LED로 전환하는 것이 더 광범위한 자동화로의 진입점이 되고 있습니다. 여러 기능을 통합할 수 있는 크로스 도메인 벤더는 중국의 스마트 빌딩 시장 전체에서 번들 입찰을 수주하는 데 있어 가장 유리한 입장에 있습니다.
하드웨어는 2025년 매출의 54.88%를 차지했으나, 센서 및 컨트롤러 비용의 하락에 따라 가격 결정력은 약화되고 있습니다. 무선 5G 센서의 보급으로 게이트웨이 수요는 더욱 감소하고 있으며, 독자적인 기술을 보유하지 않은 제조업체들은 압박을 받고 있습니다. 고객이 원시 데이터가 아닌 인사이트력을 요구함에 따라 소프트웨어 계층, 분석, 운영 체제, 사이버 방어 분야의 전략적 중요성이 높아지고 있습니다. 지멘스의 ‘Desigo CC’로 대표되는 구독형 가격 책정은 현금 흐름을 안정시키고 고객 유지율을 높이고 있습니다.
2025년 시점에서는 규모가 가장 작은 서비스 부문이지만, 2031년까지 13.95%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 레거시 시스템을 둘러싼 통합의 복잡성이 전문 통합 업체에 대한 수요를 뒷받침하는 한편, 중소기업은 운영을 관리형 서비스 제공업체에 위탁하고 있습니다. 존슨 컨트롤즈의 ‘OpenBlue’는 중국 내 성과 연동형 계약을 기반으로 한 수주액이 2024년에 40% 증가하여, 성과 보장이 긍정적으로 받아들여지고 있음을 보여줍니다. 수익 창출 방식이 일회성 하드웨어 판매에서 라이프사이클 서비스로 전환되는 가운데, 현지에서 긴밀한 지원 네트워크를 갖춘 벤더들은 중국의 스마트 빌딩 시장 전체에서 점유율을 확대되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the China smart building market size is expected to grow from USD 96.31 billion in 2025 to USD 109.35 billion in 2026 and is forecast to reach USD 206.44 billion by 2031 at 13.55% CAGR over 2026-2031.
This report is Segmented by Solution (Building Energy Management Systems, Infrastructure Management Systems, Intelligent Security Systems, Integrated Workplace Management Platforms, and More), Component (Hardware, Software, Services), Connectivity Type (Wired, Wireless), Building Type (Residential, Commercial, Industrial), and Geography. Market Forecasts are Provided in Terms of Value (USD).
China Smart Building Market Trends and Insights
Expanding Government Smart City Initiatives
Beijing's 2024 guideline commits CNY 1.2 trillion (USD 165 billion) through 2027 to digitalize municipal services, treating smart buildings as core infrastructure alongside 5G and data centers. The directive covers 16 demonstration zones and requires new public buildings above 10,000 m2 to connect with city data platforms by 2026. Compliance timetables are driving a surge in turnkey projects, favoring vendors able to integrate automation, security, and energy modules under a single architecture. Local governments tie subsidy eligibility to adherence with the Ministry of Housing's 2024 smart-building technical specification, effectively raising market-entry barriers.As a result, the Chinese smart building market experiences policy-induced demand certainty even amid broader real-estate volatility.
Rising Demand for Energy-Efficient Retrofits in Existing Buildings
Roughly 60% of China's building stock predates the 2010 energy codes, representing more than 20 billion square meters of retrofit potential.The carbon peaking plan targets a 15% reduction in operational emissions by 2030, with retrofits accounting for half of the reduction. The People's Bank of China extended its carbon-reduction facility to cover building energy-management projects at an interest rate of 1.75%, trimming payback periods for landlords. Fourteen provinces now require energy-performance disclosure at lease renewal, creating rental premiums for smart-enabled assets, as seen in Shanghai, where automated buildings achieved 8-12% higher rents in 2024. These incentives convert energy systems from cost centers into revenue enhancers, sustaining double-digit uptake across the Chinese smart building market.
High Upfront Capital Expenditure for SMEs
Comprehensive smart retrofits cost up to USD 200 per m2, a hurdle for SMEs that hold 40% of commercial floor area but earn rental yields of only 4-6%. Commercial lending rates of 4.5-6.0% neutralize central-bank concessional lines reserved for state developers, stretching paybacks to 8-12 years. Subsidies covering 20-30% of costs in Zhejiang and Guangdong ease the burden yet remain confined to pilot budgets. As a result, the China smart building market shows bifurcation: tier-1 portfolios digitize rapidly while fragmented SME assets lag. Vendors are responding by offering modular kits, phased rollouts, and revenue-sharing energy contracts, but capital friction persists as a structural brake on nationwide penetration.
Other drivers and restraints analyzed in the detailed report include:
- Integration of 5G and AIoT Platforms in Building Automation
- Growing Corporate Net-Zero Carbon Commitments
- Shortage of Certified Smart-Building Facility Managers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Building energy management systems captured 37.62% of the Chinese smart building market share in 2025, supported by disclosure rules for properties above 20,000 m2. Vendors bundle HVAC, lighting, and solar assets into algorithms that track weather and occupancy patterns, pushing the segment toward outcome-based contracts. Sliding hardware margins facilitate a shift to subscription models that ensure energy savings. Integrated workplace management, though smaller, is advancing at a 15.12% CAGR, helped by hybrid work trends and landlord demand for real-time space analytics. China Resources Land rolled out workplace dashboards across 2.8 million square meters in 2024, reducing tenant space by up to 20% and validating the segment's value proposition.
Energy, security, and workplace modules increasingly converge on a single data layer. Infrastructure management systems offer steady if slower growth tied to new-build volume. Security remains essential amid rising compliance requirements for visitor tracking, but privacy curbs limit the use of facial recognition in residential complexes. Lighting controls fold into energy platforms, with LED retrofits serving as entry points for broader automation. Cross-domain vendors that can stitch multiple functions together are best positioned to win bundled tenders across the Chinese smart building market.
Hardware generated 54.88% of 2025 revenue, yet it is losing pricing power as sensor and controller costs decline. Wireless 5G sensors further erode gateway demand, pressuring manufacturers that lack proprietary technology. Software layers, analytics, operating systems, and cyber-defense rise in strategic weight as clients seek insight rather than raw data. Subscription pricing, exemplified by Siemens Desigo CC, smooths cash flow and deepens stickiness.
Services, the smallest component in 2025, are on track for the fastest 13.95% CAGR through 2031. Integration complexity around legacy systems fuels demand for specialist integrators, while SMEs outsource operations to managed-service providers. Johnson Controls' OpenBlue bookings in China increased by 40% in 2024 under outcome-based contracts, demonstrating the acceptance of performance guarantees. As monetization shifts from one-off hardware sales to life-cycle services, vendors with dense local support networks gain market share across the entire China smart building market spectrum.
Complete Report Scope:
- By Solution
- Building Energy Management Systems
- Infrastructure Management Systems
- Intelligent Security Systems
- Integrated Workplace Management Platforms
- Lighting Control Systems
- By Component
- Hardware
- Software
- Services
- By Connectivity Type
- Wired
- Wireless
- By Building Type
- Residential
- Commercial
- Industrial
List of Companies Covered in this Report:
- Johnson Controls International plc
- Siemens Aktiengesellschaft
- Honeywell International Inc.
- Schneider Electric SE
- ABB Ltd.
- Azbil Corporation
- Hitachi Ltd.
- Huawei Technologies Co., Ltd.
- Cisco Systems, Inc.
- Xiaomi Corporation
- Zhejiang Dahua Technology Co., Ltd.
- Zhejiang Uniview Technologies Co., Ltd.
- SenseTime Group Inc.
- Shanghai Yunding Network Technology Co., Ltd. (Tuyasmart)
- Inspur Group Co., Ltd.
- Beijing Megvii Technology Limited
- Foxconn Industrial Internet Co., Ltd.
- Legrand (China) Co., Ltd.
- Delta Electronics (China) Co., Ltd.
- Advantech Co., Ltd.
- Gree Electric Appliances, Inc. of Zhuhai
- Hisense Smart Technology Co., Ltd.
- Broad Group Co., Ltd.
- Hollysys Automation Technologies Ltd.
- iSoftStone Information Technology (Group) Co., Ltd.
- Hikvision Digital Technology Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding Government Smart City Initiatives
- 4.2.2 Rising Demand for Energy-Efficient Retrofits in Existing Buildings
- 4.2.3 Integration of 5G and AIoT Platforms in Building Automation
- 4.2.4 Growing Corporate Net-Zero Carbon Commitments
- 4.2.5 Rapid Growth of Smart Property Management Services
- 4.2.6 Emergence of Digital Twin-Based Urban Planning Mandates
- 4.3 Market Restraints
- 4.3.1 High Upfront Capital Expenditure for SMEs
- 4.3.2 Fragmented Building Communication Protocols
- 4.3.3 Data Privacy and Cyber-Security Compliance Gaps
- 4.3.4 Shortage of Certified Smart-Building Facility Managers
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution
- 5.1.1 Building Energy Management Systems
- 5.1.2 Infrastructure Management Systems
- 5.1.3 Intelligent Security Systems
- 5.1.4 Integrated Workplace Management Platforms
- 5.1.5 Lighting Control Systems
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.2 Software
- 5.2.3 Services
- 5.3 By Connectivity Type
- 5.3.1 Wired
- 5.3.2 Wireless
- 5.4 By Building Type
- 5.4.1 Residential
- 5.4.2 Commercial
- 5.4.3 Industrial
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Johnson Controls International plc
- 6.4.2 Siemens Aktiengesellschaft
- 6.4.3 Honeywell International Inc.
- 6.4.4 Schneider Electric SE
- 6.4.5 ABB Ltd.
- 6.4.6 Azbil Corporation
- 6.4.7 Hitachi Ltd.
- 6.4.8 Huawei Technologies Co., Ltd.
- 6.4.9 Cisco Systems, Inc.
- 6.4.10 Xiaomi Corporation
- 6.4.11 Zhejiang Dahua Technology Co., Ltd.
- 6.4.12 Zhejiang Uniview Technologies Co., Ltd.
- 6.4.13 SenseTime Group Inc.
- 6.4.14 Shanghai Yunding Network Technology Co., Ltd. (Tuyasmart)
- 6.4.15 Inspur Group Co., Ltd.
- 6.4.16 Beijing Megvii Technology Limited
- 6.4.17 Foxconn Industrial Internet Co., Ltd.
- 6.4.18 Legrand (China) Co., Ltd.
- 6.4.19 Delta Electronics (China) Co., Ltd.
- 6.4.20 Advantech Co., Ltd.
- 6.4.21 Gree Electric Appliances, Inc. of Zhuhai
- 6.4.22 Hisense Smart Technology Co., Ltd.
- 6.4.23 Broad Group Co., Ltd.
- 6.4.24 Hollysys Automation Technologies Ltd.
- 6.4.25 iSoftStone Information Technology (Group) Co., Ltd.
- 6.4.26 Hikvision Digital Technology Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


