

|
시장보고서
상품코드
2154309
필리핀의 카톤보드 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Philippines Cartonboard - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
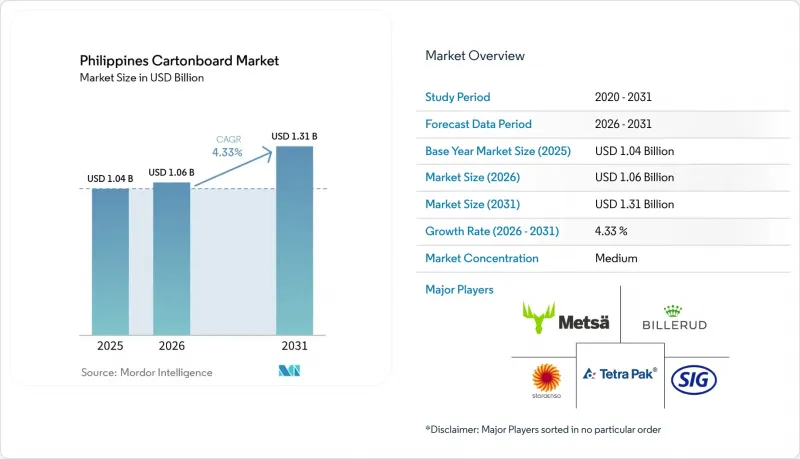
에 따르면 필리핀의 판지 시장 규모는 2025년 10억 4,000만 달러, 2026년 10억 6,000만 달러에서 2031년까지 13억 1,000만 달러로 확대할 것으로 예측되고 있으며, 2026-2031년까지 연평균 성장률(CAGR)은 4.33%에 달할 전망입니다.
필리핀 판지 시장의 동향 및 인사이트
고급 소매용 및 진열용 골판지 포장에 대한 수요 증가
필리핀에서 현대적인 소매업이 부상함에 따라 소매 진열 기준이 높아지고 있으며, 이에 따라 더 높은 인쇄 품질과 견고한 구조를 갖춘 ‘진열용’ 골판지 포맷에 대한 수요가 증가하고 있습니다. 조직화된 소매 그룹과 상품 진열을 중시하는 매장 형태는 브랜드 소유주들에게 무지 2차 외부 포장 상자에 그치지 않고, 더 많은 카테고리에서 고평량 접이식 상자용 판지(FBB)나 코팅지로의 전환을 촉진하고 있습니다. 태국이나 인도네시아에서 수입된 제품은 이미 정돈된 진열 가능한 형태로 시장에 유통되고 있으며, 같은 매장에서 판매하는 국내 제조업체에게 상품 진열 기준이 서서히 높아지고 있습니다. 또한 소매업체들은 진열성을 중시한 대형 패키지의 자체 브랜드 상품을 확대하고 있으며, 이로 인해 플렉서블 파우치로 대체되는 대신 접이식 골판지 사용이 증가하고 있습니다. 이는 필리핀 골판지 시장에 중요한 의미를 지닙니다. 왜냐하면 기초가 되는 소비자 수요가 정체되어 있더라도, 가공 단위당 골판지의 부가가치를 높이는 결과로 이어지기 때문입니다. 또한 식품, 퍼스널 케어, 헬스케어 포장 분야에서 인쇄 품질, 진열 적합성, 그리고 진열대에서의 통일감이 가공업체 선정에 있으며, 여전히 중요한 요소로 남아 있게 될 것입니다.
포장 식품 및 음료 소비의 확대
포장 식품 및 음료 생산의 확대는 카톤, 슬리브, 액체용 패키지에 걸쳐 지속적인 수요를 창출하므로, 여전히 필리핀 판지 시장의 기반을 이루고 있습니다. 2026년에는 식품 및 음료 제조 부문이 5% 성장할 것으로 예측되며, 이는 인쇄가 가능하고 보호 기능을 갖춘 2차 포장이 필요한 비스킷, 레토르트 식품, 유제품, 상비 식품 분야의 판지 수요를 지원할 것입니다. 상온 보관이 가능한 식사나 수프는 특히 중요한데, 이러한 카테고리에서는 보관 및 유통 과정에서 제품의 품질을 보호하고 명확한 표시가 가능한 포장이 필수적이기 때문입니다. 또한 중부 루손 및 카라바존 지역의 식품 가공에 대한 투자는 일반적으로 포장 수요를 견인하므로 이러한 추세는 중요하며 산업 회랑에 인접한 컨버터의 수주를 지원합니다. 따라서 수요 기반은 단일 식품 카테고리에 집중되어 있는 것이 아니라 광범위한 범위에 걸쳐 있으며, 이로 인해 필리핀의 판지 시장은 특정 카테고리의 변화에만 더 탄력적에 대응할 수 있게 되었습니다. 또한 이는 현대적인 소매업과 전통적 유통업 모두를 통해 유통되는 제품에 대해 판지가 실용적인 포장 기판으로서의 역할을 더욱 공고히 하고 있습니다.
수입 섬유 및 펄프 비용의 변동
필리핀 판지 시장은 가공업체들이 국내산 버진 보드를 통한 헤지 수단이 없기 때문에 수입 섬유 및 펄프 비용 변동의 영향을 지속적으로 받고 있습니다. 전 세계 제지 원료 가격이나 운임이 상승하면, 고급 등급의 판지는 해외 공급업체로부터 조달되고 있으므로 가공업체들은 즉시 이익률 압박을 느끼게 됩니다. 이러한 압박은 외식 산업, 가정용품 및 대중용 FMCG(일용소비재) 계약에서 가격 경쟁을 피할 수 없는 중견 가공업체들에게 더욱 감당하기 어렵습니다. 2026년, DTI(필리핀 무역산업부)는 수입 골판지 원지에 대한 세이프가드 관세 도입안을 기각했습니다. 이로 인해 국내 구매자들은 국제적인 가격 변동 주기에 완전히 노출되게 되었습니다. 필리핀 골판지 시장에 미치는 영향은 투입 비용의 불확실성이 높아질 뿐만 아니라, 이미 운전자금이 부족한 상황에서 투자 결정이 지연되는 점에도 있습니다. 또한 원자재 가격 변동이 가공업체가 비용을 전가하기보다 더 빨리 영향을 미치는 시장에서는 고객과의 계약 가격 책정도 더욱 어려워집니다.
부문별 분석
2025년, 필리핀 골판지 시장에서는 접이식 골판지(Folding Boxboard)가 33.12%의 시장 점유율을 차지하며, 동 시장의 다른 제품 등급을 크게 앞질렀습니다. 이러한 우위는 균형 잡힌 비용, 신뢰할 수 있는 가공 특성, 그리고 식품, 화장품, 의약품, 담배의 2차 포장에 걸친 폭넓은 용도에서 기인합니다. 또한 해외의 확고한 제지 공장에서 코팅 처리된 수입품이 공급되고 있으며, 컨버터들은 브랜드 소매 포장 인쇄 기준을 유지하기 쉽다는 점에서도 이 등급을 선호하고 있습니다. 필리핀 골판지 업계에서 이러한 다용도성과 가공 용이성이 결합되어, 접이식 골판지는 광범위한 주류 소비자용 용도에서 기본 선택지가 되고 있습니다. 표백되지 않은 단단한 판지는 백도, 인쇄 정밀도 및 무단 개봉 방지 구조가 중요한 고급 담배 및 헬스케어 제품 포장 분야에서 여전히 중요한 위치를 차지하고 있습니다.
‘화이트 라이닝 칩보드’는 가정용품 및 일반 상품 포장에서 가격 주도형 역할을 유지하고 있는 반면, ‘무표백 판지’는 무게가 더 나가는 소매용 디스플레이나 라미네이트 가공된 외부 포장에 사용되고 있습니다. ‘액체 포장용 판지’는 2031년까지 연평균 성장률(CAGR) 5.51%로 성장할 것으로 예측되며, 필리핀 판지 시장에서 가장 빠르게 성장하는 등급입니다. 이러한 성장세는 무균 음료에 대한 관심 증가, 섬유 기반 포장 형태로의 광범위한 전환, 그리고 사용 후 골판지 회수 시스템에 대한 관심 고조를 반영하고 있습니다. 소형 무균 포장 옵션의 확대 또한 이 등급이 핵심 가치 제안을 변경하지 않으면서도 가격에 민감한 사용 사례로의 진출을 촉진할 것입니다. 식품 서비스용 판지 시장 규모는 여전히 작지만, 메트로 마닐라와 세부에서 도시 지역의 테이크아웃 및 배달 수요가 증가함에 따라 종이컵, 클램쉘 용기, 테이크아웃 용기에 대한 수요가 늘어나면서 그 중요성이 커지고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 거시경제 요인이 시장에 미치는 영향
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 업계 밸류체인 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 등급별
- 포장 형태별
- 최종사용자 산업별
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Tetra Pak International S.A.
- SIG Group AG
- Stora Enso Oyj
- Billerud AB
- Metsa Board Corporation
- International Paper Company
- WestRock Company
- Smurfit Westrock plc
- Mondi plc
- Nippon Paper Industries Co., Ltd.
- Oji Holdings Corporation
- Nine Dragons Paper Holdings Limited
- SCG Packaging Public Company Limited
- Asia Pulp and Paper Co., Ltd.
- UPM-Kymmene Corporation
- Mayr-Melnhof Karton AG
- Sappi Limited
- Graphic Packaging International, LLC
- Packaging Corporation of America
- Rengo Co., Ltd.
- DNP Group
제7장 시장 기회와 향후 전망
KSA 26.10.23According to Mordor Intelligence, the Philippines cartonboard market size is projected to expand from USD 1.04 billion in 2025 and USD 1.06 billion in 2026 to USD 1.31 billion by 2031, registering a CAGR of 4.33% between 2026 and 2031.
Philippines Cartonboard Market Trends and Insights
Rising Demand For Premium Retail And Shelf-Ready Cartonboard Packaging
Modern trade in the Philippines has pushed retail presentation standards higher, which is raising the need for shelf-ready carton formats with better print quality and stronger structural finish. Organized retail groups and presentation-led store formats are encouraging brand owners to move beyond plain secondary outers and into higher-grammage folding boxboard and coated substrates in more categories. Imported products from Thailand and Indonesia already arrive in cleaner shelf-ready formats, and that is quietly raising the presentation benchmark for domestic manufacturers that sell into the same aisles. Retailers are also expanding private-label products in larger presentation-focused packs, which supports more folding carton use rather than flexible pouch substitution. This matters for the Philippines cartonboard market because it supports higher board value per converted unit, even when underlying consumer demand remains steady. It also keeps print quality, display readiness, and shelf consistency central to converter selection in food, personal care, and healthcare packaging.
Expansion Of Packaged Food And Beverage Consumption
Expansion in packaged food and beverage output continues to anchor the Philippines cartonboard market because it creates recurring demand across cartons, sleeves, and liquid packs. In 2026, the food and beverage manufacturing sector is projected to grow 5%, which supports carton demand in biscuits, ready meals, dairy, and pantry staples that need printable and protective secondary packaging. Shelf-stable meals and soups are especially relevant because these categories depend on packaging that protects product quality and supports clear labeling during storage and distribution. This pattern also matters because food processing investment in Central Luzon and CALABARZON usually pulls packaging demand with it, which strengthens order flow for converters near industrial corridors. The demand base is therefore broad rather than concentrated in a single food line, which makes the Philippines cartonboard market more resilient to changes in one category alone. It also reinforces the role of cartonboard as a practical packaging substrate for products that move through both modern retail and traditional trade.
Volatility In Imported Fiber And Pulp Costs
The Philippines cartonboard market remains exposed to imported fiber and pulp costs because the converting base does not have a local virgin-board hedge. When global paper inputs or freight rates rise, converters feel margin pressure quickly because premium board grades are sourced from overseas suppliers. That pressure is harder to absorb for mid-tier converters that compete on price in foodservice, household, and mass FMCG contracts. In 2026, the DTI rejected a proposal for a safeguard duty on imported corrugating medium paper, which left local buyers fully exposed to international pricing cycles. The effect on the Philippines cartonboard market is not only higher input uncertainty, but also slower investment decisions when working capital is already stretched. It also makes customer contract pricing more difficult in a market where raw material swings can reach converters faster than they can pass costs forward.
Other drivers and restraints analyzed in the detailed report include:
- Growth In Aseptic And Shelf-Stable Carton Applications
- E-Commerce-Driven Secondary Packaging Demand
- Limited Local Integrated Cartonboard Capacity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Folding Boxboard held 33.12% of the Philippines cartonboard market share in 2025, which kept it well ahead of other product grades in the Philippines cartonboard market. Its lead comes from balanced cost, dependable converting behavior, and wide use across food, cosmetics, pharmaceutical, and tobacco secondary packs. Converters also favor this grade because coated imported supply is available from established overseas mills, which helps them maintain print standards for branded retail packaging. In the Philippines cartonboard industry, that combination of versatility and converting ease makes Folding Boxboard the default choice for a wide range of mainstream consumer applications. Solid Bleached Board stays important in premium tobacco and healthcare packs where brightness, print precision, and tamper-evident structures matter.
White-Lined Chipboard keeps a price-led role in household and general merchandise packaging, while Solid Unbleached Board serves heavier retail displays and laminated outer packs. Liquid Packaging Board is projected to grow at 5.51% CAGR through 2031, which makes it the fastest-moving grade in the Philippines cartonboard market. That momentum reflects stronger aseptic beverage interest, a wider push toward fiber-based formats, and rising attention to used-carton recovery systems. The expansion of smaller aseptic pack options should also help the grade reach more price-sensitive use cases without changing its core value proposition. Food Service Board remains smaller, but it is gaining relevance as urban takeaway and delivery demand lift paperboard cups, clamshells, and carry containers in Metro Manila and Cebu.
Complete Report Scope:
- By Product Grade
- Solid Bleached Board
- Solid Unbleached Board
- Folding Boxboard
- White-Lined Chipboard
- Liquid Packaging Board
- Food Service Board
- By Packaging Format
- Folding Cartons
- Liquid Packaging
- Sleeve and Tray
- Other Packaging Formats (Cups, Foodservice Containers)
- By End-User Industry
- Food
- Beverage
- Pharmaceutical and Healthcare
- Tobacco
- Cosmetics and Toiletries
- Other End-User Industries (Toy, Apparel, Automotive, Household, Electrical, Foodservice)
List of Companies Covered in this Report:
- Tetra Pak International S.A.
- SIG Group AG
- Stora Enso Oyj
- Billerud AB
- Metsa Board Corporation
- International Paper Company
- WestRock Company
- Smurfit Westrock plc
- Mondi plc
- Nippon Paper Industries Co., Ltd.
- Oji Holdings Corporation
- Nine Dragons Paper Holdings Limited
- SCG Packaging Public Company Limited
- Asia Pulp and Paper Co., Ltd.
- UPM-Kymmene Corporation
- Mayr-Melnhof Karton AG
- Sappi Limited
- Graphic Packaging International, LLC
- Packaging Corporation of America
- Rengo Co., Ltd.
- DNP Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 Rising Demand for Premium Retail and Shelf-Ready Cartonboard Packaging
- 4.3.2 Expansion of Packaged Food and Beverage Consumption
- 4.3.3 Growth in Aseptic and Shelf-Stable Carton Applications
- 4.3.4 E-Commerce-Driven Secondary Packaging Demand
- 4.3.5 Rising Sustainability Preference for Fiber-Based Packaging
- 4.3.6 Brand Migration From Plastic to Paperboard Cartons
- 4.4 Market Restraints
- 4.4.1 Volatility in Imported Fiber and Pulp Costs
- 4.4.2 Limited Local Integrated Cartonboard Capacity
- 4.4.3 Moisture Sensitivity and Barrier Performance Constraints
- 4.4.4 Price Competition From Alternative Packaging Substrates
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Grade
- 5.1.1 Solid Bleached Board
- 5.1.2 Solid Unbleached Board
- 5.1.3 Folding Boxboard
- 5.1.4 White-Lined Chipboard
- 5.1.5 Liquid Packaging Board
- 5.1.6 Food Service Board
- 5.2 By Packaging Format
- 5.2.1 Folding Cartons
- 5.2.2 Liquid Packaging
- 5.2.3 Sleeve and Tray
- 5.2.4 Other Packaging Formats (Cups, Foodservice Containers)
- 5.3 By End-User Industry
- 5.3.1 Food
- 5.3.2 Beverage
- 5.3.3 Pharmaceutical and Healthcare
- 5.3.4 Tobacco
- 5.3.5 Cosmetics and Toiletries
- 5.3.6 Other End-User Industries (Toy, Apparel, Automotive, Household, Electrical, Foodservice)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Tetra Pak International S.A.
- 6.4.2 SIG Group AG
- 6.4.3 Stora Enso Oyj
- 6.4.4 Billerud AB
- 6.4.5 Metsa Board Corporation
- 6.4.6 International Paper Company
- 6.4.7 WestRock Company
- 6.4.8 Smurfit Westrock plc
- 6.4.9 Mondi plc
- 6.4.10 Nippon Paper Industries Co., Ltd.
- 6.4.11 Oji Holdings Corporation
- 6.4.12 Nine Dragons Paper Holdings Limited
- 6.4.13 SCG Packaging Public Company Limited
- 6.4.14 Asia Pulp and Paper Co., Ltd.
- 6.4.15 UPM-Kymmene Corporation
- 6.4.16 Mayr-Melnhof Karton AG
- 6.4.17 Sappi Limited
- 6.4.18 Graphic Packaging International, LLC
- 6.4.19 Packaging Corporation of America
- 6.4.20 Rengo Co., Ltd.
- 6.4.21 DNP Group
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and unmet-need assessment


